Playboy Posts Its Most Profitable Quarter Of The Turnaround As China Licensing Revives, But Slowing Honey Birdette Growth And A Cash-Funded Miami Club Muddy The Asset-Light Story
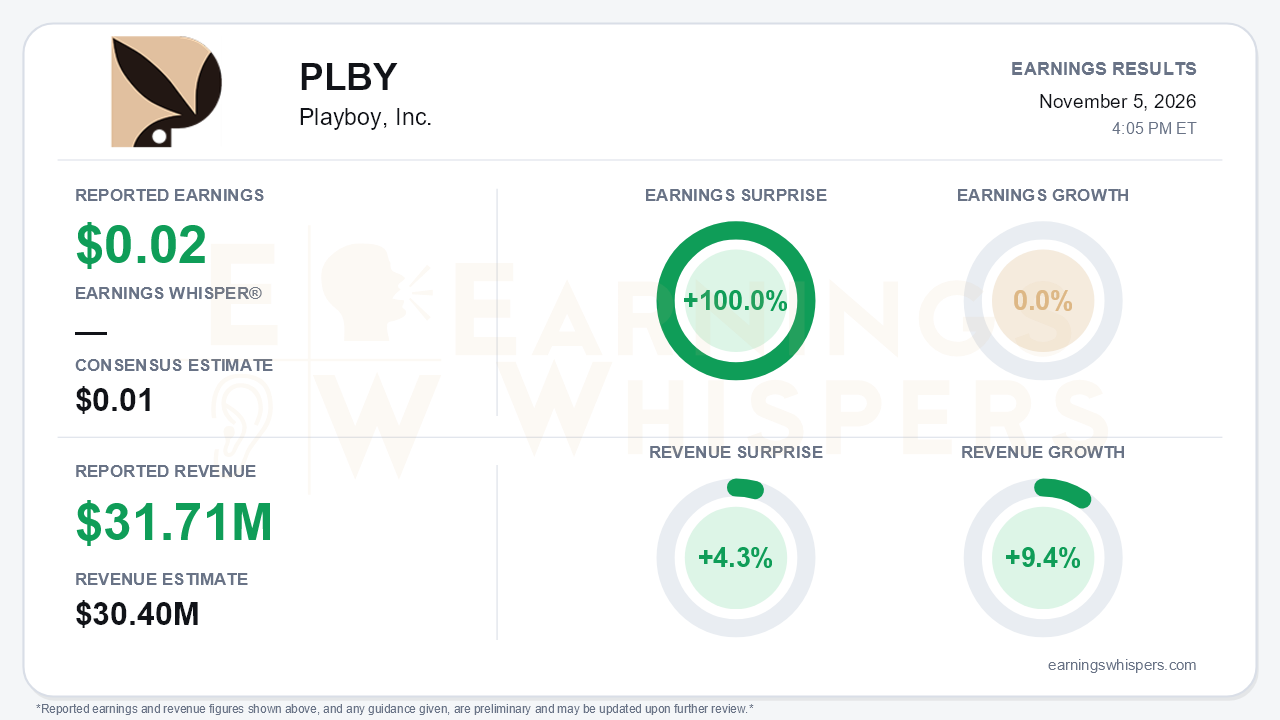
Playboy, Inc. (NASDAQ: PLBY) delivered its cleanest profitability print of the turnaround. Earnings came in at $0.02 per share against a $0.01 consensus, a 100.0% surprise, on revenue of $31.71 million, which topped the $30.4 million estimate by 4.3% and grew 9.4% year over year. On the supplied comparison, per-share earnings growth was 0.0%, but that figure understates the shift: net income roughly quadrupled to $1.9 million from $0.5 million, operating income nearly tripled to $4.0 million, and adjusted EBITDA nearly doubled to $7.9 million, a 25% margin and the seventh straight positive quarter. The central tension is that profitability is clearly inflecting while the top-line engine that carried the past year, Honey Birdette, is losing speed, just as management commits balance-sheet cash to a hospitality project.
The quality of the GAAP beat deserves some scrutiny. Operating expenses were essentially flat at $27.7 million, but the operating income gain partly reflected lower legal expenses and the release of a U.S. sales tax reserve, which helped drive $864,000 of other operating income against almost nothing a year ago. Interest expense also rose to $2.6 million from $1.9 million, so the improvement is coming despite a heavier financing burden. Adjusted EBITDA benefited from adding back $2.2 million of stock-based compensation, nearly double last year's level. Still, the sequential trend is real: adjusted EBITDA has moved from $5.0 million in Q1 to $7.0 million in Q2 and $7.9 million now, and net income improved from roughly breakeven in Q2 and a loss in Q1.
The most encouraging development was licensing. Revenue in the segment rose to $12.6 million, up 5.3%, accelerating from $11.2 million (+2%) in Q2 and $10.9 million in Q1. China royalties jumped about 40%, or $1.2 million, after three new agreements with roughly $15 million in combined contract value, reversing the transition pause of the first half. Licensing segment operating income climbed 41% to $10.9 million. Management also re-signed its largest apparel licensee for five years with minimum guarantees up roughly tenfold, landed its first six-figure sponsorship, and, in a firmer stance than on prior calls, said it expects China growth through the first half of 2027 and rest-of-world licensing to return to growth in 2027. The magazine relaunch and paid-voting franchise, which topped $1 million in revenue, add a modest but growing content layer.
Bears have legitimate ammunition beneath that. Honey Birdette revenue grew 12.1% to $18.4 million, down from 18% growth in Q2 and 15% in Q1, with comps slowing to 11% from 15%. Margins kept improving: the release cites direct-to-consumer gross margin of 62.2% versus 60.8%, while the call put Honey Birdette at 63% versus 61%, and adjusted operating income doubled to $2.4 million. But the Q1 plan to open five U.S. stores has given way to rationalization, with the count down to 48 from 51 and two more closures planned. Rest-of-world licensing was flat excluding prior-year audit settlements, sponsorships ramped slower than hoped, and contracted unrecognized licensing revenue has drifted to $324 million from $343 million at year-end. The larger apparel guarantee will also make early quarters of each contract year look lighter.
The Miami Beach club is the strategic wildcard. Playboy agreed to buy the Freehand Hotel property and will commit about $5 million of its own cash, with the club consolidated, a notable departure from the Q2 framing of growing hospitality without risking company capital. Management expects to recoup the investment through membership sales, but timing is undefined, and the cash appears to come at the expense of further buybacks. Cash fell to $34.9 million from $37.1 million after a $3 million repurchase installment, against $144.9 million of debt, though management reaffirmed a path to roughly $108 million by January 2028.
The market setup is more complicated than the surprise implies. Shares closed at $1.37 ahead of the report, down 9.3% from the $1.51 open after the August release and about 4% below the 200-day moving average. The stock slid to a 52-week low of $0.95 on October 14 before rebounding 44%, so some recovery was already underway. Investor sentiment remained negative but improved meaningfully, rising to -0.18 from -0.32, and Earnings Whispers momentum and AVWAP trend readings have turned positive, consistent with that rebound.
The bottom line is that Playboy proved its asset-light licensing model can generate genuine operating leverage, and the China revival plus the apparel renewal give the licensing story more visibility than it had a quarter ago. Against that, a decelerating Honey Birdette, a shrinking store base, a slipping contracted backlog, and a cash-funded hospitality bet on a leveraged balance sheet keep this a show-me story rather than a settled turnaround.
Read our earnings preview for Playboy, Inc.: https://www.earningswhispers.com/article/PLBY/22361
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-19 | |
| Sep-30 | |
| Sep-21 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Jul-27 | |
| Jul-22 | |
| Jun-29 | |
| Jun-22 | |
| Jun-11 |
