Paylocity's Conservative Guide Faces Its First Test As AI Push And Rerating Raise The Bar
Paylocity enters its fiscal first-quarter report with a familiar puzzle. The company just finished a year in which recurring revenue growth reaccelerated to above 12%, yet it opened the new year with a guide implying roughly 7% total revenue growth. Management raised its outlook every quarter last year, so the market has learned to treat that opening number as a floor. The stock has rallied on that assumption. The September quarter is the first chance to see whether the gap between the guide and actual performance is as wide as investors now seem to believe.
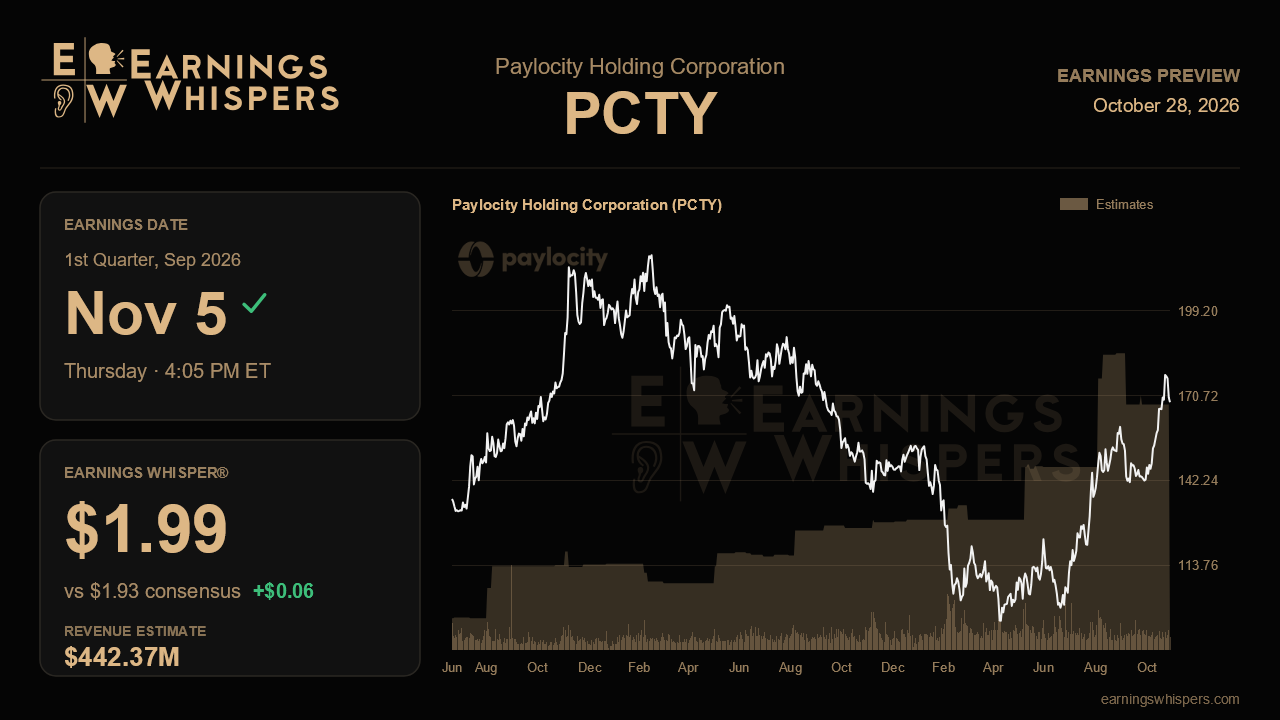
The Street is looking for non-GAAP earnings of $1.93 a share on revenue of $442.4 million, up 8.4% from $408.2 million a year ago. Management guided to $439.5 million to $444.5 million, so consensus sits in the upper half of that range but not at the ceiling. Last quarter Paylocity cleared the top of its revenue guide by $11.3 million. A repeat of that kind of beat would push revenue into the mid-$450 millions and would bring growth back toward double digits. The Earnings Whisper of $1.99 sits modestly above consensus. That points to a buy-side expectation of another clean beat, not just an in-line print. For the full fiscal year, management's $1.880 billion to $1.895 billion outlook is the number most likely to move the stock. A lift toward the high end, or above it, would confirm that the conservative playbook is intact.
The underlying drivers matter more than the headline beat. Management's guide assumes flat client workforce levels, a step down from the year-over-year gains seen throughout last year. Any evidence that employment at client companies is holding up would be an easy source of upside. Signs of softening would test the idea that the guide is padded. Recurring revenue growth is the cleanest gauge here. A quarter that holds near the 12% pace would validate the reacceleration story. A slide toward the 8% full-year assumption would suggest the conservatism was simply realism.
The newer catalysts deserve scrutiny too, because they underpin the argument that average revenue per client can keep climbing beyond last year's roughly 5% gain. Ignite AI now carries directly monetizable premium agents, and AI interactions nearly doubled sequentially last quarter. Adora's leave management tool and the Grayscale recruiting integration are being packaged as premium offerings. Paylocity Retirement launched in June, and the Elevate managed-services line is ramping. It is too early for these to move revenue materially. Still, early attach rates, pricing traction and commentary on how the sales force is absorbing so many launches at once will reveal whether the product wave is real or still mostly a slide deck. That question carries extra weight given lingering market worries that AI could erode employment levels and, with them, seat-based pricing.
On profitability, the change in amortization of deferred contract costs from seven to eight years should add roughly 120 to 140 basis points to adjusted EBITDA margin this year. Margin strength will therefore partly reflect accounting rather than operations. Investors should look past that tailwind to see whether underlying leverage persists while subscale acquisitions weigh slightly. Free cash flow comparisons will look tougher as the company laps a one-time tax benefit of about $65 million.
Sentiment has shifted noticeably. Readings have improved from deeply bearish before last quarter's report to only mildly bearish now. Shares have gained 13.4% since the last report while the S&P 500 slipped 0.8%. At about $170, the stock trades well above its 200-day average near $126 and in the upper part of its post-earnings range, roughly 5% below the $178.53 high. That rerating means a merely in-line quarter may not be enough. To keep the narrative intact, Paylocity needs to show that recurring growth is outrunning its flat-employment guide and then raise the full-year outlook accordingly.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-13 | |
| Oct-13 | |
| Oct-05 | |
| Sep-29 | |
| Sep-28 | |
| Sep-22 | |
| Sep-10 | |
| Aug-25 | |
| Aug-11 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-21 |
