Paylocity Beats And Raises, But Rising Float Income Does Much Of The Lifting As Core Growth Slows
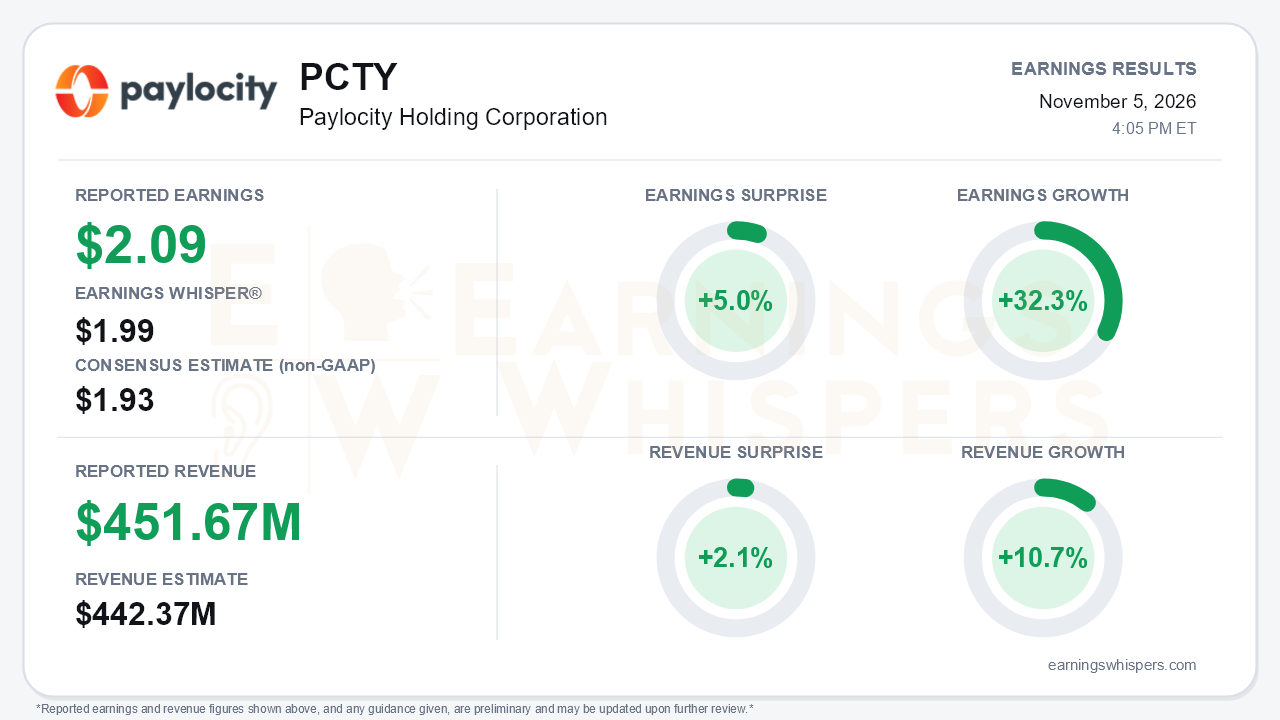
Paylocity opened fiscal 2027 with a clean beat and a raise larger than the beat. Non-GAAP earnings of $2.09 per share topped the $1.93 consensus and the $1.99 Earnings Whisper number by 5.0%, and grew 32.3% from a year ago. Revenue of $451.7 million rose 10.7%, beat consensus by 2.1%, and finished $7.2 million above the top of management's own guidance. Full-year total revenue guidance rose $30 million at the midpoint. That is the headline. The central tension is that a meaningful share of the upgrade comes from interest rates rather than the core payroll and HCM business, and the company's own outlook still implies slower growth in that core business through the rest of the year.
The quality of the beat deserves scrutiny. Recurring and other revenue grew 12.0% to $424.5 million, which is a solid result. Interest income on client funds, however, fell to $27.2 million from $29.3 million a year ago. The 32.3% EPS growth was also helped by capital return. Diluted shares fell about 4% after aggressive buybacks, and the tax line was lighter. Non-GAAP net income rose a more modest 14.9%, from $97.7 million to $112.2 million. GAAP EPS climbed to $1.07 from $0.86. Underneath, adjusted gross margin declined year over year, a reversal from the 60-basis-point expansion posted in fiscal Q2 2026. Management attributed the decline to staffing timing for the new Elevate and Retirement offerings. Cash generation also softened in the quarter. Operating cash flow slipped to $79.7 million from $86.5 million, and free cash flow fell to $56.1 million from $67.2 million, although the trailing-twelve-month free cash flow margin improved to 23.0% from 20.5%.
The call preserved a credible growth story, but not an accelerating one. Management again described demand as 'stable,' perhaps with 'arrows up a little,' language that has appeared on prior calls as well. Client workforce levels are running up roughly half a point to a point, yet guidance still assumes they stay flat. The product narrative was more assertive. Recruiting Optimizer launched as a paid AI module, with early data citing 35% recruiter productivity gains and 25% faster fills. Ignite AI has answered roughly 30 million questions, and usage of its insight agent rose more than 90% in a month. Elevate and Retirement are attaching across segments in their first full quarter. The July acquisition of Aidora adds an AI leave-management module that management expects to monetize. Beauchamp said he is 'more excited than a year or two ago,' and the tone on AI monetization was clearly firmer.
Bears have legitimate ammunition in the guidance mix. Roughly half of the $30 million total revenue raise reflects float income, now projected at about $118 million versus $103 million. That change follows a September rate hike that replaced the two cuts the company assumed in August. The adjusted EBITDA guide rose to $711.5-$721.5 million. Ex-float EBITDA, by contrast, moved up only modestly to $593.5-$603.5 million, implying about 90 basis points of margin leverage versus 80 previously. An analyst noted the ex-float EBITDA beat was the smallest in company history, as R&D spending rose about 15% year over year. Second-quarter recurring guidance of roughly 10%, and about 9% for the full year, implies deceleration from Q1's 12%. Management noted that the Q2 guide mirrors the conservative cadence it used for Q1. The balance sheet also shifted. Revolver borrowings rose to $131.3 million from $81.3 million and corporate cash fell to $194.5 million as buybacks jumped to $152.5 million from $48.1 million in fiscal Q4.
The market setup is more demanding than the surprise implies. Shares closed at $170.96 heading into the report, up 14.0% from the open after the August release and about 35% above the 200-day moving average. The stock rallied from a late-September low of $139.42 to a 52-week high of $178.53 on October 26 and entered earnings just 4.2% below that peak. Investor sentiment improved substantially, from -0.41 to -0.10, but remains slightly negative. That suggests skepticism has eased rather than flipped to enthusiasm. Price trend, momentum and AVWAP readings are positive, while sequential growth is neutral, consistent with a business that is executing but not accelerating.
The bottom line is that Paylocity delivered a convincing quarter and a guidance raise that removes near-term downside worries. Much of the incremental upside, however, rests on rates, buybacks and still-unproven monetization of new AI and service products. With the stock near its highs, the next test is whether recurring growth holds near double digits and gross margin recovers as the Elevate staffing ramp matures.
Read our earnings preview for Paylocity Holding Corporation: https://www.earningswhispers.com/article/PCTY/22359
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-22 | |
| Oct-13 | |
| Oct-13 | |
| Oct-05 | |
| Sep-29 | |
| Sep-28 | |
| Sep-22 | |
| Sep-10 | |
| Aug-25 | |
| Aug-11 |
