Profound Medical Must Prove Its Slipped Shipment Was Timing, Not A Demand Problem
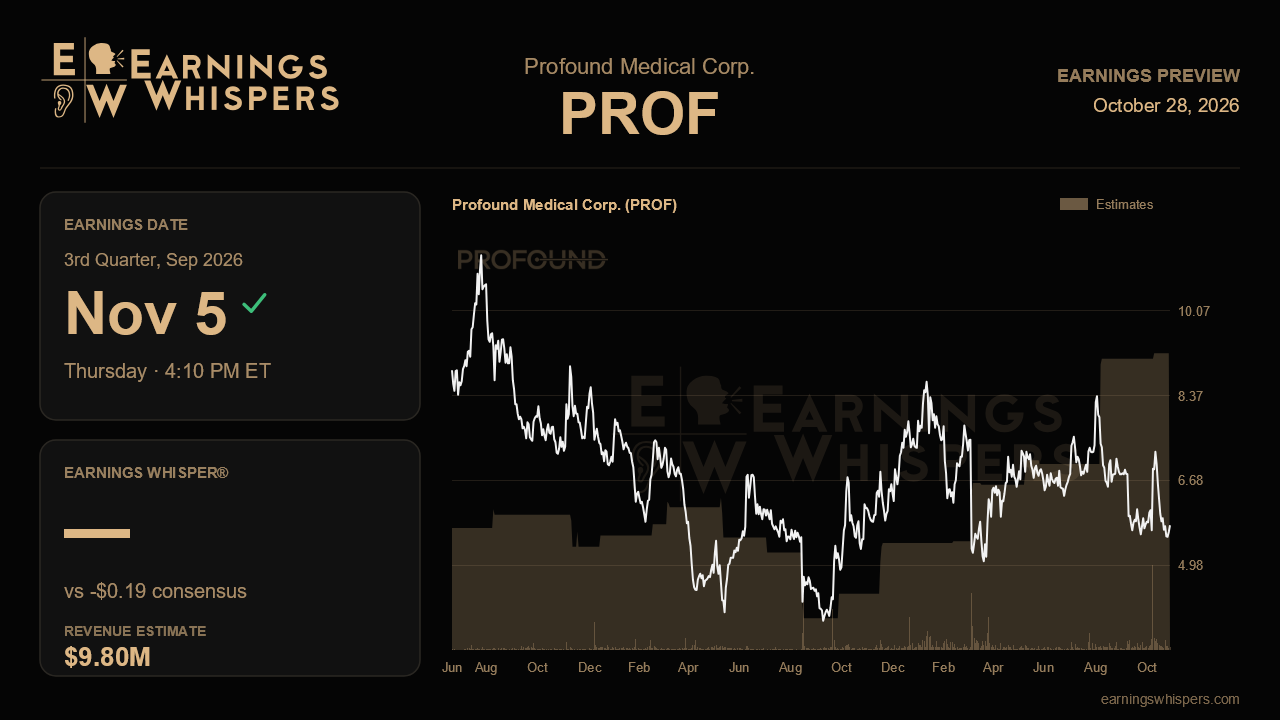
Profound Medical heads into its third-quarter report carrying a promise it now has to keep. Last quarter, management blamed a $3.1 million shipment that slipped into July for reported revenue of just $2.5 million, arguing the underlying number would have been roughly $5.6 million and that the business had reached another commercial inflection point. The market has not given the company the benefit of the doubt. The shares have fallen about 21% since that report while the S&P 500 was essentially flat. That leaves Thursday's release as a credibility test as much as an earnings event.
The Street expects revenue of about $9.8 million, up roughly 85% from $5.3 million a year ago, and a loss of 19 cents per share, an improvement from the 26-cent loss in both the year-ago period and last quarter. That revenue figure clearly assumes the delayed July shipment lands in this period on top of normal activity. Management reaffirmed its full-year target of approximately $25 million, and consensus sits at $25.1 million, essentially right on the guide. Notably, the company held that outlook rather than raising it despite its more upbeat tone, so the bar is not stretched. Still, there is little cushion if logistics problems recur. Execution, rather than ambition, is the issue here.
The operating story management laid out has real substance. Gross margin climbed to 78% last quarter, well above the company's 70%-plus target, and keeping it near that level while revenue scales would show the improvement is structural rather than a product of mix. The installed base reached 84 systems, up from 70 a year earlier. Payer coverage expanded by more than 18 million lives in a single quarter. The proposed 2027 Medicare hospital rate would raise TULSA payment nearly 15%, widening its premium over competing prostate procedures. Management also cited record July orders and more than 160 qualified leads from a key urology conference. Those claims should show up as new system placements and a reaffirmed or firmer pipeline, which was reframed at about $70 million.
The softer spots deserve equal attention. Same-store utilization at the company's index sites fell 12% sequentially. Management attributed the dip to temporary issues at five locations, including a pause while one customer converted a placement into a capital purchase. A rebound in procedure volumes would support the view that reimbursement gains are translating into patient demand, while another decline would raise doubts that the installed base is being used productively. Shipped-but-not-installed units have now been a theme for two straight quarters, so evidence that the new operations leadership has smoothed revenue recognition matters too. The proposed cut to the ambulatory surgery center rate is a longer-term overhang, though the company has no active sites in that setting.
Cash is the other swing factor. The balance fell to $38.3 million from $59.7 million at the end of last year, a burn of roughly $10 million to $12 million a quarter even after operating expenses dropped 16%. With the CFO absent from the last call, investors will want clarity on finance leadership and on how long the current runway lasts. A clear answer here could ease fears of near-term dilution.
Sentiment has soured noticeably, with bearish readings deepening from modest levels a quarter ago. At $5.65, the stock trades well below its 200-day average of $6.71 and just above its post-earnings low of $5.45, a range that sits entirely beneath last quarter's band. Expectations are therefore subdued. The decisive question is simple: does the July shipment arrive alongside a genuinely strong core quarter, keeping $25 million in reach, or does the recovery depend on yet another deferral? A clean quarter could reset the narrative, while more timing excuses would likely confirm the market's skepticism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-28 | |
| Oct-22 | |
| Oct-14 | |
| Oct-09 | |
| Oct-09 | |
| Oct-07 | |
| Sep-03 | |
| Sep-01 | |
| Aug-17 | |
| Aug-14 | |
| Aug-13 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 |
