StandardAero Must Prove Its Margin Inflection Holds As Stock Trades Near Post-Earnings Lows
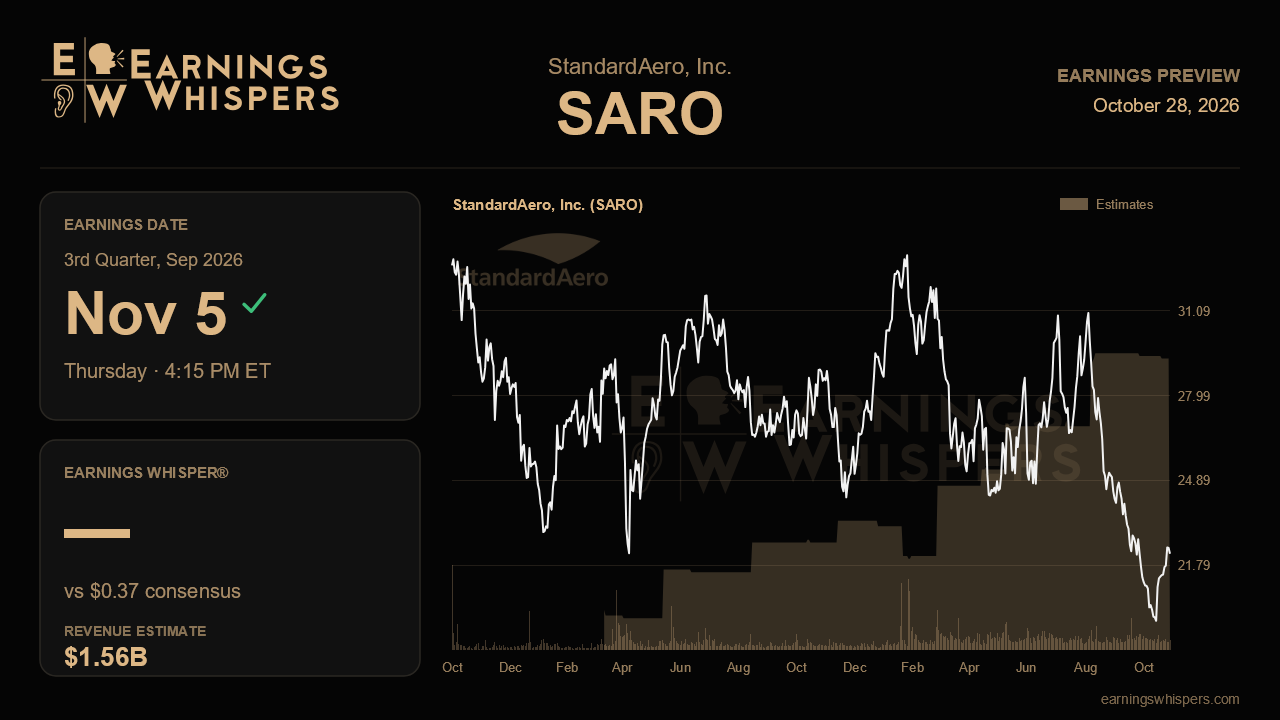
StandardAero heads into its third-quarter report with an unusual disconnect. Management has raised its full-year outlook three calls in a row, delivered record margins last quarter and declared both of its big growth programs profitable, yet the stock has fallen about 24.5% since that report while the S&P 500 barely moved. When the company reports after the close on November 5, the question is whether the operating story is still intact or whether the market has spotted cracks that the guidance has not yet acknowledged.
The Street is looking for earnings of $0.37 per share on revenue of $1.56 billion. That would be an 85% jump from the $0.20 earned a year ago, on revenue growth of only about 4%. The gap between those two figures is the margin story in a nutshell: the earnings leverage depends far more on profitability than on volume. Both estimates also sit below last quarter's $0.40 and $1.60 billion, so analysts are not modeling a straight-line climb. More telling, the full-year consensus of $1.42 per share sits below management's raised range of $1.50 to $1.57, even as the revenue consensus of $6.41 billion lands comfortably inside the $6.375 billion to $6.5 billion outlook. In other words, the Street broadly accepts the sales forecast but is skeptical about how much of it reaches the bottom line.
That skepticism points straight at the component repair business. Its margin slid to 26.3% last quarter, down 270 basis points from a year earlier and a sharp reversal from the record 29.2% posted the quarter before. Management blamed work migration between facilities, inefficiency as new employees ramp up and delayed military inputs. It described the problem as timing and held its segment outlook, which implies a return to the high-20s in the second half. This quarter is the first real test of that claim. A rebound toward 28% or better would support the idea that the dip was transitory. Another reading in the mid-20s would suggest a structural problem and could make the full-year EBITDA target of $885 million to $910 million look stretched.
Military and helicopter revenue is the second swing factor. After growing 10% in the first quarter, it fell 3% in the second on input delays, and management now explicitly needs a back-half surge to reach low-double-digit growth for the year. Back-loaded forecasts leave little room for slippage, so a quarter without visible improvement would likely draw pointed questions. On the positive side, the Winnipeg CF34 expansion was slated for completion this quarter and is said to be effectively sold out. Confirmation that it is up and running, along with evidence that LEAP and the CFM56 Dallas-Fort Worth center remain profitable rather than having just touched breakeven, would reinforce the multiyear growth case, including the newly expanded ambition for several billion dollars in annual LEAP revenue by the mid-2030s.
Sentiment has soured noticeably, with bearish readings more than doubling from the prior quarter. The shares trade at $22.42, well below the 200-day moving average of $26.78 and much closer to the post-earnings low of $19.56 than the $30.82 high. That positioning cuts both ways. Expectations are clearly muted, but a stock this weak tends to signal investors want proof rather than promises. Free cash flow guidance of $270 million to $300 million, held flat for four straight calls amid persistent shortages of forgings and castings, along with any commentary on jet fuel's effect on airline demand, will color that judgment.
Ultimately, this report hinges on whether component repair margins bounce back as promised while military work begins its anticipated catch-up. If both show up, the company's guidance looks credible and the Street's below-range estimates look too cautious. If they do not, the market's recent verdict may prove to have been early rather than wrong.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-06 | |
| Sep-23 | |
| Sep-03 | |
| Aug-18 | |
| Aug-06 | |
| Jul-23 | |
| Jul-21 | |
| Jul-20 | |
| Jul-20 | |
| Jul-16 | |
| Jun-17 | |
| Jun-02 |
