StandardAero Matches EPS Estimates, Raises Guidance A Fourth Time And Launches $350M Buyback, But Component Repair Margins Keep Slipping
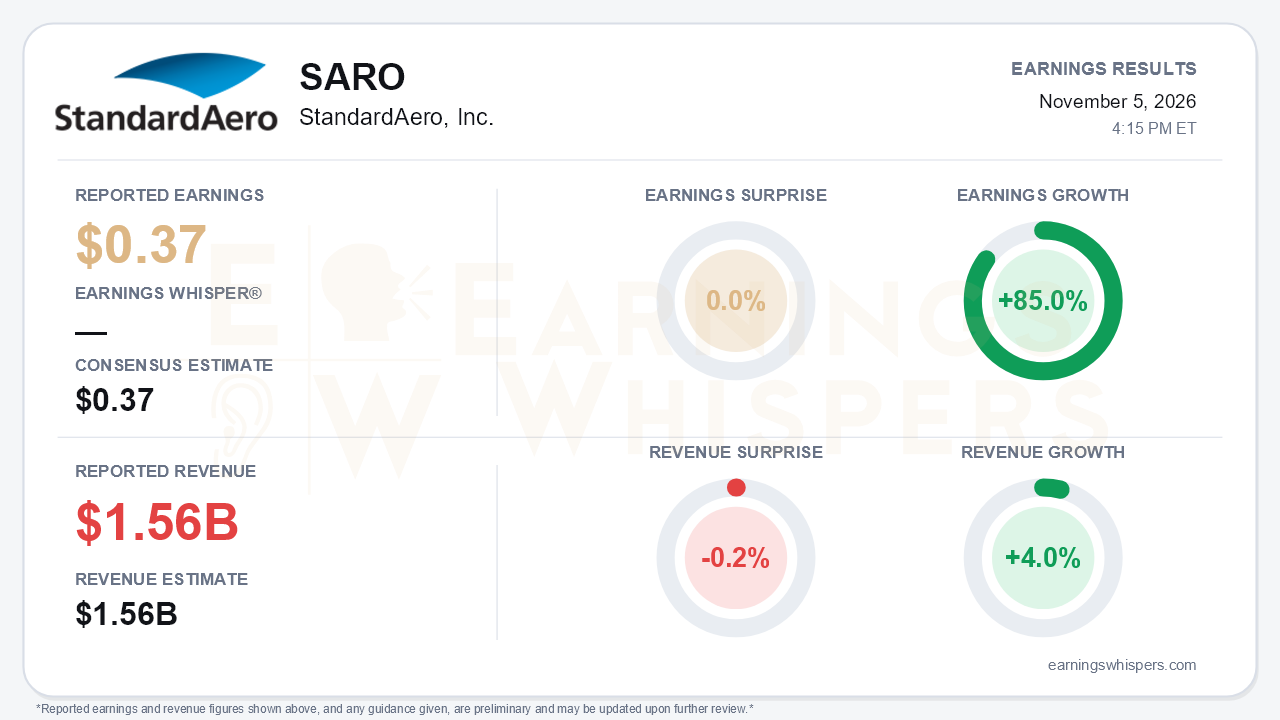
StandardAero's third quarter matched expectations on earnings and missed slightly on revenue. The company reported earnings of $0.37 per share on revenue of $1.557 billion. EPS was in line with the $0.37 consensus, and revenue came in 0.2% below the $1.56 billion estimate. On the Earnings Whispers normalized basis, earnings grew 85.0% year over year while revenue rose just 4.0%.
The company's own figures tell a somewhat different story. Management reported adjusted diluted EPS of $0.39, up 30% from $0.30. That definition was broadened in Q2 to exclude amortization of all intangible assets, including license-related intangibles. GAAP diluted EPS rose to $0.28 from $0.20. Investors should know which yardstick they are using.
The headline is not the beat. It is the guidance and the capital return. Management raised full-year guidance for the fourth consecutive quarter, and this was the largest increase yet:
- Revenue: $6.525-6.645 billion, up $148 million at the midpoint.
- Adjusted EBITDA: $905-920 million.
- Adjusted EPS: $1.57-1.62, up from $1.50-1.57 last quarter and $1.35-1.45 at the start of the year.
The board also lifted the buyback authorization to $1.0 billion and announced a $350 million accelerated share repurchase.
The quality of the quarter rests almost entirely on Engine Services. Segment adjusted EBITDA jumped 24% to $205.1 million. Margin expanded 250 basis points to 15.0%, up from 14.5% in Q2 and 12.3% in Q1. The drivers were volume, mix, productivity and a heavier contribution from used serviceable material. The LEAP and CFM56 lines in San Antonio and Dallas, profitable since Q2, are scaling. As a result, consolidated adjusted EBITDA margin reached 14.4%, up 130 basis points.
The 4% top-line growth understates underlying demand because roughly $300 million of pass-through material revenue is being eliminated. Commercial aerospace grew only 1.3% on a reported basis. Even so, management still assumes low-double-digit to mid-teens commercial growth for the year once pass-through is excluded.
That is where the central tension sits. Component Repair Services is moving the wrong way:
- Segment revenue rose 7.3%, but adjusted EBITDA fell 9.9%.
- Segment margin was 25.8%, down from 30.7% a year ago, 26.3% in Q2 and 29.2% in Q1.
- That is well below the 28.5-29.5% range management initially guided.
In Q2, management expected a second-half recovery into the high 20s. Instead, military training-platform inputs fell sharply as Middle East conflict spending pulled outlays elsewhere, and management now ties the recovery to the conflict itself. Internal insourcing sales grew just 1% after the loss of a discrete contract.
The Engine Services strength is not fully repeatable either. The used-material benefit was non-recurring, and the guidance implies Q4 segment margin of about 14%, down from 15%. Bears have legitimate ammunition here: the best segment's peak margin is fading while the highest-margin segment keeps compressing.
Cash flow deserves similar scrutiny. Operating cash flow was $128.9 million and adjusted free cash flow was $99.2 million, up from roughly $50 million in Q2. However, GAAP free cash flow was negative $81 million after $180 million of intangible purchases tied to license investments. The company now guides to adjusted free cash flow, which excludes those payments. Meanwhile:
- Revolver borrowings rose to $270 million from $110 million a year earlier.
- Cash fell to $191 million.
- Net leverage improved to 2.7x, but mainly because trailing EBITDA grew rather than because debt came down.
Committing $350 million to an accelerated buyback in that context is a confident bet on future cash generation, not a distribution of excess cash.
The forward catalysts are real:
- Customer demand visibility now extends into 2028.
- LEAP shop-visit slots are being quoted into the mid-2030s.
- The $1 billion LEAP revenue target for 2030 was reaffirmed.
- License-expansion EBITDA is now expected at about $30 million next year.
- The Winnipeg CF34 expansion is complete.
- New CEO Paul McElhinney, formerly head of GE Aerospace's aftermarket business, framed LEAP, productivity, CRS and capital deployment as his priorities, in a confident tone.
Analysts did press on whether higher fuel prices and airline capacity cuts could slow engine maintenance demand. Management said it sees no impact.
The market had been skeptical heading into the print. Shares closed at $25.71 the day before the report:
- That was 13.4% below the opening price after the August release.
- It was about 3% below the 200-day moving average.
- Shares had set a 52-week low of $19.56 on October 14.
- Although they had rebounded 31% from that low, they remained nearly 17% below the August 7 high of $30.82.
Investor sentiment deteriorated meaningfully over the quarter, falling from -0.20 to -0.46. The stock therefore entered earnings with expectations already depressed, a setup that a guidance raise and an accelerated buyback could exploit.
The bottom line is that StandardAero delivered an in-line quarter wrapped in a genuinely stronger outlook. Engine Services profitability, rising guidance and multi-year demand visibility support a credible growth story. However, the slide in Component Repair margins, the non-recurring used-material tailwind, and a cash-flow picture flattered by excluding license purchases mean the quality of the raise deserves scrutiny. With sentiment negative and shares still below their 200-day average, the next test is whether Q4 holds near 14% in Engine Services and whether CRS can stabilize without waiting on geopolitics.
Read our earnings preview for StandardAero, Inc.: https://www.earningswhispers.com/article/SARO/22376
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-02 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Oct-06 | |
| Sep-23 | |
| Sep-03 | |
| Aug-18 | |
| Aug-06 | |
| Jul-23 | |
| Jul-21 | |
| Jul-20 | |
| Jul-20 |
