Runway Growth Must Show Its Core Earnings Still Cover The $0.33 Dividend Without One-Time Help
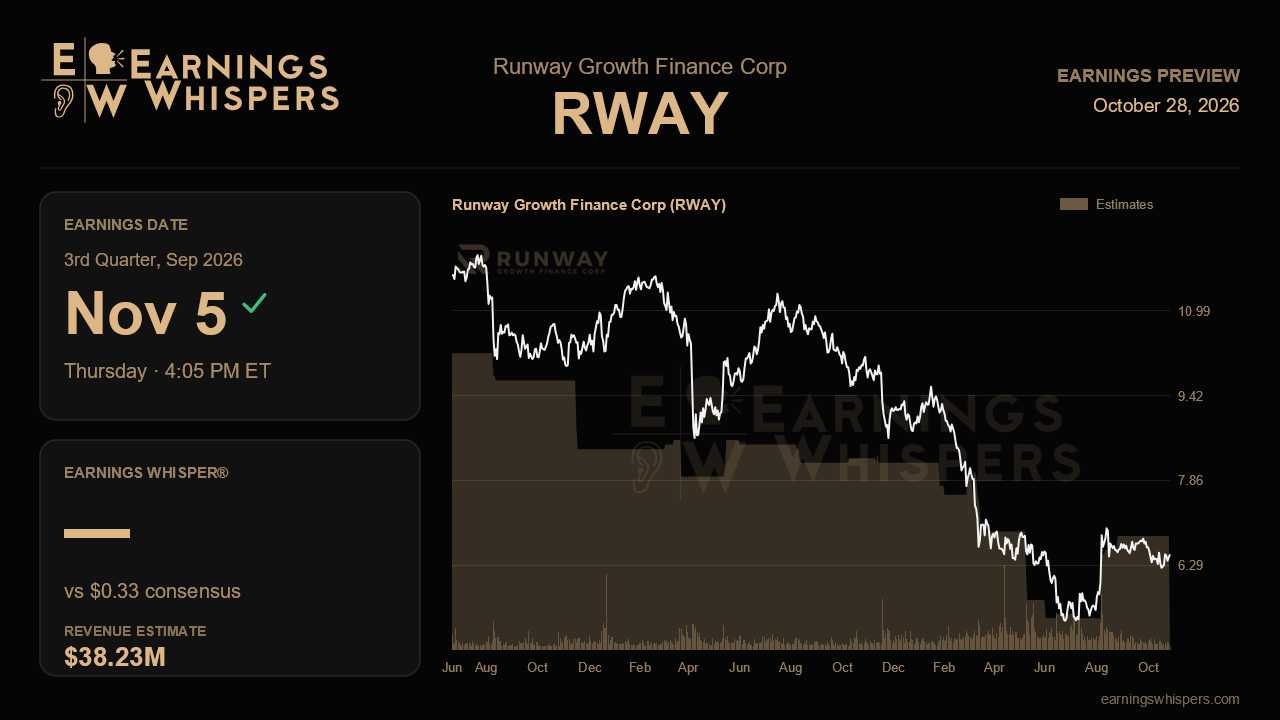
Runway Growth Finance heads into its third-quarter report with a deceptively simple question hanging over it: what does this BDC actually earn once the accounting tailwinds fade? Last quarter's net investment income of $0.43 per share looked like a clean step-up from the SWK Holdings acquisition, but roughly $0.09 of that came from deferred incentive-fee reversals and prepayment activity. Strip those out and the run rate sits in the mid-$0.30s, uncomfortably close to the $0.33 quarterly dividend. Consensus has landed exactly there, at $0.33 per share, which makes this report less about beating a number and more about proving the payout is genuinely earned.
The Street's math implies a 23% year-over-year decline in per-share earnings even as revenue is expected to edge up about 4% to $38.2 million, compared with $37.0 million last quarter. That divergence tells the story. The top line now reflects a portfolio that swelled to $1.2 billion with SWK, yet per-share profitability is expected to normalize lower because last quarter's extras will not repeat and higher leverage brings higher interest costs. Management reaffirmed, but did not raise, its view that the dividend will be more than fully covered for the year. A print at or modestly above $0.33 would validate that stance; anything meaningfully short would raise doubts about coverage just as the board weighs future distributions.
Credit is the second test. The Marley Spoon and BlueShift restructurings crystallized into a $45.3 million realized loss last quarter, and the Marley Spoon workout is still unresolved. Debt yield held at 14.2%, down from 15.4% a year earlier because of those problem loans. Investors should look for stability in non-accruals, any recovery on Marley Spoon, and whether the weighted average risk rating holds near the improved 2.34 level. Fresh additions to the non-accrual list would undercut management's argument that the worst is behind the portfolio, particularly with lingering market unease toward software-heavy lenders.
Then there is net asset value, which has slid from $13.55 to $11.91 over three quarters. Last quarter's $0.22 per share hit came largely from SWK transaction expenses, a one-time cost that should not recur. That makes this quarter a cleaner read: a flat or rising NAV would suggest the erosion was transaction- and loss-driven rather than structural, while another decline would reinforce the market's skepticism. Balance sheet flexibility matters here too. Leverage jumped to 1.36x, above the 1.2x to 1.3x target, and liquidity fell to $210.8 million. Watch whether management pulls leverage back toward target or stretches further to fund originations and the $11.9 million left on its buyback.
The buyback angle is unusually relevant. At $6.43, the stock trades near 54% of last reported NAV, well below the 70% threshold that triggers BC Partners affiliates' commitment to buy up to 10% of shares over two years. Evidence of that buying, alongside company repurchases under the new 10b5-1 plan, would offer real technical support. The shares have slipped 1.1% since the last report, slightly lagging the S&P 500, and sit below the 200-day average of $6.84, nearer the $6.21 low of their post-earnings range than the $6.99 high. Sentiment has softened from 51.8% bearish to 44.9% bearish, so the crowd is less gloomy, though hardly enthusiastic.
Ultimately, the report hinges on whether SWK-fueled scale translates into recurring income that covers the dividend on its own, while NAV finally stops bleeding. Deliver both, with a new leadership team under Co-CEO Mike Rovner and CFO Carmela Thompson showing steadier credit, and the deep discount starts to look excessive. Miss on either, and the market's discount will look like a forecast rather than an overreaction.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-27 | |
| Oct-13 | |
| Oct-06 | |
| Sep-25 | |
| Sep-23 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-17 | |
| Jul-14 | |
| Jul-14 | |
| Jul-08 | |
| May-28 | |
| May-26 |
