Runway Growth Beats On NII, But Stalled Originations And Sub-Dividend Core Earnings Shift The Story
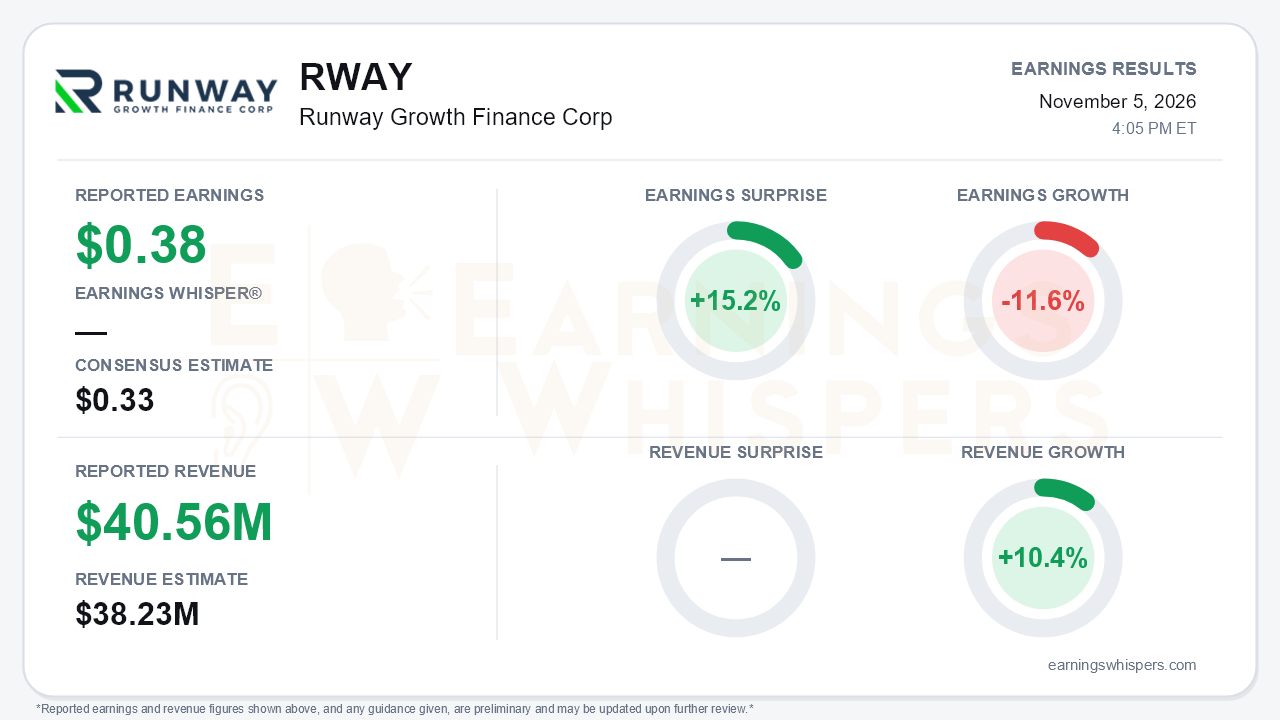
Runway Growth Finance (NASDAQ: RWAY) reported third-quarter net investment income of $0.38 per share, beating the $0.33 consensus by 15.2%. Total investment income of $40.56 million topped the $38.23 million estimate by 6.1% and grew 10.4% from a year ago. The beat deserves scrutiny. Per-share NII still fell 11.6% year over year and slipped from $0.43 in the second quarter. Management also pointed to roughly $0.06 per share of net one-time benefit in the quarter, which puts core NII at about $0.32. That is a penny below the $0.33 dividend the board just declared. The central tension is clear: the balance sheet and credit profile improved sharply, but the earnings engine is shrinking.
The release shows why the headline flatters the run rate. Interest income rose to $37.3 million from $30.7 million a year earlier, largely because the SWK assets enlarged the book. That growth came with a higher cost base. Operating expenses climbed to $24.7 million from $21.0 million a year ago and from $18.8 million in the second quarter. Interest expense alone rose to $13.3 million from $10.6 million. Weighted average shares grew to 41.9 million from 36.2 million, so dollar NII of $15.9 million was essentially flat year over year while per-share NII declined. The reported 15.8% debt yield, up from 14.2%, was boosted by prepayment activity; management put core yield at 14.0%. On a GAAP basis, the net increase in net assets was $0.26 per share as $5.2 million of unrealized losses offset a sliver of realized gains. For the nine months, total investment income of $107.0 million was virtually unchanged from a year ago.
The operating picture from the call is one of deliberate retrenchment. Fundings fell to just $8.5 million, all follow-ons to existing borrowers, from $85.8 million in the second quarter. Meanwhile, repayments totaled $140 million. The biggest was the $72.3 million payoff of 3PL/Extensive after its acquisition by Descartes, which removed the largest single-name concentration. As a result, leverage dropped to 1.10x from 1.36x and returned to the target range. Asset coverage improved to 1.91x, and the weighted average risk rating fell to 2.26, its best level since 2023. NAV per share ticked up to $11.94 from $11.91, a modest stabilization after the slide from $13.42 at year-end 2025. The cost is that the portfolio fell to roughly $1.06 billion from $1.19 billion.
The forward-looking signals tilt more cautious than the beat implies. Management said fourth-quarter repayments are on pace to match or exceed the third quarter's. Post-quarter activity already includes $55 million of prepayments, among them a MedMinder payoff at a 36.7% IRR, against only $4 million of new commitments. Net portfolio growth may be "a while" away. Dividend language also weakened. Last quarter, management described a stable outlook with more than 100% coverage and an aim to grow the payout. This quarter, it committed to coverage only through fiscal 2026 and called 2027 hard to predict. Spillover income of $0.76 per share provides a cushion, but bears have legitimate ammunition. Marley Spoon took another $10.8 million write-down and needs growing bridge financing amid restructuring. Management also warned that higher rates could dampen venture deal flow and flagged looser underwriting in parts of the market.
There are offsets. The buyback authorization doubled to $30 million, with $22.1 million remaining, and the company repurchased $4.8 million of stock in the quarter. The board is also discussing a possible tender offer. A 7.75% baby bond refinanced $33 million of 9% SWK notes, lowering funding costs. With more than half of borrowings fixed-rate, management expects the Fed hike to lift fourth-quarter portfolio yields. Thin trading liquidity, however, limits how much the buyback can move the stock.
Investor sentiment remained negative but improved modestly, rising from -0.52 to -0.45 since the prior report. The stock has gone essentially nowhere. At $6.56, shares are up 0.9% from the $6.50 open after the August report. They sit 2.7% below the 200-day moving average and roughly midway between the inter-earnings high of $6.99 in mid-August and the $6.21 low on October 19. That leaves the stock trading near 55% of NAV. The Earnings Whispers trend readings are largely neutral, with AVWAP still negative, consistent with a market waiting for evidence rather than reacting to the beat.
The bottom line is that Runway Growth used the quarter to de-risk. It cut leverage, reduced concentration, improved credit ratings, refinanced expensive debt and expanded buybacks. The 15.2% NII beat, however, rests partly on one-time items, and core earnings now trail the dividend. With originations nearly frozen and repayments still running ahead, the investment case has shifted from income growth to balance-sheet discipline and capital return. Dividend durability into 2027 is now the key open question.
Read our earnings preview for Runway Growth Finance Corp: https://www.earningswhispers.com/article/RWAY/22375
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-27 | |
| Oct-13 | |
| Oct-06 | |
| Sep-25 | |
| Sep-23 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-17 | |
| Jul-14 | |
| Jul-14 |
