Quest Resource Must Prove Its Industrial Rebound Has Legs As Shares Lag The Recovery
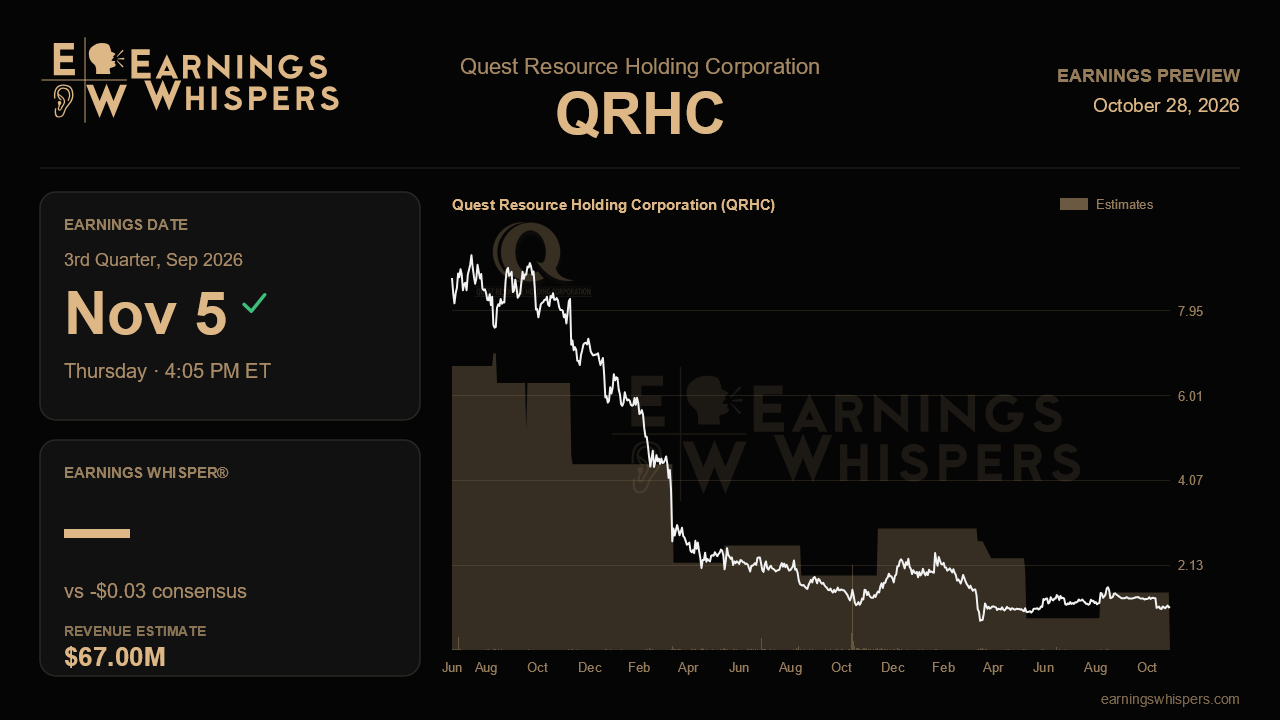
Quest Resource Holding enters its third-quarter report with an awkward disconnect. Last quarter, management delivered its first year-over-year revenue growth in a while, sharper cash generation and its most confident tone in several calls. The stock has since fallen about 14.6%, trailing a roughly flat S&P 500 by more than 14 percentage points. The report due after the close on November 5 has to show that the turn described last quarter is a trend rather than a single good quarter.
The Street is looking for revenue of about $67.0 million, up 5.8% from $63.3 million a year ago and roughly 4.5% above the $64.1 million posted in the second quarter. That fits management's outlook, which called for another quarter of sequential revenue growth and gross margins flat to slightly higher than the 16.3% just reported. Consensus sits squarely inside that framework rather than stretching beyond it. On the bottom line, analysts expect a loss of $0.03 per share. That would be narrower than the prior quarter's $0.05 loss but wider than the $0.02 loss a year earlier, so the per-share comparison looks worse than the operating story. For a company priced near a dollar, a penny swing either way says more about interest expense and rounding than about the health of the business.
The industrial portfolio is the hinge. It went from a $4 million year-over-year drag in the first quarter to a $3.3 million contribution in the second, and management described it as stabilized for the first time after several quarters of decline. A second straight quarter of industrial growth would support that claim. A reversal would suggest the second quarter was a restocking blip. Management also conceded that some industrial accounts now run structurally below where they were a few years ago, so the real test is whether the largest customers keep growing off a lower base, not whether volumes return to old peaks.
Margins are the second test. Gross margin recovered sequentially but was still more than two points below the 18.5% of a year earlier, a gap the company tied to pricing pressure at select industrial clients. If revenue reaches the consensus figure and margins hold the guided range, gross profit would land somewhere around $11 million. That would extend the sequential climb from $9.7 million and $10.4 million over the past two quarters. The new seven-figure win with a national auto parts retailer was described as coming in at normal, accretive margins. It is the clearest early check on whether recent customer additions are improving the mix rather than buying revenue cheaply. Commentary on the other wallet-share wins, nine since the back half of fiscal 2025, and on whether long sales cycles are shortening will show how durable growth into next year might be.
Cash and balance-sheet discipline round out the scorecard. Operating cash flow jumped to $4.5 million from roughly $0.2 million, days sales outstanding fell to about 70 against a mid-60s target, and another $2 million of voluntary term debt was repaid, leaving net notes payable near $59.4 million. With SG&A already down about 20% in the first half, further gains in operating leverage depend mostly on gross profit growth rather than more cost cuts. Rising diesel costs, which management flagged as a watch item, could pressure that.
Sentiment has softened its bearish edge, improving to a modestly negative reading from a more pessimistic one ahead of the last report. The shares at $1.17 still trade well below the 200-day moving average of $1.40 and in the lower part of their post-earnings range of $1.03 to $1.66. The bar is not demanding. What decides whether the recovery narrative survives is simple: industrial volumes must keep growing while gross margin holds or improves, turning top-line momentum into gross profit dollars that can fund continued deleveraging.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| May-07 | |
| May-07 | |
| Apr-23 | |
| Mar-12 | |
| Mar-12 | |
| Mar-12 | |
| Mar-10 | |
| Mar-10 | |
| Feb-26 |
