Quest Resource Beats On The Bottom Line As Margins Rebound, But A 4.8% Revenue Miss And Stalled Industrial Volumes Keep The Turnaround Unproven
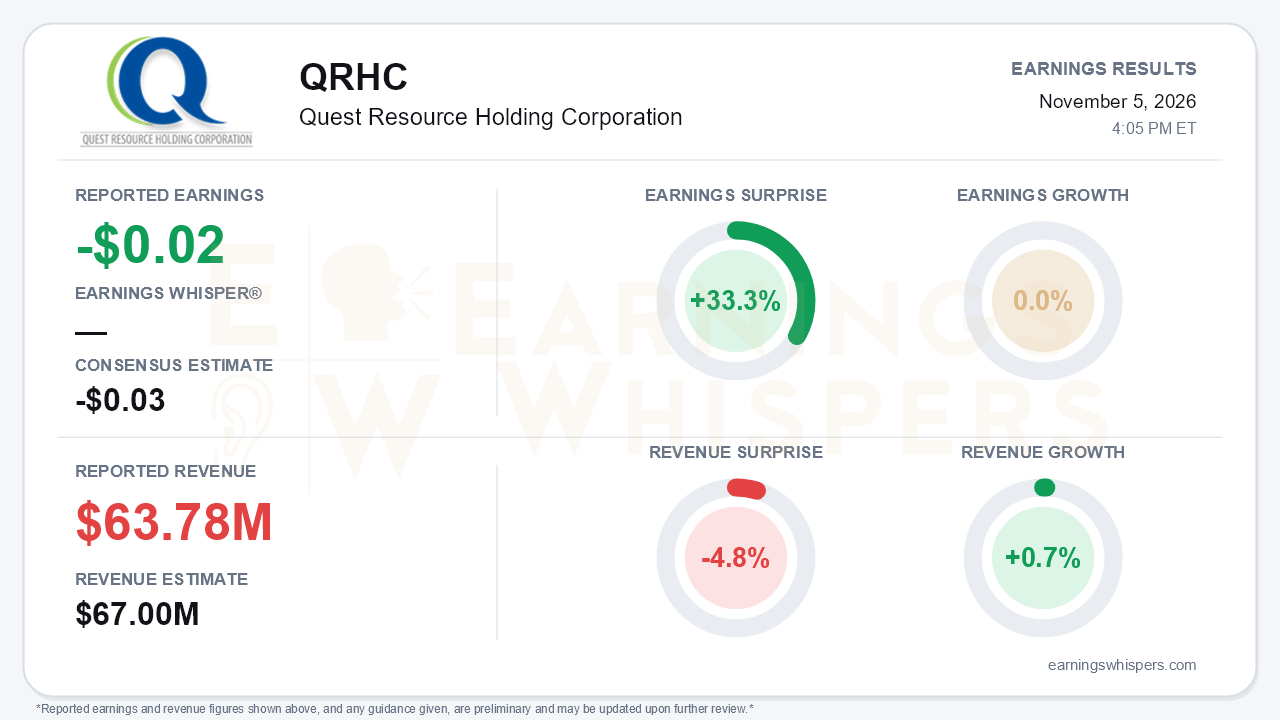
Quest Resource Holding Corporation (NASDAQ: QRHC) produced the kind of quarter that looks better the further down the income statement you read. The company posted a loss of $0.02 per share, beating the -$0.03 consensus by 33.3%. Revenue was $63.78 million, however, missing the $67.0 million consensus by 4.8% and rising only 0.7% from a year ago. Earnings Whispers' normalized comparison shows earnings growth of 0.0% year over year, even though GAAP loss per share narrowed to $(0.02) from $(0.06). Investors should note that difference: the GAAP improvement is real, but on a normalized basis the bottom line is treading water. The central tension is clear. Quest delivered a convincing margin and EBITDA step-up while the top line stalled again, and the turnaround still depends on revenue wins that have not yet been announced.
The quality of the improvement holds up better than the revenue line. Gross margin rose 150 basis points sequentially to 17.8%, up from 16.3% in Q2 and 15.7% in Q1. That beat management's Q2-call guide of "flat to slightly up." Gross profit rose 9.1% sequentially to $11.4 million. Adjusted EBITDA reached $3.4 million, versus $2.8 million in Q2 and $2.9 million a year ago. Cost discipline did much of the work. SG&A fell to $8.5 million from $9.2 million, and year-to-date SG&A is down roughly $5 million, or 16%. Operating income rose to $1.7 million from $1.1 million. Still, gross margin remains below last year's 18.1%, and gross profit edged down 0.7% year over year. Much of the sequential rebound is recovery from a weak first half rather than new peak profitability.
The revenue story weakened compared with the prior quarter. Q2 showed 8% year-over-year growth and 4% sequential growth, and management had expected another sequential increase in Q3. Instead, revenue slipped to $63.8 million from $64.1 million. Industrial volumes had stabilized in Q2 but softened again, creating a $1.2 million year-over-year drag that net new business of $1.7 million only partly offset. Non-industrial revenue grew sequentially, which supports the diversification thesis. But Quest closed no material wallet-share wins in Q3, compared with four in Q2. Management described gross margin as sustainable within a range, attributing it to service-network optimization, pricing and maturing land-and-expand accounts. Revenue momentum, by contrast, now depends on deals that are still pending.
Those pending deals are the main catalyst. Management said several large national non-industrial brands are "on the goal line" and expressed hope to announce wins next quarter. That is a noticeable shift from Q2's "elongated sales cycle" language. Other positives include:
- four contract renewals signed without concessions;
- the hiring of a new SVP of Technology;
- guidance for Q4 gross profit and margin to rise solidly year over year.
Management also signaled a pivot from cost-cutting to reinvestment in sales and technology, and expects SG&A to tick up in 2027. That pivot carries a timing risk. Spending would rise before the revenue it is meant to capture has shown up, and Q4 seasonality points to a sequential decline.
The balance sheet gives bears legitimate ammunition. Operating cash flow turned negative at -$0.3 million, compared with +$4.5 million in Q2. Management blamed three client-specific collection delays and said they are now resolved. DSO stalled at about 71 days, short of the mid-60s target. ABL availability fell to $17.4 million from $19.4 million. Cash stood at just $943,000 against roughly $60.6 million in notes payable. Stockholders' equity has fallen to $26.6 million from $40.5 million at year-end, largely because of Q2's $11.0 million goodwill impairment. Diesel costs, which management said remain elevated, add another variable.
The market had already priced in considerable skepticism. Shares closed at $1.06 the day before the report. That is 23.0% below the $1.37 opening price after the August report and 23.2% below the 200-day moving average. The stock sat just 9.4% above its inter-earnings low of $0.96, set November 3, and 36.4% below the $1.66 high reached shortly after the last report. Investor sentiment remained negative but improved marginally, from -0.159 to -0.145, which amounts to essentially unchanged expectations. Earnings Whispers trend signals are mostly negative, with price, sequential growth and AVWAP all pointing lower; only momentum reads positive.
The bottom line is that Quest showed its cost structure and service network can generate meaningfully better margins and EBITDA. The beat on earnings was earned through operations, not accounting. But the revenue miss, the reversal in industrial volumes, negative cash flow and thin liquidity mean the investment case still rests on converting late-stage national-brand opportunities into announced wins. Until revenue growth resumes and collections normalize, the margin progress looks like a necessary foundation rather than proof of a durable turnaround.
Read our earnings preview for Quest Resource Holding Corporation: https://www.earningswhispers.com/article/QRHC/22367
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 6 hours | |
| 7 hours | |
| Oct-28 | |
| Oct-22 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-23 | |
| May-07 | |
| May-07 | |
| Apr-23 | |
| Mar-12 | |
| Mar-12 | |
| Mar-12 |
