Serve Robotics Must Prove DoorDash And Beacon Can Fill The Uber Hole
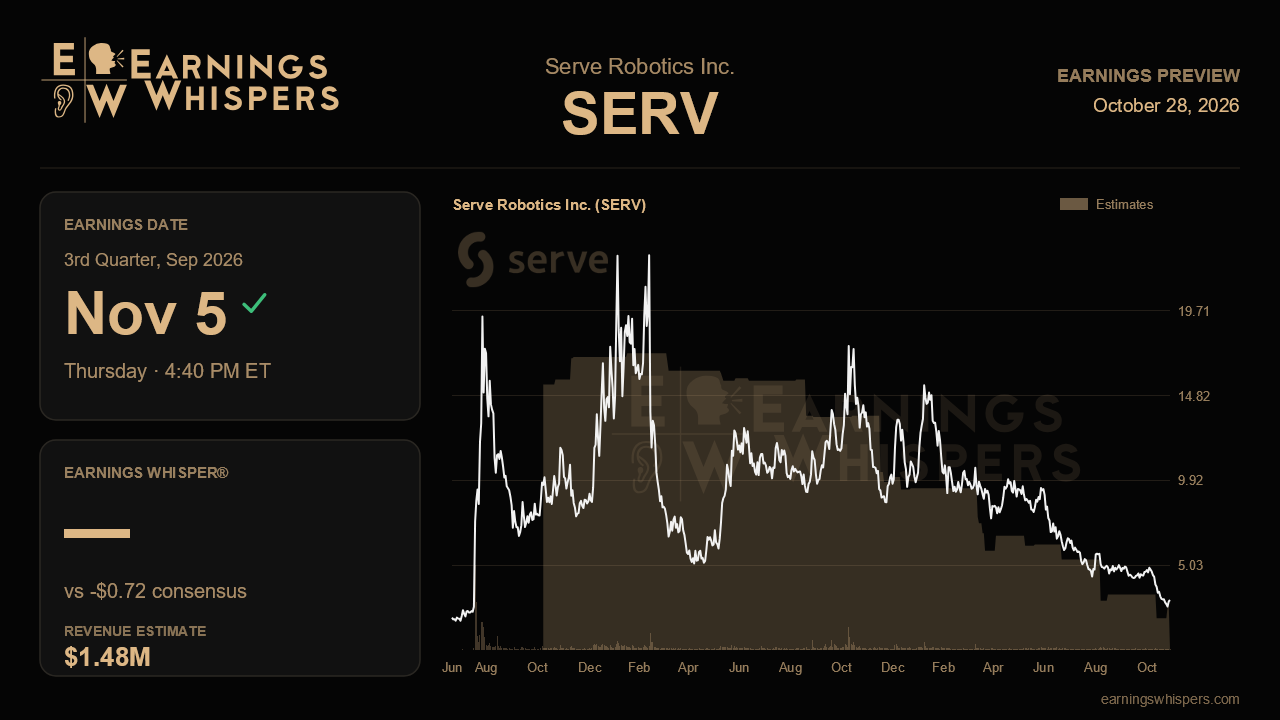
Three months ago, Serve Robotics stopped selling a growth story and started selling a survival plan. Management cut full-year revenue guidance by roughly 62%, from about $26 million to a range of $9 million to $10 million. It also signaled that its anchor Uber partnership will probably not be renewed when it expires in early 2027. The third-quarter report, due after the close on November 5, is the first real test of whether the replacement engine can turn over: DoorDash, advertising, hospital robotics and a slate of new products.
The Street is braced for a step down. Consensus calls for revenue of about $1.5 million, less than half the $3.2 million reported in the second quarter. That would still be more than double the $0.7 million from a year ago, but the sequential drop matters more. The forecast lines up with the reset guidance. After roughly $6.2 million in first-half revenue, the $9 million to $10 million range implies about $2.8 million to $3.8 million for the back half, or roughly $1.4 million to $1.9 million per quarter. A $1.5 million estimate sits toward the lower end of that implied path. The full-year consensus figure of around $25 million plainly predates the cut and should be disregarded. On earnings, analysts expect a loss of $0.72 per share. That is narrower than last quarter's $0.80 loss but wider than the $0.54 loss a year ago.
The operating questions follow directly from last quarter's call. First is how quickly Uber volume is fading. Volume on that platform fell for the first time after 17 straight quarters of growth, and management blamed a mismatch in operating model and integration. A steep further slide would raise doubts about whether the full-year floor holds. Second is whether DoorDash can carry more weight. Volume there grew about 50% sequentially in the second quarter and another 50% from June to July, and investors will want evidence that the momentum survived the summer. Third is whether advertising, which made up about half of robotic food delivery revenue, has held up despite pressure on ad budgets. Management has already warned that software revenue will be softer in the second half, so that line offers little cushion.
The newer catalysts also need to show up in the numbers. The Beacon countertop device launched in mid-August and is meant to reach merchants without back-of-house integration, a barrier management said blocks about two-thirds of orders. Early merchant adoption data would help validate it. So would details on the promised new marketplace partner, traction in the two new markets, the next-generation autonomy stack and the fall product aimed at non-food deliveries. On costs, last quarter's encouraging sign was a sequential improvement in fleet gross margin even as Uber volume fell. The bar is gross losses continuing to narrow from roughly -271% of revenue, with spending tracking toward non-GAAP opex of $140 million to $150 million and capex of $15 million to $17 million. Recurring revenue from the Diligent hospital business, which made up more than half of total revenue, is the steadiest piece and should keep showing contract renewals. Liquidity above $240 million gives Serve time, but not unlimited time.
The market has already passed judgment. Shares have fallen about 40% since the last report while the S&P 500 was flat. At $2.94, the stock sits near the bottom of its post-earnings range of $2.63 to $5.31 and well below its 200-day moving average of $7.48. Sentiment has turned far less negative, with the bearish reading easing from 46.6% to just 5.7%. That suggests much of the pessimism may already be priced in, though it says nothing about the result itself.
With expectations reset this low, a modest revenue figure alone is unlikely to move the stock much. What matters is whether non-Uber volume, Beacon adoption and narrowing gross losses show the business can grow without its founding partner. If the new channels prove real, the reset starts to look like a foundation. If not, the guidance cut may turn out to be the first of several.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-13 | |
| Oct-05 | |
| Aug-28 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-06 |
