Serve Robotics Beats And Lifts Its Outlook, But A Sequential Revenue Dip And Heavy Cash Burn Keep The Turnaround Unproven
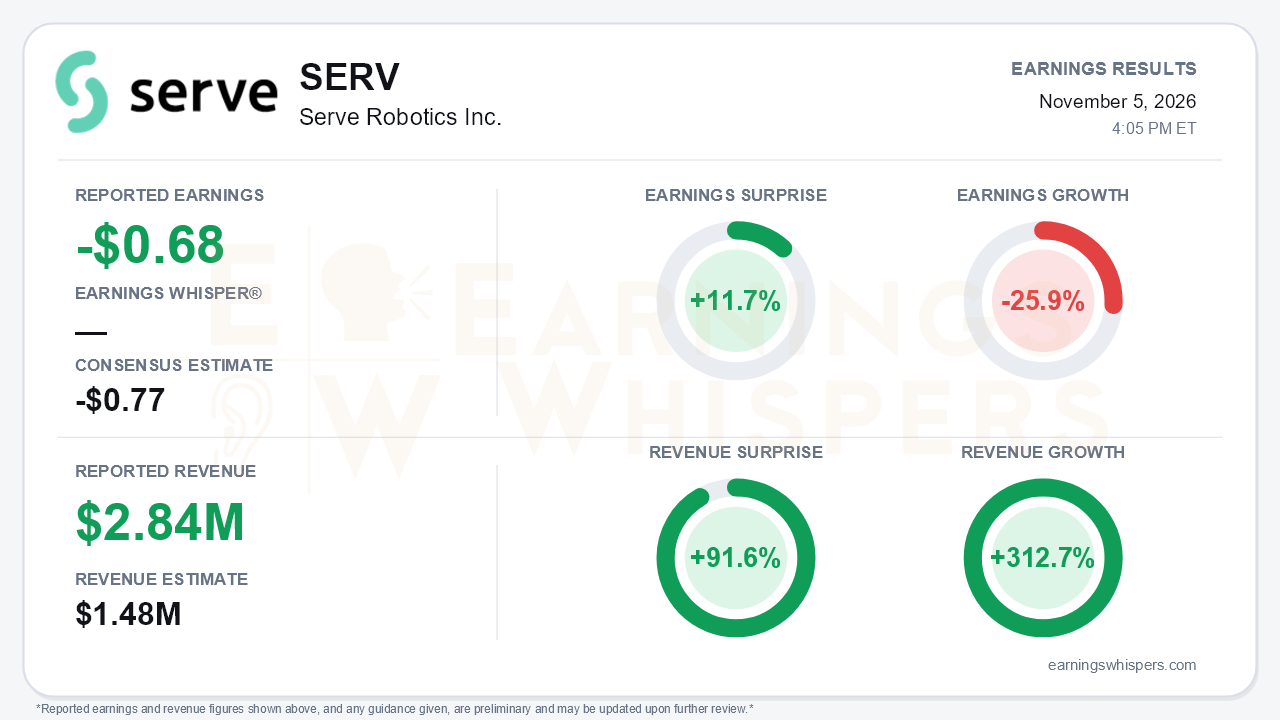
Serve Robotics (NASDAQ: SERV) delivered the kind of quarter a badly beaten-down stock needed on the surface. It lost $0.68 per share against a consensus loss of $0.77, an 11.7% earnings surprise. Revenue of $2.84 million nearly doubled the $1.48 million consensus, a 91.6% beat, and grew 312.7% year over year. Management also raised full-year 2026 revenue guidance to about $12 million from $9 million to $10 million. The central tension is that the beat came against expectations that had already collapsed. Revenue actually fell sequentially from $3.24 million in Q2, and the per-share loss still widened 25.9% from a year ago. This was a quarter of improving efficiency, not yet a quarter of improving scale.
The quality of the top line deserves scrutiny. Fleet services, the core business, grew to $2.58 million from $2.31 million in Q2, and daily active robots rose to 917 from 792. Software services, however, dropped to $253,000 from $933,000 after a customer contract completed in Q2, and management warned of continued quarter-to-quarter volatility there. Branding revenue rose roughly 80% sequentially, but part of that came from a six-week campaign that will not repeat. Even the raised guidance needs context. It implies roughly $3 million in Q4, which is still less than half the $26 million target management set early in the year and reaffirmed in Q1.
The cost story is where the quarter genuinely improved. Fleet margin rose by more than 100 percentage points sequentially, helped by about $1 million in procurement and maintenance savings and a 75% cut in external deployment costs. Overall gross margin edged up to -266% from -271%, a third straight quarter of improvement. Still, cost of revenues of $10.4 million against $2.8 million of revenue shows how far the unit economics have to travel. Non-GAAP operating expenses fell for the first time this year, to $39.2 million from $40.4 million, and the GAAP net loss narrowed to $59.2 million from $64.1 million in Q2. Research and development was the one line still rising. The release frames full-year non-GAAP opex of $150 million as a $10 million to $20 million cut from the start-of-year $160 million to $170 million guide. Against the $140 million to $150 million range given on the Q2 call, however, $150 million sits at the top end. That is not a fresh reduction.
Management's tone shifted from defensive in Q2, when it disclosed the Uber non-renewal and cut guidance, to confident. The demand evidence supports at least part of that shift. DoorDash and Grubhub daily deliveries more than tripled during the quarter, merchants on the new platforms grew 2.5x, and recurring revenue rose to 69% of the total from just over 50% in Q2. Hospital contract extensions reached 12, and the hospital count reached 27. New catalysts include:
- the Physical AI Services launch, with Bedrock Robotics as a named customer and a pipeline that spans mining and defense;
- an exclusive DoorDash launch in Gold Coast, Australia;
- a micro-depot format that management expects to cut city-launch costs to roughly one-fifth;
- a teased major autonomy announcement "in coming weeks."
On the other side, Uber volume continues to fall ahead of a contract expiration in Q1 2027, so the new channels must keep growing just to backfill that loss.
The balance sheet is the bears' strongest ammunition. Cash and marketable securities fell to $198 million from roughly $240 million in Q2 and about $260 million at the end of 2025. Nine-month operating cash burn reached $123.5 million. Serve raised $84.9 million through at-the-market offerings this year, and shares outstanding climbed to about 88 million from 74.7 million at year-end. Weighted shares rose more than 40% year over year, which explains why the per-share loss widened faster than the operational improvement would suggest.
The market had priced in a great deal of disappointment. Shares entered the report at $2.65, down 46.2% since opening at $4.93 after the August release and 62.5% below the 200-day moving average of $7.06. The stock had set a 52-week low of $2.43 on November 2 and traded about 9% above it, near the bottom of its inter-earnings range. Investor sentiment nonetheless improved meaningfully, from -0.47 after the prior report to roughly -0.05, close to neutral. The Earnings Whispers trend signals remain mostly negative on price, momentum, and AVWAP, consistent with a stock that has not yet stabilized.
The bottom line is that Serve delivered a cleaner quarter than skeptics expected, with a revenue beat, a guidance raise, real margin and expense progress, and a broader set of revenue channels. But revenue declined sequentially, the raised outlook rebuilds only part of the original plan, and cash burn and dilution remain heavy. The report improves the narrative more than it changes the math, and continued Q4 execution and the promised autonomy news will matter more than this beat.
Read our earnings preview for Serve Robotics Inc.: https://www.earningswhispers.com/article/SERV/22377
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 7 hours | |
| 7 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-13 | |
| Oct-05 | |
| Aug-28 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-11 |
