Surf Air Faces Back-Half Revenue Test As SurfOS Story Meets A Sub-$1 Stock
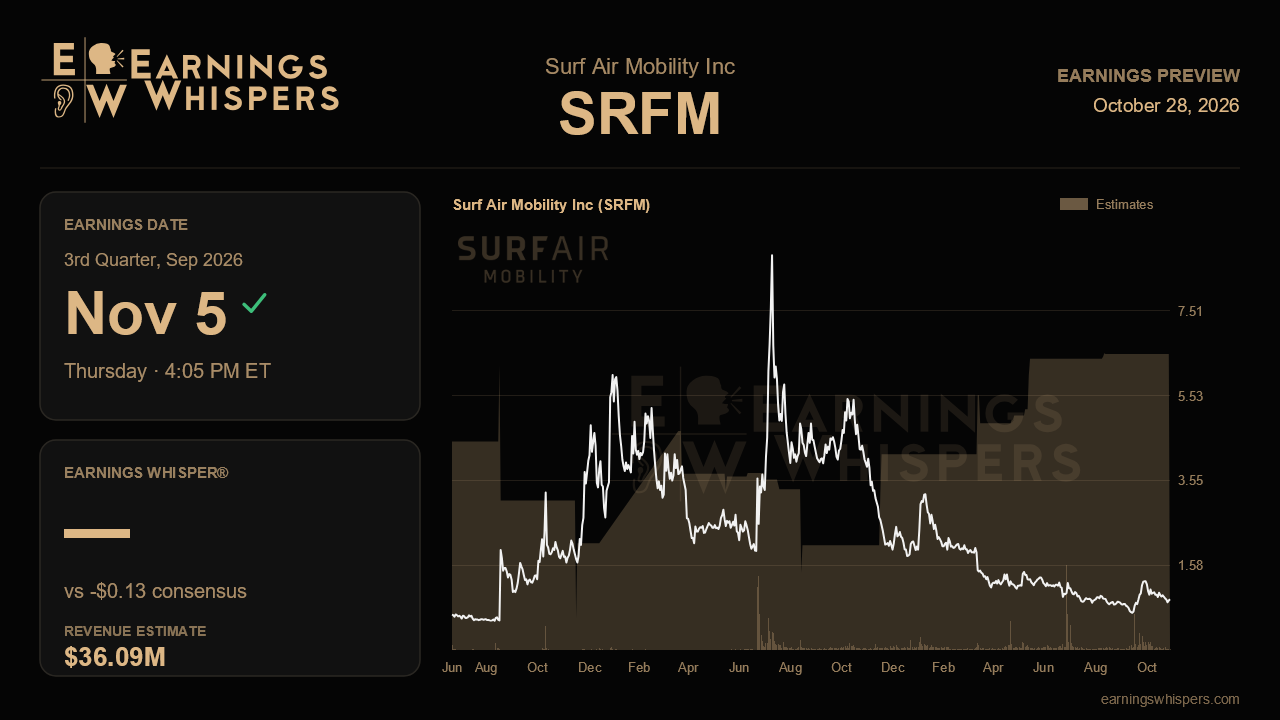
Surf Air Mobility spent its last earnings call telling investors the company had moved out of stabilization and into expansion. The third-quarter report, due after the close on November 5, is the first real chance to check that claim against numbers. Management has long said 2026 would be weighted toward the second half, and this is the quarter where that weighting has to show up. It arrives with the shares trading below a dollar and investor mood that has soured noticeably.
Wall Street expects a loss of 13 cents a share on revenue of about $36.1 million. That revenue figure would mark roughly 24% growth from the year-ago quarter. It would also be a sharp step up from the $29.5 million booked in the second quarter, when consolidated sales were barely higher than a year earlier. Management guided to third-quarter revenue of $35.5 million to $37.5 million and reaffirmed its full-year range of $128 million to $138 million. The consensus has climbed into that band and now sits just below the midpoint, so the Street is taking the company at its word without stretching beyond it. The expected loss would be about 80% narrower than the 64 cents lost a year ago. Much of that improvement reflects the restructuring and debt reduction already in place, which leaves revenue execution as the bigger swing factor.
The sequential jump depends heavily on charter. Surf on Demand generated $12.1 million in the second quarter, with departures up 67% and revenue per departure up 25%. Another strong showing would confirm that growth is coming from both more flying and better pricing. The independent broker program, halfway to its target of 100 at last count, should be a visible contributor if the momentum is real. Scheduled service, by contrast, is shrinking on purpose as unprofitable routes are cut. It fell about 20% last quarter. Further declines are not a problem in themselves, but management called the airline a bright spot for second-half profitability. Investors should look for margin improvement in that segment even as its revenue contracts. Fuel costs and Hawaii weather, both drags last quarter, remain the obvious risks to that promise.
The software story is where the narrative either gains weight or stalls. The Wheels Up BrokerOS contract, worth up to $12 million over two years, turned years of letters of intent into a paying customer. Roughly $2 million of that is expected to be collected this year. Management has also pledged a second enterprise contract by year-end and the launch of OperatorOS and OwnerOS in the fourth quarter. Progress on any of these, or evidence that the expanded Palantir partnership is speeding up sales cycles, would support the platform thesis. Vague updates would reinforce the worry that enterprise deals simply take too long. The full-year adjusted EBITDA loss target of $25 million to $30 million is another key marker. The second quarter alone lost $10.5 million, which leaves little room for slippage in the back half.
The market has not given management much benefit of the doubt. Shares have fallen almost 8% since the last report while the S&P 500 was roughly flat. At 78 cents, the stock sits well below its 200-day average near $1.23 and in the lower half of a post-earnings range of 46 cents to $1.34. That price keeps the NYSE deficiency notice and possible reverse split in the foreground. Sentiment has swung to nearly 75% bearish from about 43% a quarter ago. Expectations around the stock look more pessimistic than the business guidance implies.
The central question is whether third-quarter revenue lands inside the guided range on the strength of charter, while losses keep narrowing toward the full-year EBITDA target. If both happen, the expansion story holds and the gloom around the shares looks overdone. If revenue lands short of the range, the back-half thesis breaks. Debt amortization resumes in January 2027, leaving the company little time to rebuild credibility.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-28 | |
| Oct-23 | |
| Oct-15 | |
| Oct-15 | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-02 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 | |
| Sep-23 |
