Surf Air Mobility's Charter Boom Delivers A Record Quarter, But An EPS Miss, Wider EBITDA Loss Guide And Thin Cash Leave Little Room For Error
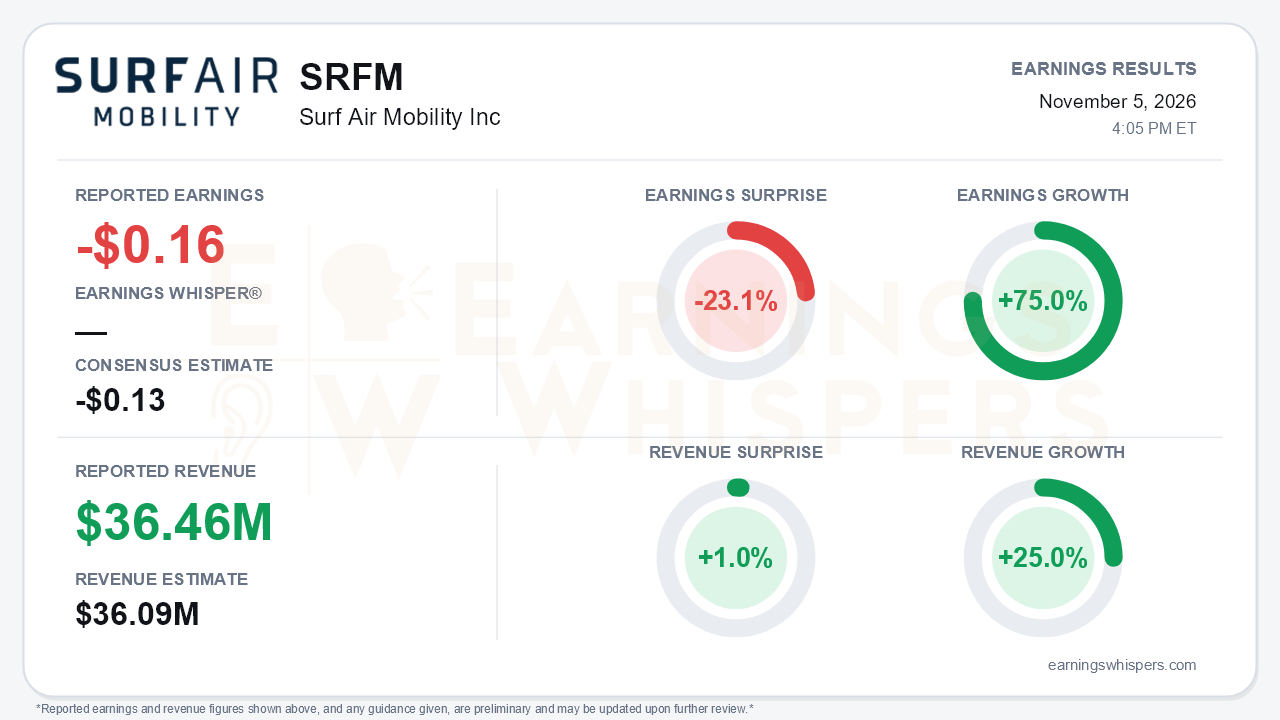
Surf Air Mobility posted the highest revenue and smallest Adjusted EBITDA loss in its history for the third quarter, yet still missed on the bottom line. The company lost $0.16 per share, wider than the -$0.13 consensus, a 23.1% shortfall. Revenue of $36.46 million edged past the $36.09 million estimate by 1.0%. The miss matters less than the underlying split. The operating business is clearly gaining traction. The software story that underpins the company's rebranding as a "technology-powered air mobility platform" slipped again, and management widened its full-year Adjusted EBITDA loss guidance. That is the central tension.
The top line genuinely accelerated. Revenue grew 25% year over year after gains of roughly 9% in Q1 and 8% in Q2, and rose 24% sequentially. That acceleration came almost entirely from Surf On Demand. Charter revenue reached a record $19 million, up 121% year over year and 57% from Q2, and it now exceeds scheduled service revenue for the first time. Scheduled service fell 15% to $17.5 million as Essential Air Service routes were exited.
The 75% year-over-year improvement in EPS needs context. Net loss narrowed 25% to $20.4 million, but weighted shares nearly tripled to 125 million from 42 million, so dilution drove much of the per-share gain. Restructuring and transaction costs of about $3.7 million were also added back in reaching the $6.7 million Adjusted EBITDA loss.
The call showed real operating progress. Surf On Demand departures rose 86% to 1,417. Revenue per departure climbed 17% year over year and 29% sequentially as the mix shifted toward larger aircraft and longer trips. Charter gross margin expanded more than 10 points from Q2, which suggests the growth is not being bought at the expense of profitability, helped by seven preferred operator partners.
The airline is also improving:
- Airline Adjusted EBITDA was positive at $1.2 million, and it has improved every quarter this year.
- Direct operating cost per block hour fell 6%, and labor productivity rose 15%.
- Consolidated Adjusted EBITDA losses have narrowed from $12.3 million in Q1 to $10.5 million in Q2 and $6.7 million in Q3.
- The Q4 guide of a $2.4 million to $5.4 million loss implies further narrowing.
SurfOS is where bears have legitimate ammunition. Software revenue was immaterial in Q3. The Wheels Up BrokerOS implementation scope was extended, which puts at risk the roughly $2 million of 2026 revenue management cited last quarter. The second enterprise contract promised "before year end" is now described only as "advanced discussions." OperatorOS did launch, and five contracts are signed on a percentage-of-trip-revenue model, meeting the year-end target on a signed basis. None are yet generating meaningful revenue, however, and updates on OwnerOS and the 100-broker goal were absent.
Full-year Adjusted EBITDA loss guidance moved to $32 million to $35 million from $25 million to $30 million. Management attributed the change to fuel, up about 37% per gallon, and longer SurfOS implementations. Full-year revenue guidance of $128 million to $138 million was reaffirmed, but the implied $36.4 million to $46.4 million Q4 range is unusually wide for a company of this size.
The balance sheet amplifies every execution risk. Cash was just $10.7 million at quarter-end, even after the full $21.6 million asset-backed facility funded. Current liabilities of $127 million dwarf current assets of $30 million, and current debt maturities have risen to $24.6 million. Management offered no breakeven date. The NYSE minimum price deficiency also remains unresolved, a concern given that the stock trades around $0.74. CFO turnover and a new SurfOS president from Palantir add both credibility and transition risk.
Investors were already skeptical entering the report. Sentiment fell meaningfully further into negative territory, from -0.43 to -0.74. Shares are down 13% from the $0.85 opening after the Q2 report and sit about 36% below the $1.17 200-day moving average. The inter-earnings period was extraordinarily volatile:
- The stock hit a 52-week low of $0.46 on September 16.
- It nearly tripled to $1.34 by September 30.
- It then gave back about 45% of that peak heading into the print.
That round trip suggests speculative enthusiasm around the platform narrative has not held. Trend readings are mixed, with momentum positive but AVWAP still negative.
The bottom line is that Surf Air Mobility's operating businesses delivered: charter is scaling with better margins, and the airline is now EBITDA-positive. But the company is being valued, and judged, on whether SurfOS becomes a real revenue stream. On that front, deadlines slipped and guidance moved the wrong way. With roughly $11 million in cash and a sub-$1 share price, the company needs the enterprise pipeline to convert soon. Q4 will test whether management can land within its wide guide and sign a second enterprise deal.
Read our earnings preview for Surf Air Mobility Inc: https://www.earningswhispers.com/article/SRFM/22388
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Oct-29 | |
| Oct-28 | |
| Oct-23 | |
| Oct-15 | |
| Oct-15 | |
| Oct-09 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Oct-06 | |
| Oct-02 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 |
