StepStone Must Prove Fee Momentum Can Outrun Spring Marks And Buy-In Doubts
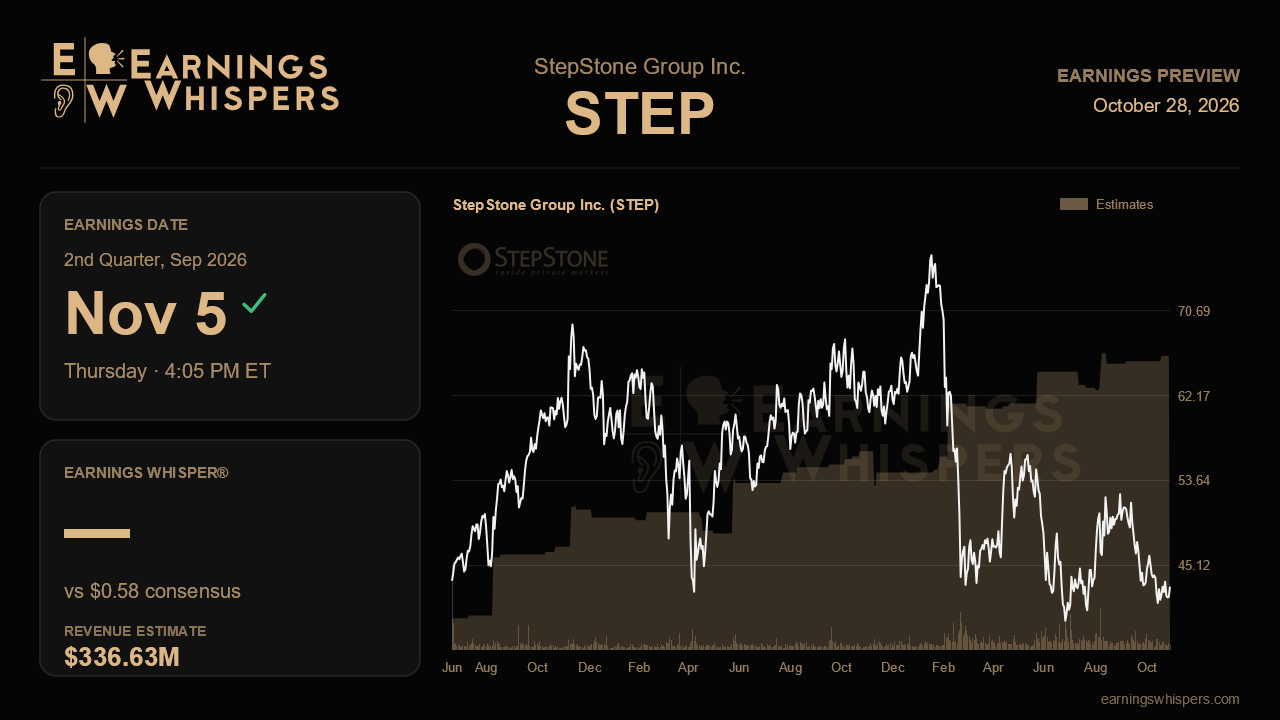
StepStone Group heads into its fiscal second-quarter report with an odd disconnect. Last quarter management described a business firing on nearly every cylinder, with fee revenue up 27% and fee-related earnings topping $100 million for a second straight quarter. Yet the stock has dropped about 16% since then while the S&P 500 barely moved. The November 5 release, due after the close, will help show whether the market has been too quick to discount that momentum or whether it correctly sensed trouble beneath the surface.
Wall Street expects adjusted earnings of $0.58 a share, up about 7% from $0.54 a year ago and a sizable step up from the $0.48 posted last quarter. Revenue is projected at $336.6 million, roughly 26% below the year-ago figure. That headline decline looks alarming but needs context. StepStone's reported revenue includes carried interest allocations that swing with portfolio marks, so a drop of that size points more to softer performance-related revenue than to any erosion in the recurring fee base. The real question is whether management fees keep climbing while the more volatile carry line cools. With no formal guidance on the table, the prior call's commentary sets the benchmark.
That commentary was upbeat. Fee revenue rose steadily from $217 million two quarters before last to $271 million, and another sequential gain would confirm the ramp is intact. Private wealth is the engine. Management saw no obvious ceiling on multibillion-dollar quarterly inflows into its Spring vehicles, and the flagship private equity secondaries fund, at about $2.5 billion, was raising money ahead of plan. Steady inflows and further secondaries closes would back up that confidence. A visible slowdown in wealth subscriptions would challenge the core of the bull case.
The offsets deserve equal attention. Management guided the commingled fund fee rate to stay roughly flat for several quarters as the repriced secondaries funds raise capital, leaving the blended rate near 63 to 64 basis points. Holding that range would be fine. A further slip would suggest the investment-period discount is biting harder than expected. Expenses are the other swing factor. Cash compensation rose to $117 million after April merit increases, and G&A is growing with distribution fees tied to wealth assets. If fee revenue keeps outpacing those costs, operating leverage holds. If not, margins could stall even with strong asset growth.
The carry book is where newer risks could show up. Net accrued carry was steady at $935 million, and more than 70% of it now comes from programs older than five years, which makes the book more ready to harvest. But management warned that Spring's net asset value could swing as public holdings, including a mid-teens SpaceX position already off its peak, come out of lockup. Spring incentive fees won't be recognized until fiscal Q3, so this report is more about protecting that December payday than collecting it. Investors will also want more detail on funding the SPW profits-interest buy-in, which short sellers have criticized for potential share issuance and cash needs.
Sentiment has edged from slightly bullish to slightly bearish, a small shift that still fits the stock's slide. At about $43, shares sit well below the 200-day moving average near $50 and closer to the post-earnings low of $40 than the $53 high, so expectations look subdued. The report will turn on whether fee-related earnings keep compounding fast enough to outweigh mark volatility and buy-in uncertainty. Another clean step up in fee revenue, steady fee rates and a credible funding plan would show the recent selloff priced in more risk than the business deserves.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-28 | |
| Oct-22 | |
| Oct-14 | |
| Oct-09 |
Blackstone Raises $1 Billion For Private Credit Continuation Fund As Secondaries Boom
STEP
Benzinga Private Markets
|
| Oct-01 | |
| Sep-28 | |
| Sep-28 | |
| Sep-17 | |
| Sep-14 | |
| Aug-31 | |
| Aug-31 | |
| Aug-26 | |
| Aug-18 | |
| Aug-18 |
