StepStone Beats On Fee-Driven Operating Leverage, But Buy-In Costs, Slower Wealth Inflows And Tight Exits Temper The Record Quarter
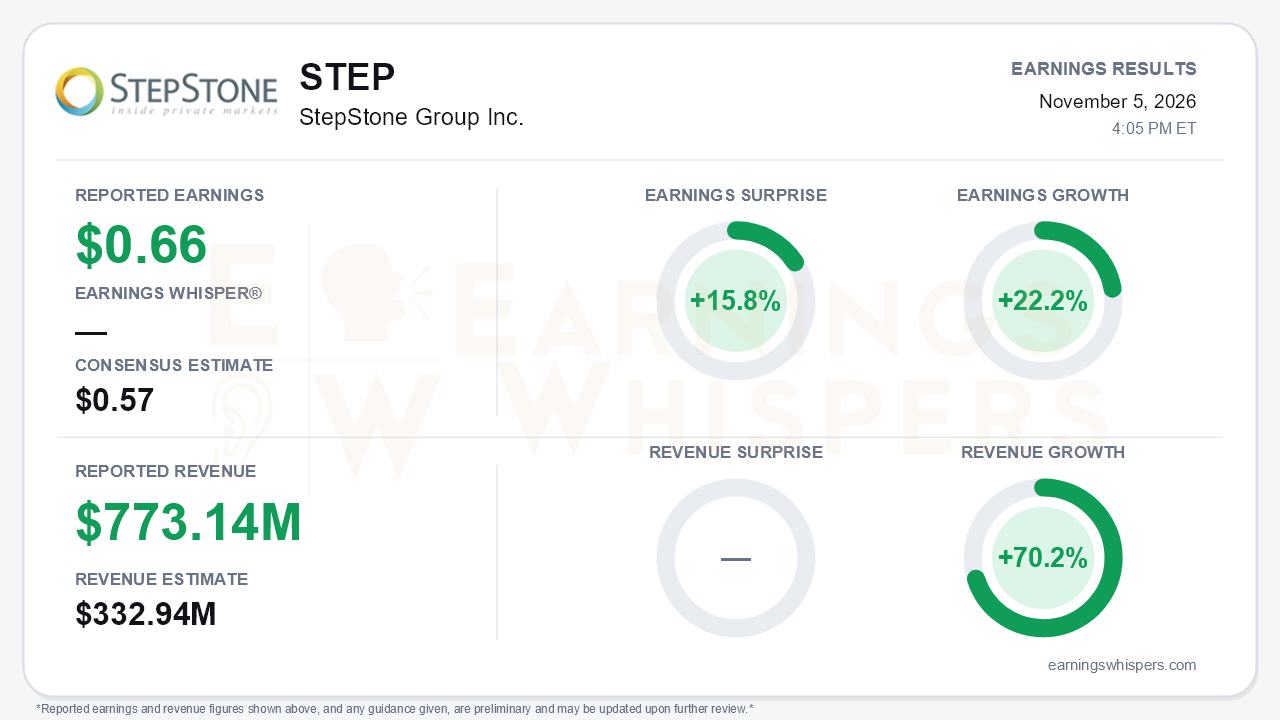
StepStone Group delivered its cleanest operating quarter in some time, and the beat came from recurring fees rather than carry. Adjusted net income was $0.66 per share, beating the $0.57 consensus by 15.8%. That was up 22.2% from a year earlier and a sharp rebound from $0.48 in the June quarter. Reported revenue of $773.14 million topped the $332.94 million consensus by 132.2% and grew 70.2%. That GAAP figure, however, includes $301.7 million of unrealized carried interest and $115.0 million of legacy Greenspring carry that belongs to others, so the revenue surprise says more about accounting presentation than about the earnings engine. The more telling numbers are fee-related earnings, which rose 61% to $126.2 million, and an FRE margin that hit a record 42%.
The quality of the beat holds up well. Fee revenues grew 37% year over year to $297.6 million, accelerating from 27% growth in the June quarter and 21% in March. Focused commingled fund fees jumped to $194.4 million from $127.1 million. Realized performance income did not drive the quarter:
- Gross realized performance fees were $65.1 million, essentially flat with a year ago.
- Performance-related earnings slipped 5%.
ANI growth of 24% lagged FRE growth of 61% because a growing slice of FRE flows to the private wealth profits-interest holders. That slice reached $29.6 million this quarter versus $10.1 million a year earlier. On a GAAP basis, the loss attributable to Class A holders narrowed to $0.87 per share from $4.66. Equity-based compensation tied to the profits-interest fair-value change fell to $379 million from $884 million, though it remains a large non-cash drag.
The call reinforced the growth narrative with improving forward indicators:
- Last-twelve-month gross AUM additions reached a record $43 billion, up from $38 billion two quarters earlier.
- Undeployed fee-earning capital hit a record $42.4 billion, up 42% year over year, a built-in source of future fees.
- The LTM management fee rate rose to 67 basis points from 63-64.
- Private wealth AUM climbed to $23 billion from roughly $15 billion two calls ago.
- The CFO lowered fiscal 2027 cash compensation ratio guidance to about 42% from 43%.
- Management now expects "meaningful" full-year FRE margin improvement over fiscal 2026's 38%, with further expansion into fiscal 2028 after the profits-interest buy-in.
The pipeline also looks strong. The debut infrastructure secondaries fund closed at its $1.5 billion hard cap. The venture secondaries fund activates in the December quarter, adding $1.8 billion of fee-earning AUM. Flagship funds have raised $11 billion against a roughly $20 billion prior-vintage baseline, and management expects to exceed prior fund sizes. Upcoming 401(k) and target-date announcements could open a new distribution channel. Net accrued carry crossed $1 billion for the first time, a reservoir for future realizations once exits reopen.
Bears still have legitimate ammunition:
- **Margin durability:** The CFO explicitly said 42% is not a run rate, citing full-quarter compensation for new hires and seasonal conference spending in the back half.
- **Wealth inflows:** Private wealth subscriptions slowed to $1.7 billion from $2.3 billion in March, though redemptions held near 2%.
- **SMA outflows:** Separately managed account distributions spiked to $3.2 billion from $0.7 billion a year ago, partly due to the expiration of a large mandate.
- **Shareholder returns:** The supplemental dividend, $0.55 last year, will be retained to fund the profits-interest buy-in, which could be up to 75% equity-financed and therefore dilutive. The regular quarterly dividend did rise to $0.33 from $0.28.
- **Macro headwinds:** A 10-year Treasury above 5% continues to slow exits and distributions.
- **Real estate:** Fee-earning AUM in real estate is down 6% year over year.
The market setup was decidedly cooler than the fundamentals. Investor sentiment slipped from roughly neutral (0.03) to modestly negative (-0.14) heading into the report. Shares fell 8.9% from the opening price after the August report to $46.40, about 5% below the 200-day moving average of $48.95. The stock has rebounded about 16% from its October 14 low of $40.05 but remains 12.5% below the mid-August high of $53.02. The Earnings Whispers trend readings are mixed: momentum has turned positive, while price and AVWAP trends remain negative.
The central tension is that StepStone's fee machine is accelerating just as investors are weighing rate-driven exit drag, slower wealth subscriptions and the cost of buying back the wealth profits interest. That buy-in is the key bridge. In the near term it costs shareholders the supplemental dividend and possibly some dilution. Over time it should recapture a fast-growing stream of FRE that currently leaks to minority holders.
The bottom line is that StepStone beat on the right line items: recurring fees, margin and fundraising, not one-off realizations. Management's upgraded compensation and margin outlook gives the story credible forward support. The record 42% margin will likely ease near term, and the payoff from the buy-in and the retirement channel is still ahead, which helps explain why a stock trading below its 200-day average reflects caution rather than enthusiasm.
Read our earnings preview for StepStone Group Inc.: https://www.earningswhispers.com/article/STEP/22392
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-28 | |
| Oct-22 | |
| Oct-14 | |
| Oct-09 |
Blackstone Raises $1 Billion For Private Credit Continuation Fund As Secondaries Boom
STEP
Benzinga Private Markets
|
| Oct-01 | |
| Sep-28 | |
| Sep-28 | |
| Sep-17 | |
| Sep-14 | |
| Aug-31 | |
| Aug-31 | |
| Aug-26 |
