Sarepta Faces A Revenue Step-Down As Alevitas Recovery Gets Its First Full Test
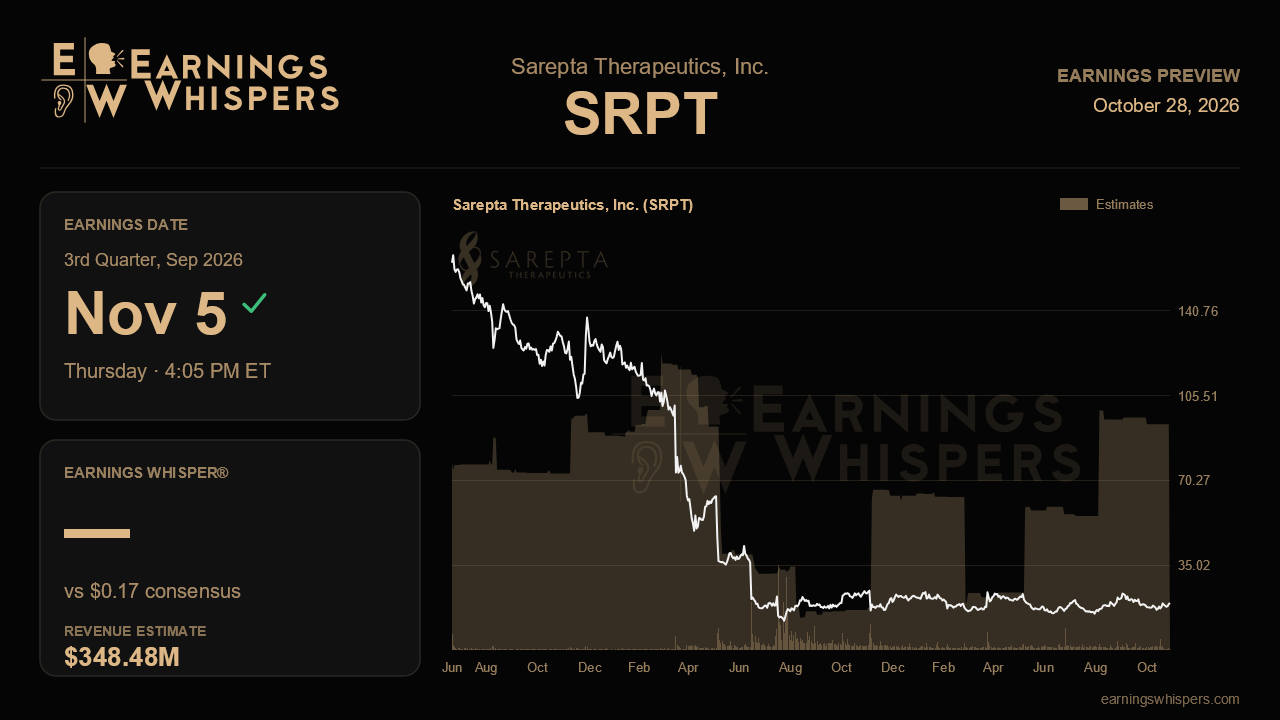
Sarepta Therapeutics heads into its third-quarter report with a stock that has rallied 16% since its last update, while Wall Street expects revenue to shrink. That tension makes the November 5 release, due after the close, more than a routine checkpoint. It is the first quarter in which the company's expanded Alevitas sales force has been fully in place for the entire period, and investors will want proof that the commercial reset management described is turning into actual demand.
The consensus calls for earnings of $0.17 per share on revenue of $348.5 million. On the surface the earnings comparison looks dramatic, a swing from a loss of $0.28 a year ago and an implied gain of roughly 161%. The top line tells a less flattering story. Revenue is expected to fall about 13% from the $399.4 million reported a year earlier and to step down sharply from the $401.3 million posted last quarter. Profitability is improving because of cost discipline, not growth. The company has held its full-year revenue guidance of $1.2 billion to $1.4 billion steady across three consecutive calls, but management has repeatedly urged caution and steered investors toward the low end. A quarter near consensus, paired with another reaffirmation, would keep that story intact. A trim to the range would confirm that the recovery is slower than hoped.
Alevitas is the swing factor. Its sales slid from $131 million in the third quarter of last year to $110 million in the fourth quarter and $102 million in the first quarter of 2026. On the last call, management said enrollment-form activity was stabilizing and improving, and that physician outreach was turning into enrollment forms within about a month. If that conversion speed is real, a full quarter with the contract sales force in the field should show up as steadier Alevitas revenue. A third straight sequential decline would undercut the claim that the bottom is in and would put the low end of guidance under pressure. Management itself has described the recovery as weighted toward the back half and into 2027, so stabilization rather than a sharp rebound is the reasonable bar.
The pipeline and regulatory calendar matter just as much for the stock. The second-quarter call brought a real setback: complete 12-week data from Cohort 8, the sirolimus study in non-ambulatory patients, slipped from the end of 2026 to the first quarter of 2027 because dosing is happening in sequence instead of in parallel. That trial is the route back to non-ambulatory labeling and supports the LGMD2E filing, so any further delay would hurt. Offsetting that, the applications to convert Amondys 45 and Vyondys 53 to traditional approval are under standard review with no advisory committee planned, putting a decision roughly ten months after the late-April submission. Investors should also look for the promised FSHD and DM1 RNA updates in the second half, any progress on the Huntington's program, and management's latest view of a possible Dyne exon 51 competitor that could arrive in late 2026 or 2027.
Sentiment has improved noticeably. Bearish readings fell to about 32% from nearly 52% ahead of the prior report, and the stock has beaten the S&P 500 by almost 16 percentage points since then. At $19.32, shares sit modestly above their 200-day moving average of $18.77 and roughly in the middle of their post-earnings range of $16.35 to $23.62. That is constructive, but well short of a breakout, which suggests the market has priced in some relief without assuming a full turnaround.
The central question is whether Alevitas has stopped shrinking. If the fully deployed sales force produces stable or rising sales and guidance holds, the recent rally has a foundation. If revenue keeps sliding while the key clinical catalysts sit in 2027, the improved mood could prove premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-26 | |
| Oct-22 | |
| Oct-16 | |
| Oct-14 | |
| Oct-12 | |
| Sep-30 | |
| Sep-30 | |
| Sep-25 | |
| Sep-24 | |
| Sep-22 | |
| Sep-08 | |
| Sep-08 | |
| Aug-31 | |
| Aug-27 |
