Sarepta Misses On Earnings As A Manufacturing Charge Crushes Margins, While PMO Strength Lifts The Revenue Floor And Shifts Focus To Imminent DM1/FSHD Data
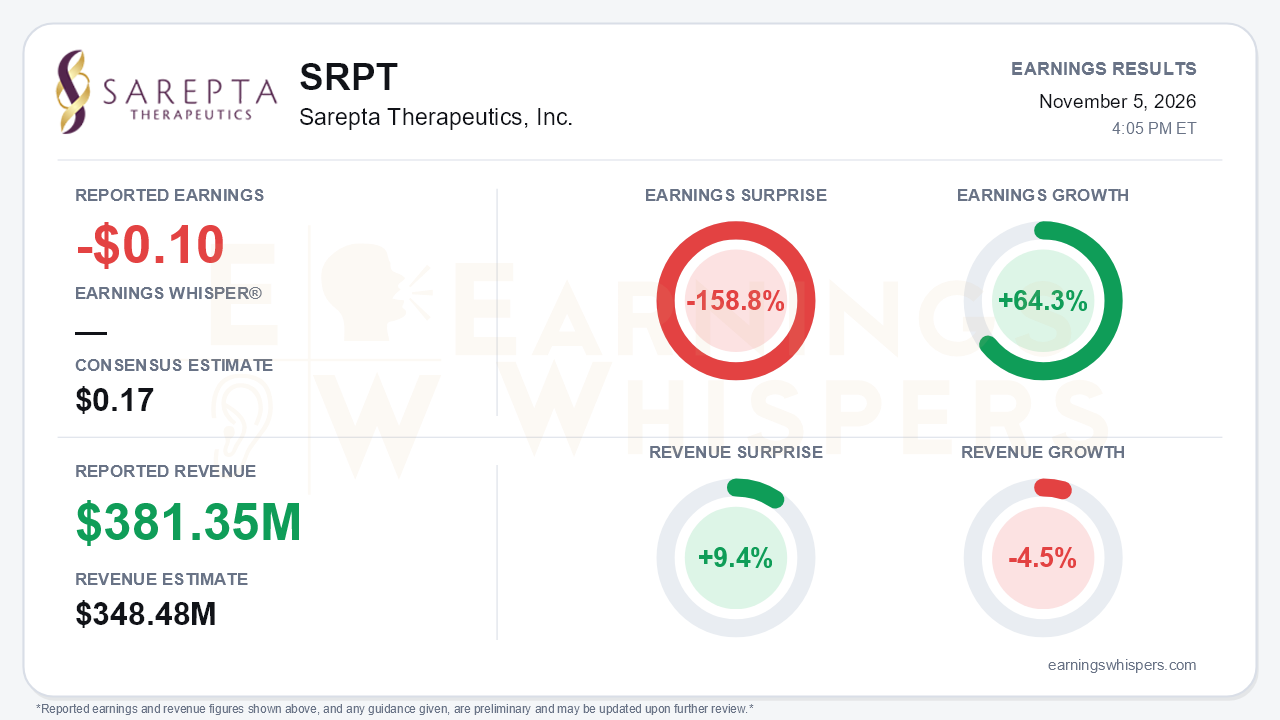
Sarepta Therapeutics reported a third-quarter loss of $0.10 per share, well short of the $0.17 consensus estimate, a 158.8% negative surprise. Revenue of $381.35 million beat the $348.48 million consensus by 9.4% but fell 4.5% year over year. Earnings still improved 64.3% from a year ago as the loss narrowed. The central tension is between a commercial business that is shrinking but generating cash and a pipeline story that management is now pushing hard ahead of binary data. The PMO exon-skipping franchise is carrying the quarter, ELEVIDYS has settled at a lower level, and the investment case increasingly depends on DM1 and FSHD readouts expected within weeks.
The quality of the quarter deserves scrutiny on both lines. The normalized loss of $0.10 falls between the company's GAAP loss of $0.27 and its non-GAAP profit of $0.13. The main swing factor was a take-or-pay charge on non-cancelable Catalent manufacturing obligations for inventory Sarepta chose not to make. The release puts that charge at $62.0 million in cost of sales. The call cited $52 million and said it cut product gross margin to 59%, versus 82% in the first quarter. Batch write-offs on Roche supply added further cost, and cost of sales rose to $188.5 million from $150.8 million. The revenue beat was also helped by non-product sources. Collaboration and other revenue nearly doubled to $57.6 million, including a $31.4 million increase in contract manufacturing revenue from ELEVIDYS supply shipped to Roche. Net product revenue fell to $323.8 million from $370.0 million, a 13% decline. Lower GAAP R&D mostly reflects lapping last year's $100 million Arrowhead milestone, not a structural change.
The conference call made the operating split explicit. PMO revenue rose to $240.3 million from $229 million in the first quarter, with new patient enrollments increasing. ELEVIDYS revenue slid to $83.5 million, down from $102 million in the first quarter and $110 million in the fourth quarter of 2025. Enrollment forms were only flat with the second quarter, and management declined to say when ELEVIDYS would return to growth. Earlier in the year, prior leadership had talked about green shoots. Now Q3 and Q4 are framed as a new baseline, and fourth-quarter ELEVIDYS revenue is guided to trend in line with Q3. Full-year net product revenue guidance moved to $1.25 billion to $1.3 billion from $1.2 billion to $1.4 billion. The floor rose $50 million, but the ceiling fell $100 million, and the range sits below Street estimates. On the positive side, non-GAAP R&D plus SG&A guidance tightened to $800 million to $825 million. Cash and investments rose to $998.7 million, with roughly $300 million of base-business cash generation year to date. In his first full call, new CEO Michael Severino struck a tone of focused optimism, a clear shift from his predecessor's more guarded posture.
The forward calendar is dense:
- **DM1 and FSHD:** Multiple ascending dose data for SRP-1003 (DM1) and SRP-1001 (FSHD) are expected by year-end. Sarepta has already begun manufacturing Phase 3 clinical supply and is preparing for both accelerated and traditional approval pathways. That is a confident bet, but Novartis's recent DM1 miss raises legitimate questions about endpoints and patient heterogeneity in pivotal design.
- **ELEVIDYS:** An sBLA for patients under 4 is planned for mid-2027. Initial data from the Phase 4 ENDURE study showed no acute liver injury events in the sirolimus-prophylaxis subset.
- **PMO franchise:** The Vyondys/Amondys sNDA has a PDUFA date around February 2027, and the Exondys 51 MISSION study reached last patient last visit.
Bears have ammunition too. A Dyne exon 51 competitor is expected to be approved in January 2027, with management expecting an impact on Exondys in the back half of 2027. That threatens the very franchise now holding up results. RegenxBio's potential DMD gene therapy launch in 2H27, the discontinued Envision non-ambulatory study, and the 2027 convertible notes maturity add further pressure.
Investor sentiment remains negative but improved meaningfully, rising to -0.23 from -0.52 at the prior report. The stock has gained 14.0% since opening at $16.66 after the August report, closing at $18.99 before this release. It has given back much of its September 2 peak of $23.62 and now sits 19.6% below that high and 16.2% above the inter-earnings low. The AVWAP trend reading remains negative, consistent with buyers who entered near the highs still sitting on losses.
The bottom line is that Sarepta's quarter was weaker than the revenue beat implies: a headline EPS miss, a sharp margin hit from manufacturing obligations, and an ELEVIDYS franchise management now calls a new baseline. Strong PMO results, cost discipline, and a nearly $1 billion cash position give the company a credible bridge. Still, guidance that trails estimates and approaching exon 51 competition mean the setup now hinges largely on whether the imminent DM1 and FSHD data justify the Phase 3 preparations already under way.
Read our earnings preview for Sarepta Therapeutics, Inc.: https://www.earningswhispers.com/article/SRPT/22389
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-26 | |
| Oct-22 | |
| Oct-16 | |
| Oct-14 | |
| Oct-12 | |
| Sep-30 | |
| Sep-30 | |
| Sep-25 | |
| Sep-24 | |
| Sep-22 | |
| Sep-08 | |
| Sep-08 |
