VTEX Must Prove Its Margin Engine Can Outrun A Stalling Top Line
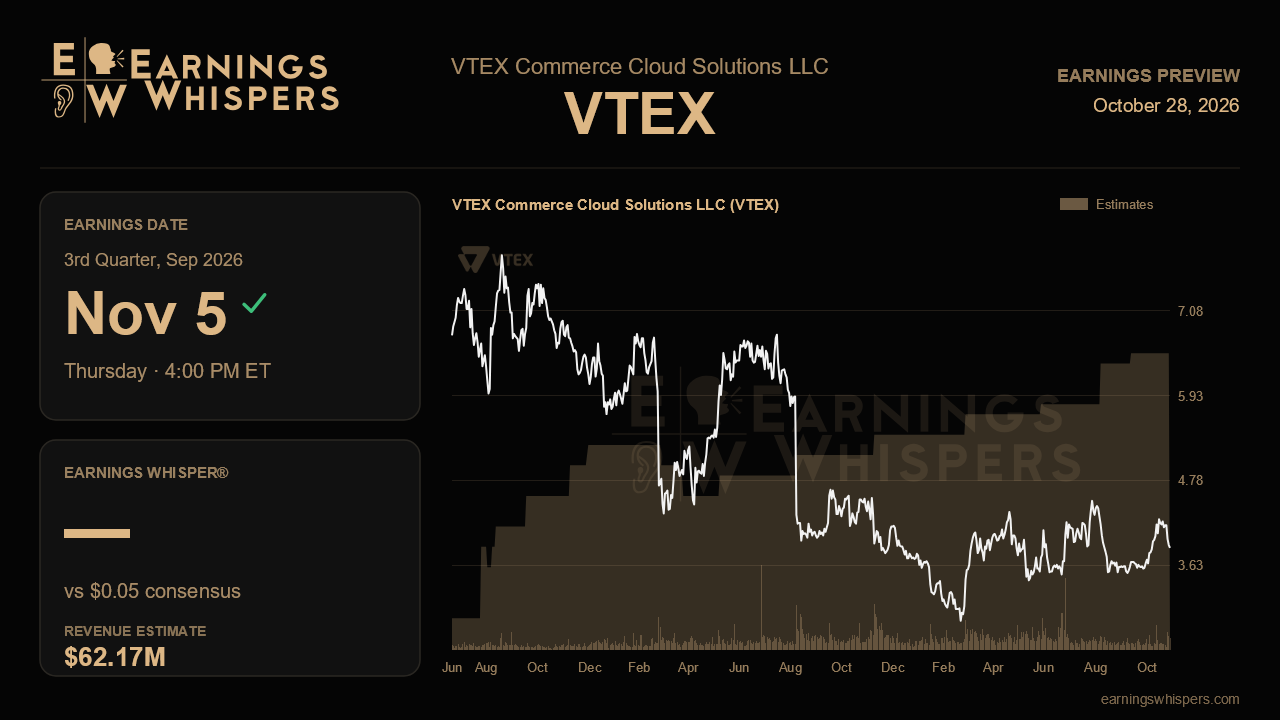
VTEX heads into its third-quarter report with two stories pulling in opposite directions. Profitability and cash generation have improved quickly, while revenue growth has slowed quarter after quarter and full-year guidance has been cut twice. The November 5 release, due after the close, will show whether the margin gains can keep earnings rising while revenue barely grows, and whether management can finally stop lowering its sales outlook.
The Street expects earnings of $0.05 per share on revenue of about $62.2 million. That would be a 66.7% gain in profit from a year ago but only 4.3% revenue growth, and a step down from the $64.4 million reported last quarter. Management guided third-quarter subscription revenue to roughly flat on an FX-neutral basis. The gap between that guidance and the Street's mid-single-digit reported growth figure suggests analysts are counting on favorable currency translation, a small beat, or both. If currency moves against the company, the revenue line could look weaker than the consensus figure implies, even if VTEX delivers exactly what it promised.
The guidance trend explains the market's caution. FX-neutral subscription growth has fallen from 15% a year earlier to 1.3% last quarter, and the full-year outlook has been cut from mid-to-high single digits, to mid single digits, to low single digits. Management blamed weaker consumer spending in Brazil in June and July, softer demand in Argentina, and customers shifting to larger accounts that pay lower take rates on the merchandise they sell through the platform. Executives stressed that churn and win rates were holding steady. If that is true, this quarter's results should show stable customer metrics even with flat revenue. A further drop in the core B2C business, which shrank about 2% FX-neutral last quarter, or a third guidance cut would undercut the argument that the slowdown is about economic conditions rather than competition.
Margins are where VTEX has the most credibility. Non-GAAP operating margin rose to 21.4% from 10% a year earlier. Subscription gross margin reached 81.8%, helped by AI-driven support automation, and free cash flow margin came in near 20%. Management raised its operating and free cash flow margin targets to the low 20s. Holding that level on flat revenue would show the cost savings are lasting, since there is little sales growth to absorb fixed costs. A slip back toward the high teens would suggest last quarter's results depended on one-time savings.
The growth initiatives offer the clearest signs of future demand. Global expansion, B2B, advertising and AI together make up 18% of subscription revenue and grew 20% FX-neutral. That share should keep rising. Investors should also look for progress on the more than 200 CX platform trials, especially paid conversions, given management's claim that sales cycles have been cut roughly in half. Updates on the AI Workspace waitlist of more than 100 enterprises and on deals sourced through partners such as Accenture and EY would show whether these efforts are becoming revenue or remain early-stage.
Sentiment has improved somewhat. The bearish reading has eased to about 32% from 61% before the last report, even though the shares fell 4% since then while the S&P 500 was roughly flat. At $3.86, the stock sits slightly above its 200-day moving average and in the middle of its post-earnings range of $3.44 to $4.44, so the market has not taken a strong position either way. The deciding factor is the full-year outlook. If VTEX keeps it unchanged, holds margins in the low 20s and shows the growth initiatives gaining share, the case for a profitable, cash-generating company waiting for growth to return remains intact. Another cut would make it harder to argue that revenue has stopped declining.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-21 | |
| Aug-28 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-22 | |
| Jun-08 | |
| May-26 | |
| May-07 | |
| May-07 | |
| May-06 | |
| Apr-24 | |
| Apr-23 |
