VTEX Misses On EPS As A Third Straight Guidance Cut Exposes A Stalled Top Line Beneath Strong Cash Flow
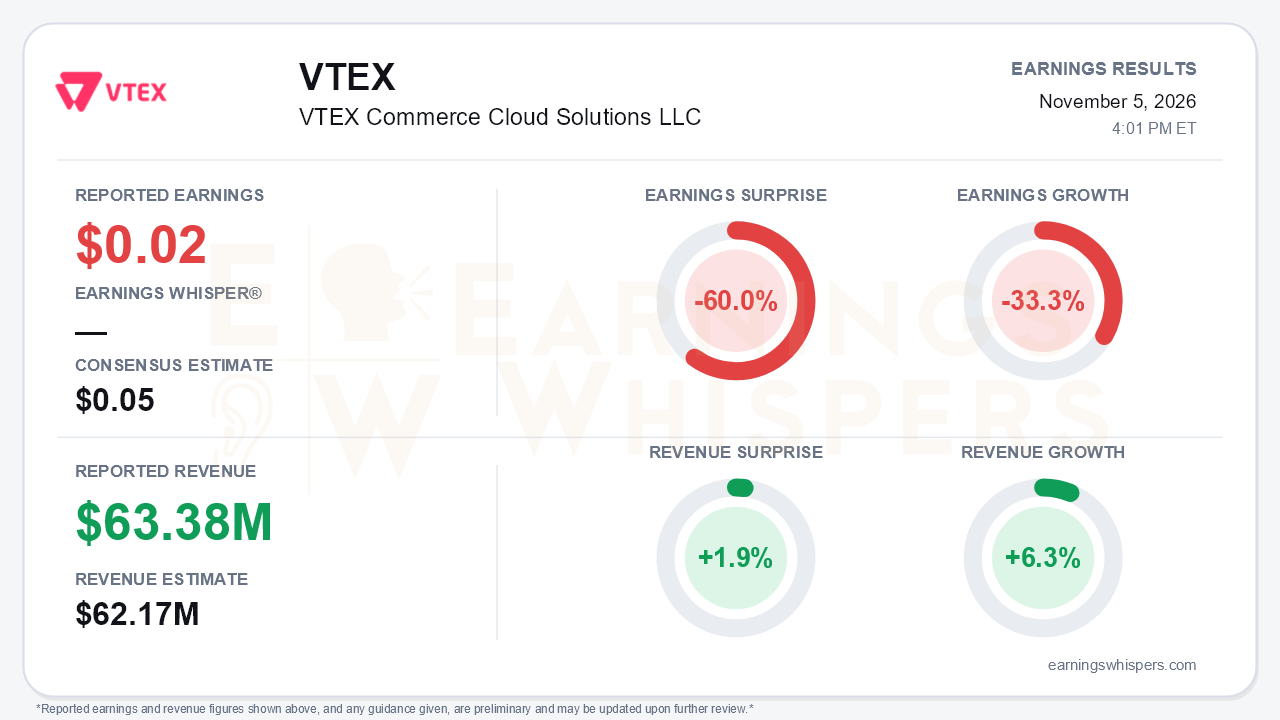
VTEX reported third-quarter earnings of $0.02 per share, missing the $0.05 consensus by 60.0% and declining 33.3% from a year ago. Revenue of $63.38 million beat the $62.17 million consensus by 1.9% and grew 6.3% year over year. Neither headline captures the most important development. The revenue beat came from currency, and management cut full-year top-line guidance for a third consecutive quarter. On an FX-neutral basis, total revenue slipped 0.4% and subscription revenue rose just 0.2%. That leaves a company that is generating more cash than ever while its core growth engine has nearly stopped. That is the central tension.
The quality of the quarter deserves scrutiny on both lines. The EPS miss was driven mostly below the operating line. Other income swung to a $2.9 million expense from a $2.2 million gain a year earlier, and the call attributed this to mark-to-market losses on the fixed-income portfolio. Those losses also lifted the tax bill to $1.3 million from essentially nothing. As a result, GAAP net income fell to $3.0 million from $6.4 million, and non-GAAP net income dropped to $7.0 million from $10.6 million.
Operating results looked better on the surface. Non-GAAP operating income rose 27% to $12.1 million, and GAAP operating income climbed to $7.2 million from $4.2 million. Headcount is down 10.1% year over year, and sales and marketing expense fell. Subscription gross margin improved 90 basis points to 81.1%. Free cash flow was the clear highlight, rising 77.3% to $13.3 million for a 21.0% margin, with trailing-twelve-month free cash flow reaching $50.4 million.
The call made the sequential picture look less flattering. FX-neutral GMV growth slowed to 4.5%, down from 7% in Q2, 6.8% in Q1 and 10.0% in Q4 of last year. FX-neutral subscription growth has followed the same path: 5.4%, then 4%, then 1.3%, and now 0.2%. Non-GAAP operating margin fell to 19.0% from 21.4% in Q2 and came in below the company's own low-20s guide. Management blamed heavier AI and token spending in R&D, which rose to $19.9 million from $16.7 million a year ago. Subscription gross margin also eased sequentially from 81.8%.
Guidance is where bears have the most ammunition. Management now expects roughly flat FX-neutral subscription revenue for fiscal 2026. That target has steadily eroded:
- mid-to-high single digits at the start of the year;
- mid single digits after Q1;
- low single digits after Q2;
- roughly flat now.
For the fourth quarter, seasonally the largest GMV period, the company guided to a low-single-digit FX-neutral decline. It cited further weakening in Brazilian consumption in October. Management also signaled no meaningful operating margin expansion in 2027. In addition, it described its strategic growth drivers only as growing at a 'double digit' rate, versus an explicit 20% in Q2, which may indicate moderation. Enterprise decision cycles remain elongated, and the call did not point to an inflection in commercial momentum.
The call did preserve a credible long-term product story:
- The CX platform had its strongest quarter, with annual contract value added up triple digits and about a third originating outside Brazil.
- A new CX AI model runs at 80% lower cost than the Q2 version.
- Kohler went live on a U.S. B2B distributor platform, a marquee North American reference.
- Avon in Saudi Arabia and Skechers in Brazil joined as new logos, and the Ads business moved into wellness, banking and travel verticals.
- Internal engineering productivity metrics improved sharply.
None of this has yet shown up in consolidated growth. Q4 guidance for mid-20s operating and free cash flow margins suggests profitability can recover even with a declining top line. Reported dollar results should also continue to get FX help, which the company estimates at about 3.5 points in Q4 and 7.4 points for the full year.
Investor sentiment was already firmly negative heading into the report and weakened slightly, moving from -0.61 to -0.66. Expectations were therefore low rather than collapsing. The stock has held up better than the fundamentals. Shares closed at $4.19 before the report, up 4.2% from the $4.02 opening after the August release. That price sat 21.8% above the late-August low of $3.44 and 5.6% below the October high of $4.44. Price and AVWAP trend readings are positive, while momentum is negative.
The company spent $10.8 million repurchasing 2.8 million shares at an average of $3.85 during the quarter, which likely helped support the stock. However, roughly 88% of the $50 million authorization is now used, so that support has limited remaining runway.
The bottom line is that VTEX delivered a cash-flow quarter attached to a growth problem. Free cash flow and gross margin are strong, and the AI and international proof points are real. Even so, a third straight guidance cut, a guided Q4 decline, and a missed margin target show that durable growth has not arrived. Until FX-neutral subscription revenue stabilizes, the buyback-supported share price and the product narrative will carry more weight than the reported numbers can justify.
Read our earnings preview for VTEX Commerce Cloud Solutions LLC: https://www.earningswhispers.com/article/VTEX/22410
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-21 | |
| Aug-28 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-22 | |
| Jun-08 | |
| May-26 | |
| May-07 | |
| May-07 |
