Verastem Must Prove Its Commercial Rebound Is Real As G12D Hopes Lift The Stock
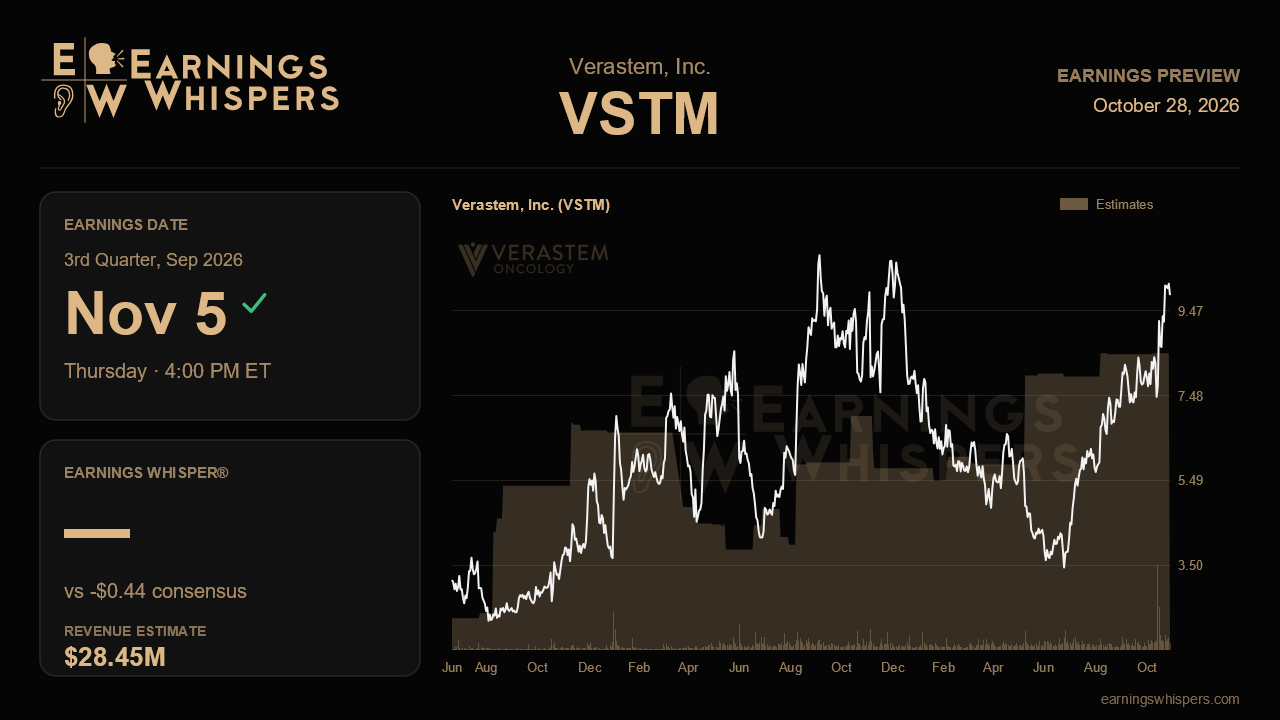
Verastem heads into its third-quarter report with the market having already paid up for a turnaround story. The shares have climbed nearly 48% since the last report while the S&P 500 barely moved, which means the November 5 release, due after the close, is less about whether the company can surprise skeptics and more about whether the commercial and clinical momentum management described in August is holding up under a brighter spotlight.
The Street is looking for revenue of about $28.5 million and a loss of $0.44 per share. Against the year-ago quarter, when revenue was $11.2 million and the loss was $1.35 per share, that is a dramatic improvement, with sales expected to rise roughly 153%. The sequential picture needs more care. Last quarter's reported revenue of $40.1 million included a $15 million Copictra sales milestone from Secura Bio, so the more useful comparison is net product revenue of $25.1 million. Consensus therefore implies product sales growth of roughly 13% to 14% from the second quarter, a slower pace than the 34% jump that took revenue from $18.7 million to $25.1 million. The wider expected loss compared with last quarter's $0.35 largely reflects the absence of that one-time milestone rather than any deterioration in the business. Verastem does not provide formal revenue guidance, so these estimates rest on the Street's reading of management's tone.
That tone was notably more confident last time. After a first quarter marked by a revenue dip, a leadership change and a launch review, management said the business was back on track and that momentum had carried into the third quarter. The drivers it cited are the ones to test now: more new patient starts, more consistent refills, and a shift toward use in earlier lines of therapy, where patients tend to stay on treatment longer. A product revenue figure at or above the high $20 millions would support the view that the first-quarter stumble was a seasonal and reauthorization blip. A flat or lower number would revive concerns that payers tightening on off-label use, along with the NCCN's decision not to expand its recommendation to KRAS wild-type patients, are capping the addressable market. The CFO also said gross margins were running better than modeled, and the company's adjusted loss narrowed to $0.31 per share, so a second straight quarter of expense discipline would strengthen the operating leverage argument.
The balance sheet should be less of a debate. The Oberland royalty facility and the Copictra milestone lifted pro forma cash to $201.4 million and pushed the runway into the second half of 2027, the third straight extension. Any slippage in that runway would be a meaningful negative, while commentary on drawing the remaining Oberland capacity or progress in the ARASCA partnership talks could extend it further without dilution.
The pipeline is where the stakes are highest. Management had planned a comprehensive VS7375 update in October covering response rates across pancreatic, colorectal and lung cancer cohorts of about 20 patients each, with early durability. The earnings call is the first chance to hear how the company frames those results against a crowded G12D field and how quickly its three registration-directed Phase II trials are enrolling.
Sentiment has warmed considerably, with the bearish reading easing to a slight 5.0% from 37.8% a quarter ago. The stock sits near $9.84, about 60% above its 200-day average and within a few percent of its post-report high of $10.22, a range that sits entirely above last quarter's $3.43 to $6.46 band. With that much optimism priced in, the central question is whether product revenue keeps climbing on its own merits. If it does, the market can keep treating VS7375 as upside layered on a working commercial business. If it stalls, the stock becomes a far more binary bet on clinical data alone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-22 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-14 | |
| Oct-11 | |
| Oct-05 | |
| Oct-02 | |
| Sep-28 | |
| Sep-28 |
