Trupanion's Pet Growth Faces A Test As Guidance Points To Slower Profit Gains
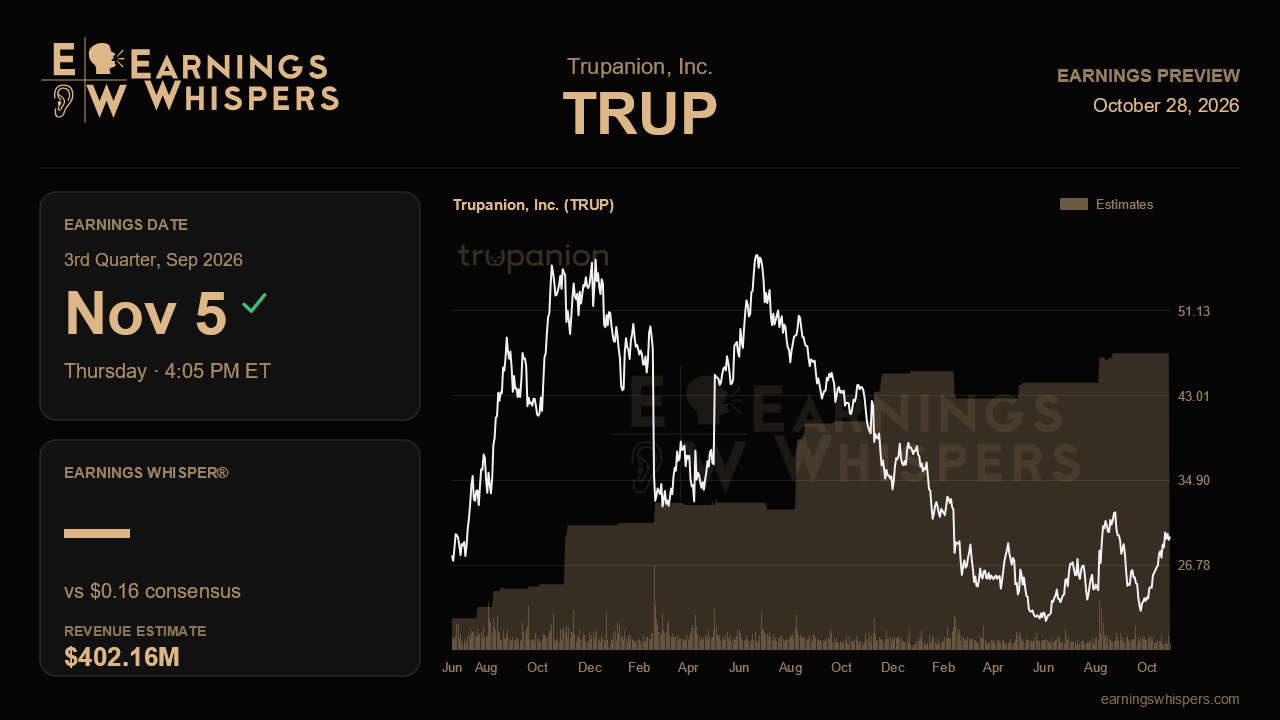
Trupanion enters its third-quarter report with an awkward split in its own story. Pet growth has been accelerating for a year, the company just launched its first-ever share buyback, and management sounds more like it is playing offense than at any point in recent memory. Yet the same management team guided third-quarter adjusted operating income to $44 million to $47 million, which implies only about 11% growth at the midpoint. That is well below the roughly 19% pace embedded in the full-year outlook. The question for November 5 is whether that slowdown is a deliberate choice to spend on growth or an early sign that the margin recovery is losing steam.
The Street expects earnings of $0.16 per share on revenue of $402.2 million. That would be about 23% EPS growth and roughly 9.6% revenue growth from the year-ago $0.13 and $366.9 million. Those are respectable figures for an insurer whose top line compounds mostly through retention and pricing. On a sequential basis, though, they are modest. EPS would be flat with last quarter's $0.16, and revenue would rise only about $9 million. The bar is not demanding on its face. The more important comparison is against management's own profit framework. Full-year adjusted operating income guidance was narrowed to $176 million to $184 million, which lifted the low end. A result at or above the top of the quarterly range would suggest the conservative third-quarter guide was simple caution. A result near the bottom would put the higher full-year midpoint in question.
The operating evidence that matters most begins with pet adds. Net subscription pet adds reached about 18,800 last quarter, up 39% from a year earlier, after even stronger gains in the two prior periods. Gross adds have quickened from 4% to 9% growth over that stretch. Management credits part of this to an expanded deductible and coinsurance rollout, now about half complete across North America, which should help web conversion and average revenue per pet. Holding net adds near recent levels would be meaningful because management also flagged an industry-wide decline in new vet visits and slower pet adoption. Those trends feed directly into Trupanion's lead funnel, which relies heavily on veterinary relationships. If net adds slip while acquisition cost per pet rises from $299, the growth narrative weakens fast.
On margins, the subscription business delivered a 15% adjusted operating margin last quarter, up from 13.8% a year earlier. The loss ratio, however, crept up to 70.2% from 69.1% in the fourth quarter, and veterinary inflation remains in double digits. Further drift in claims costs would explain the softer profit guide in a less flattering way than reinvestment would. Retention offers a quieter but useful signal. It has crept up every quarter to 98.37%, and any reversal would suggest price increases are starting to bite. Updates on the buyback pace, the $44 million dividend unlocked from subsidiary capital, and how management plans to replace PetsBest revenue before that relationship ends after the third quarter of 2028 will also shape the tone.
Investors have rewarded the story so far. Shares are up 7% since the last report, against a nearly flat S&P 500, and at $29.52 they sit comfortably above the 200-day moving average of $26.69, though below the post-earnings high of $32.09. Sentiment has moved the other way, swinging from mildly bullish before last quarter to moderately bearish now. That leaves a stock that has rallied while skepticism has grown. An in-line print may not be enough to carry the shares higher.
In the end, this report comes down to whether Trupanion can show that its accelerating pet growth is translating into durable profit, rather than being bought with a thinner margin. Steady net adds, a stable loss ratio and a reaffirmed full-year range would keep the offense-minded narrative intact. A weak funnel or rising claims costs would suggest the third-quarter slowdown is more than a pause.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Sep-10 | |
| Aug-13 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-16 | |
| Jun-24 | |
| Jun-18 | |
| May-26 |
