Trupanion Beats With Record Pet Growth And Cash Flow, But A Softer Q4 Profit Outlook Tempers The Story
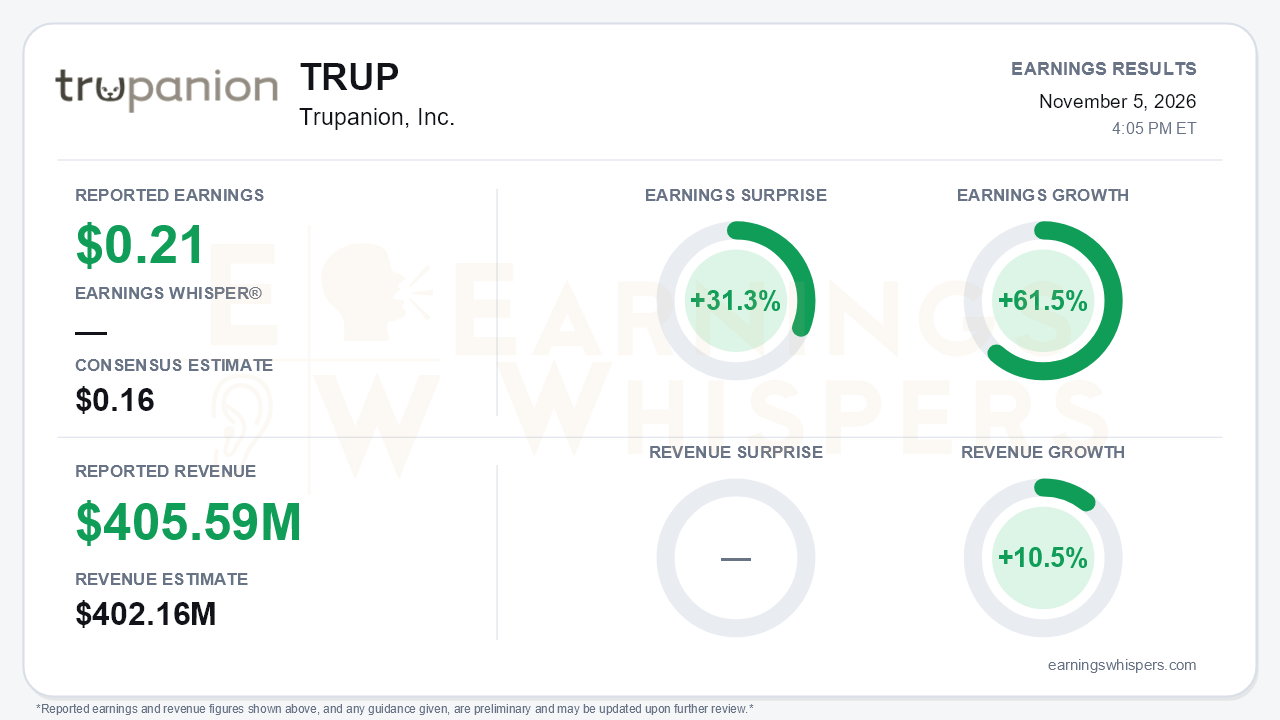
Trupanion delivered one of its cleanest quarters in years. Third-quarter GAAP earnings of $0.21 per share beat the $0.16 consensus by 31.3% and rose 61.5% from a year ago. Revenue of $405.59 million edged past the $402.16 million estimate by 0.9% and grew 10.5%. Subscription revenue rose 14% to $287.9 million, ahead of management's $284-$287 million guide, while adjusted operating income reached a record $47.0 million, at the top of its $44-$47 million range. The central tension is what comes next. Volume is accelerating and cash generation is at a record, but the fourth-quarter profit outlook implies the steepest slowdown in adjusted operating income growth this year.
The quality of the beat is mostly good, with some caveats. Operating income rose to $9.5 million from $5.9 million, and net income has climbed sequentially from $4.9 million in Q1 to $6.8 million in Q2 and $9.3 million in Q3. Several items below and around the operating line helped the GAAP comparison:
- Interest expense fell to $1.8 million from $2.8 million.
- Stock-based compensation dropped to $8.1 million from $9.5 million.
Adjusted EBITDA grew only about 6%, to $20.8 million, which is a more modest pace than the EPS figure suggests. The subscription business was the engine. The cost of paying veterinary invoices improved to 69.7% of subscription revenue from 70.1%, and free cash flow hit a record $28.5 million, up from $23.9 million a year earlier.
The operating story shifted noticeably toward volume:
- **Net pet adds** were roughly 20,500, up 28% year over year.
- **Gross adds** rose 13.8%, the best rate since 2023.
- **Pet acquisition cost** fell to $279 from $320 two quarters earlier, which management attributed to higher conversion.
- **Retention** improved for a seventh straight quarter, to 98.38%.
This matters because management said pricing increases are now the lowest since 2023. Pet growth, rather than rate, is carrying more of the load. Subscription pets grew 6% and monthly revenue per pet rose to $88.95 from $82.01. Total enrolled pets declined 2%, but that reflects the lower-margin Other segment, where revenue grew just 3%. That runoff should accelerate as the PetsBest book began moving to a new underwriter in Q4.
Bears have legitimate ammunition on margins. Subscription adjusted operating margin expanded only about 30 basis points, to 15.8% from 15.5%. That compares with roughly 120 and 130 basis points of expansion in Q2 and Q1. Fixed expenses rose to 5.8% of revenue on employee and technology costs, and the quarter included $0.6 million of adverse prior-period development. The fourth-quarter adjusted operating income guide of $48-$51 million implies about 10% growth, down from 29%, 24% and 15% over the first three quarters. Management also expects double-digit veterinary inflation to persist through 2027 and noted declining industry wellness visits. Lighter price increases against persistent cost inflation is the combination investors will watch most closely.
Offsetting that, the full-year outlook moved in the right direction. Management narrowed every range with higher midpoints:
- Subscription revenue: $1.131-$1.133 billion.
- Adjusted operating income: $179-$182 million.
- Total revenue: $1.590-$1.597 billion.
Capital allocation also turned more shareholder-friendly. The company bought back about 0.8 million shares for $25 million in its first use of the $100 million authorization and fully repaid its $15 million revolver after quarter end, while holding $396.8 million in cash and short-term investments. Management called this its most confident call of the year. Forward catalysts include:
- the Simon Cowell brand partnership;
- coinsurance and deductible options now available across about 90% of the U.S., with no promotional push yet;
- record veterinary clinic software adds;
- a March 1 Investor Day.
The market setup is more complicated than the surprise implies. Shares opened at $27.59 after the August report and closed at $33.68 heading into this release, a 22.1% gain. The stock sat just 1.1% below its inter-earnings high of $34.06, set the day before the report, and more than 50% above its late-September low of $22.05. Investor sentiment moved the other way, falling from +0.14 to -0.14 into the print. That is a meaningful swing from mildly positive to mildly negative while the price rallied. The Earnings Whispers trend signals were uniformly positive, consistent with a stock that had already priced in a good deal of the improvement.
The bottom line is that Trupanion's growth engine looks healthier than at any point in recent years. Net adds, retention, acquisition efficiency and cash flow are all improving, and the balance sheet now supports buybacks. However, margin expansion is clearly decelerating, the Q4 profit guide implies a sharp step-down in growth, and veterinary inflation shows no sign of easing. With shares near their quarterly high and sentiment already souring, the burden shifts to proving that volume-led growth can sustain earnings momentum without help from pricing.
Read our earnings preview for Trupanion, Inc.: https://www.earningswhispers.com/article/TRUP/22404
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 6 hours | |
| Oct-28 | |
| Oct-20 | |
| Oct-14 | |
| Oct-08 | |
| Sep-10 | |
| Aug-13 | |
| Aug-10 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-16 |
