TPG Mortgage Must Show Legacy Cleanup Is Lifting Earnings As Shares Sink Toward Lows
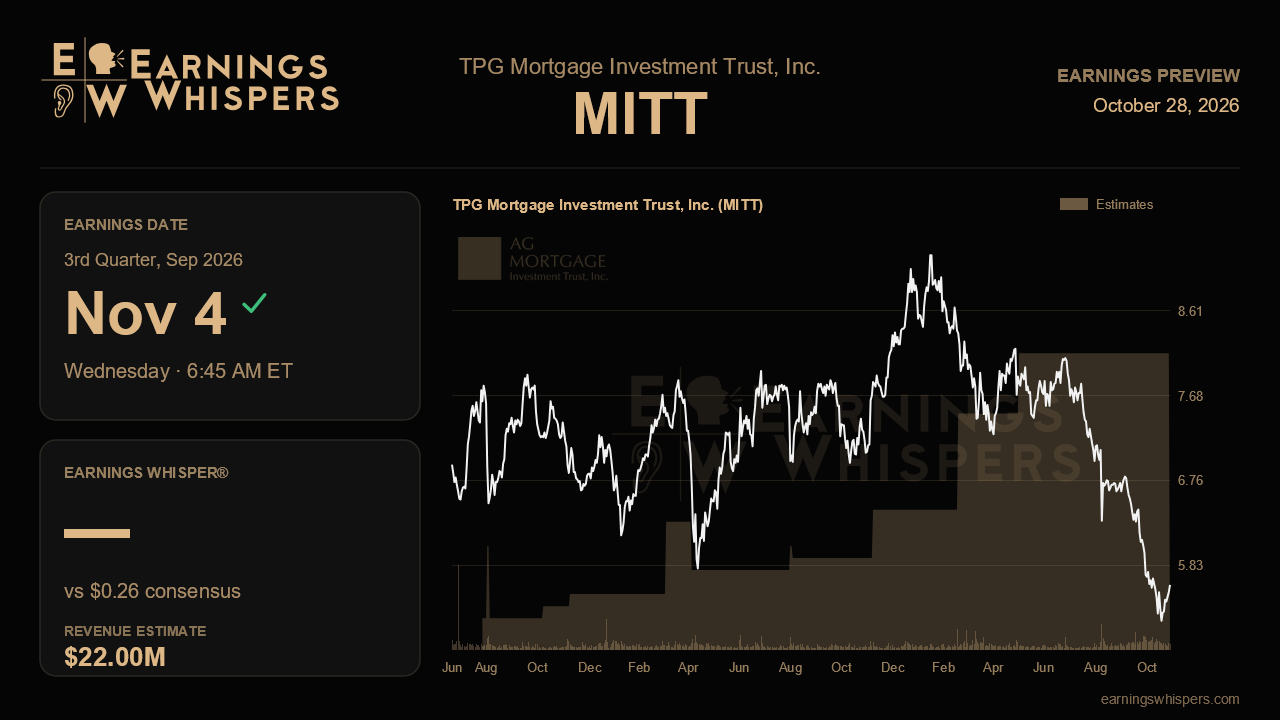
TPG Mortgage Investment Trust heads into its third-quarter report with an odd disconnect. Management spent the last call describing a company entering a new growth phase, with a transformational acquisition of Cherry Hill Mortgage, a quantified earnings tailwind from legacy commercial assets and a booming home equity business. The market has responded by marking the stock down 14% since that call, leaving shares at $5.62, roughly 56% of the $10.00 book value reported for the second quarter. The November 4 release, due before the open, is the first real chance to show that the promised earnings lift is arriving and not just being forecast.
The Street is looking for earnings of $0.26 a share, up from $0.24 last quarter and 13% above the $0.23 earned a year ago. That would match the first-quarter high-water mark and rebuild the cushion over the $0.24 quarterly dividend, which was left unchanged last quarter after four raises in seven quarters. Consensus revenue of $22.0 million implies an 82% drop from the year-ago figure, but that comparison looks more like a difference in reporting basis than a collapse in the business, and it deserves less weight than earnings available for distribution and book value. Management did not issue formal guidance, so the call commentary is the yardstick.
The most testable promise concerns the legacy commercial book. Management said two hospitality assets would be resolved by the end of the third quarter at carrying value, with a retail asset sale closing by year-end, together worth roughly $0.05 a share in near-term annual earnings and more than $0.15 later once the remaining two hotels are remarketed. Confirmation that the hotels resolved on schedule and without a markdown would validate the thesis that trapped capital is being redeployed into higher-yielding assets. Any slippage, or a resolution below carrying value, would undercut both the earnings bridge and book value. Investors should also note that the other two hotels have been pushed to next year under new management, so the larger chunk of that accretion remains a 2027 story.
Operating momentum elsewhere needs to hold up. Management guided to more than $1.25 billion of home equity securitizations across three deals in the third quarter, up from over $750 million in the second, and evidence that those deals priced and closed matters because the segment is the company's main growth engine. The counterweight is competition, which management acknowledged is compressing returns in non-agency and home equity. ARC Home, the mortgage origination affiliate, contributed a steady $0.04 per share in each of the last two quarters, and sustaining that would show the multi-year-high funding volumes were not a one-off. Book value is the other swing factor; it has yet to recover to the $10.46 to $10.48 range of late 2025.
Sentiment has soured noticeably, swinging from mildly bullish before the last report to clearly bearish now. The chart tells the same story. Shares sit well below the 200-day moving average of $7.41 and near the bottom of the $5.20 to $6.85 range since the last report, a band that lies entirely beneath the prior quarter's $6.91 to $8.33 range. Some of that selling likely reflects unease about the Cherry Hill deal, which lifts pro forma leverage to about 2.9 turns from 1.8 and adds mortgage servicing rights, an unfamiliar asset class, along with integration risk.
That combination sets a low emotional bar but a demanding factual one. Updates on the expected fourth-quarter close and the $7 million to $9 million in projected cost savings will help, but the core issue is simpler. If the hotels resolved at carrying value, earnings reach the mid-twenties and book value holds near $10, the growth narrative stays intact and the discount looks excessive. If the legacy cleanup stalls or book value slips again, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Sep-17 | |
| Sep-15 | |
| Aug-17 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-03 | |
| Jun-16 | |
| Apr-29 | |
| Apr-29 |
