Haverty's Written-Sales Surge Faces Fuel And Freight Test In Third-Quarter Report
Haverty Furniture enters its third-quarter report with a gap worth noticing. Last quarter, written sales grew double digits in every month, and delivered comparable sales climbed from roughly 4% in April to about 11% by June. Yet Wall Street is modeling only mid-single-digit revenue growth for the September quarter. Either analysts are being prudent about a furniture recovery that has disappointed before, or the order book management built over the summer is about to show up in a bigger way than the consensus assumes.
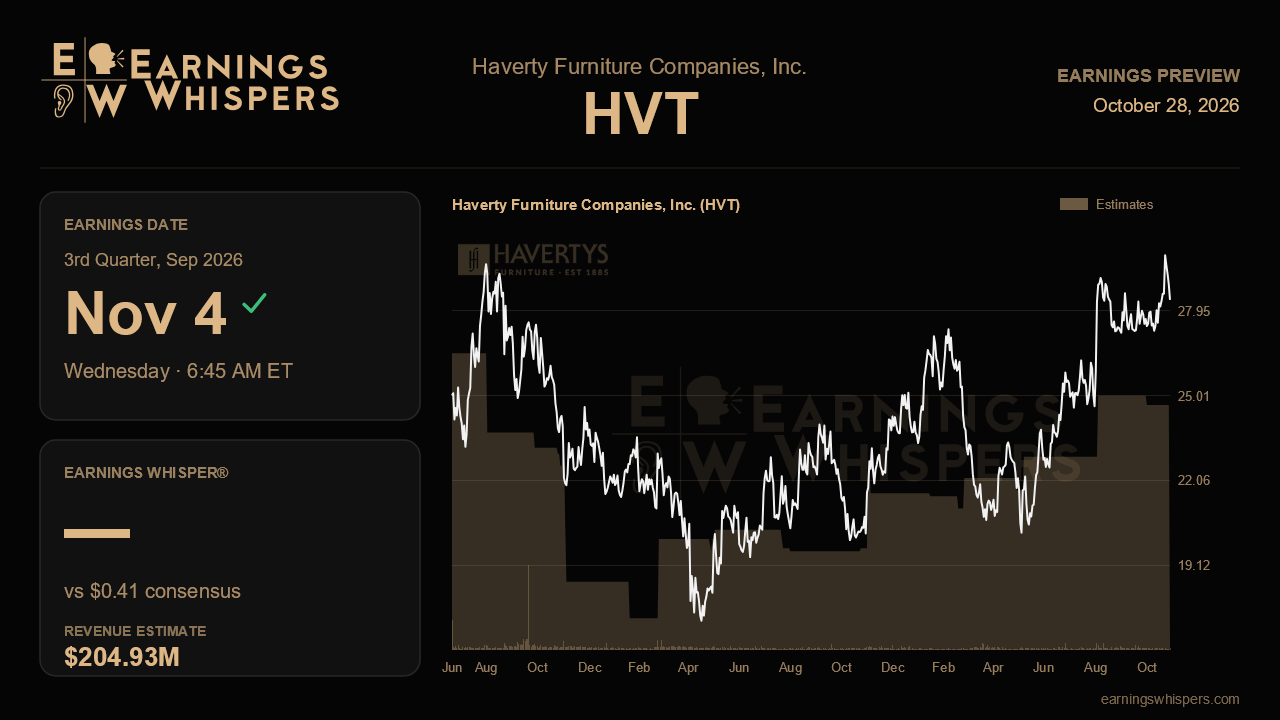
The Street expects earnings of $0.41 a share on revenue of $204.9 million when the Atlanta-based retailer reports before the open on November 4. That works out to revenue growth of about 5.4% from the $194.5 million posted a year earlier. Earnings would rise more than 46% from $0.28, which implies meaningful operating leverage on modest sales gains. The company has not issued fresh quarterly guidance, but it held its full-year framework last quarter. That framework calls for gross margin of 60.5% to 61% excluding tariff refunds, fixed SG&A of $307 million to $309 million, and variable SG&A of 18.7% to 18.9%. The variable SG&A range was nudged up because of higher third-party credit costs tied to 60-month no-interest financing.
The bullish case rests on what happened last quarter. Comparable sales accelerated to 8% from 4.3% in the first quarter, and written comps nearly doubled to 12.3%. Average ticket rose 14% to more than $3,800. Design business, where tickets topped $8,800, rose to 36.5% of sales, and special orders jumped nearly 24%. Traffic turned slightly positive, and every category and district grew. Because written sales ran ahead of deliveries, some of that demand should convert into third-quarter revenue. Delivered comps holding near the high single digits would validate the story. A slide back toward the low single digits would suggest the spring surge pulled orders forward rather than marking a durable turn. Written trends through Labor Day and into the fall also matter, since they determine whether the fourth quarter has a similar cushion.
Margins are the bigger swing factor. Management flagged container rates rising 25% to 30% from mid-August and diesel above $5 a gallon, which hits both inbound freight and home delivery. It also expects higher product input costs through year-end, and Section 232 tariffs on upholstered wood remain at 25%. Offsetting that, lower Section 301 tariffs took effect in late July, and the company expects another $1 million to $1.5 million in tariff refunds later this year. That means reported gross margin could be flattered. The cleaner test is whether margin excluding refunds stays inside the 60.5% to 61% band despite the freight spike. Credit costs deserve scrutiny too. Heavy reliance on long-term financing helps drive big tickets, but it eats into the leverage the consensus is counting on.
The growth pipeline should also produce evidence. Six openings were planned for the second half, including entry into Pennsylvania, and management is targeting 133 stores by year-end. Early reads on the St. Louis and Nashville locations, which were running ahead of plan, will help show whether expansion adds to earnings or weighs on fixed costs. Buybacks, including a privately negotiated purchase of 600,000 shares in June, will give per-share results a modest lift.
The market has already rewarded the acceleration. Shares are up about 7% since the last report, beating the S&P 500 by more than five points. At $28.33, the stock sits comfortably above its 200-day average of $25.03, and its entire post-earnings range sits above the prior quarter's. Still, it remains about 5% below its recent high of $29.88. Sentiment has also cooled, shifting from mildly bullish before the last report to mildly bearish now. That suggests some skepticism that the momentum can survive rising costs.
The central question is whether Haverty's demand strength can outrun its cost inflation. If delivered sales capture the summer order backlog and margins excluding refunds hold despite fuel and freight, the recovery narrative strengthens. If revenue merely meets modest estimates while freight erodes margins, the stock's recent gains may be harder to defend.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Sep-18 | |
| Aug-07 | |
| Aug-04 | |
| Aug-04 | |
| Jul-28 | |
| May-15 | |
| May-05 | |
| Apr-28 | |
| Mar-03 | |
| Feb-24 | |
| Feb-24 | |
| Feb-24 | |
| Feb-24 |
