Willdan's Third Guidance Raise Meets A Skeptical Tape As Tax Headwinds Hit Q3
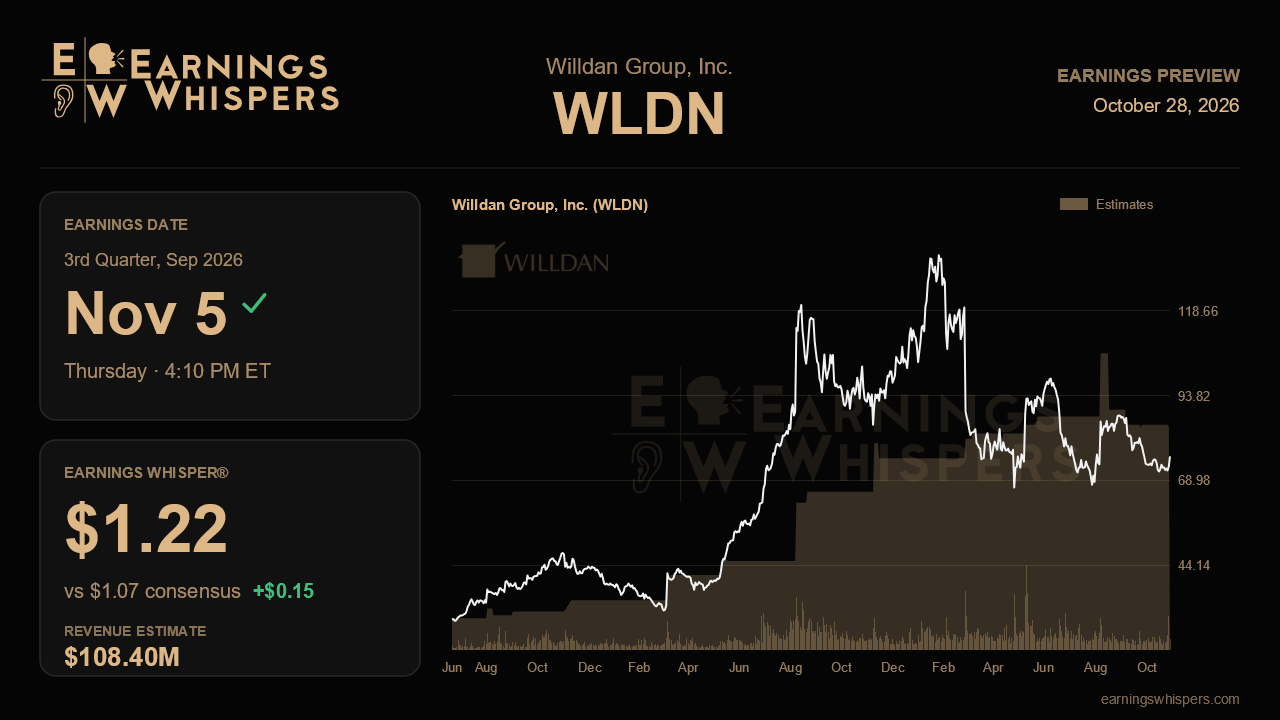
Willdan Group heads into its third-quarter report with an unusual disconnect. Management has raised its full-year outlook at every call this year, posted record profitability last quarter and lifted its long-term margin ambitions, yet the stock has slid 11.5% since that report while the S&P 500 barely moved. The November 5 release, due after the close, is the first quarter to absorb the loss of the 179D tax incentive and the first real look at whether the Burton acquisition and the expanded Los Angeles streetlight work can carry momentum into the back half.
The Street is looking for non-GAAP earnings of $1.07 a share, only a few cents above the $1.03 earned a year ago. The quarterly revenue consensus of $108.4 million implies a roughly 40% year-over-year drop, but that figure deserves caution: it appears to track net revenue, which ran $117 million in the second quarter, against a year-ago comparison based on the larger contract revenue line. The underlying business is not shrinking. The more meaningful tell is the whisper number of $1.22, a notable 15 cents above consensus, suggesting the informed bar sits well above the published estimate. That gap fits a pattern in which Willdan has beaten by wide margins and then raised guidance by less than the size of the beat.
The full-year math reinforces that point. Management now expects adjusted earnings of $5.00 to $5.15 a share on net revenue of $415 million to $430 million, up from an initial $4.50 to $4.70. Consensus sits at $4.95, below the low end of the company's range, which implies analysts either doubt the second half or are modeling the higher tax rate more aggressively than management. With the 2H tax rate expected at 15% to 20% versus essentially zero earlier, some per-share compression is baked in, so the cleaner read on operations will come from adjusted EBITDA and margin.
That is where the prior call set the terms. Management guided to roughly a 25% adjusted EBITDA margin for the year and warned that the second quarter's 28.2% pulled some revenue forward and would not repeat. A third-quarter margin in the mid-20s would validate the story; a slide well below that would revive concern about gross margin, which fell 150 basis points last quarter as lower-margin commercial work grew to about a quarter of revenue. Willdan has argued that leaner overhead offsets that mix shift, and this quarter tests whether the offset holds without a revenue tailwind.
The growth catalysts need visible traction too. Burton, closed in early May, arrived with new logos such as Walgreens, Carter's and Five Below plus cross-selling in both directions, and a first full quarter should show whether that contributes as hoped. Management also expects the APG business to nearly triple to around $75 million this year. The biggest swing factor is the $110 million LADWP streetlight expansion, whose ramp could land in the third or fourth quarter or slip into early 2027. Management explicitly cited that uncertainty as the reason for its restrained guidance, so any clarity on timing could unlock upside to the range. Updates on the battery storage pipeline, the $53 million City College of New York project and free cash flow conversion above 70% of EBITDA round out the checklist.
Sentiment has swung from firmly bearish before the last report to modestly bullish now, even as the stock trades at $76, well below its 200-day average near $87.50 and closer to the bottom of its post-earnings range than the top. That combination leaves room for a rerating if results land cleanly. The central question is whether Willdan can hold a margin near 25% while its tax shield fades and LADWP timing remains open. A fourth consecutive raise would keep the narrative intact; a mere reaffirmation could confirm the market's doubts.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-06 | |
| Sep-22 | |
| Aug-17 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-15 | |
| Jul-06 | |
| May-07 | |
| May-07 | |
| May-05 | |
| Apr-15 | |
| Apr-13 | |
| Apr-08 |
