Willdan Raises Guidance Again And Bets Big On Mantis, But A Normal Tax Rate Flattens Q3 EPS And Leverage Jumps
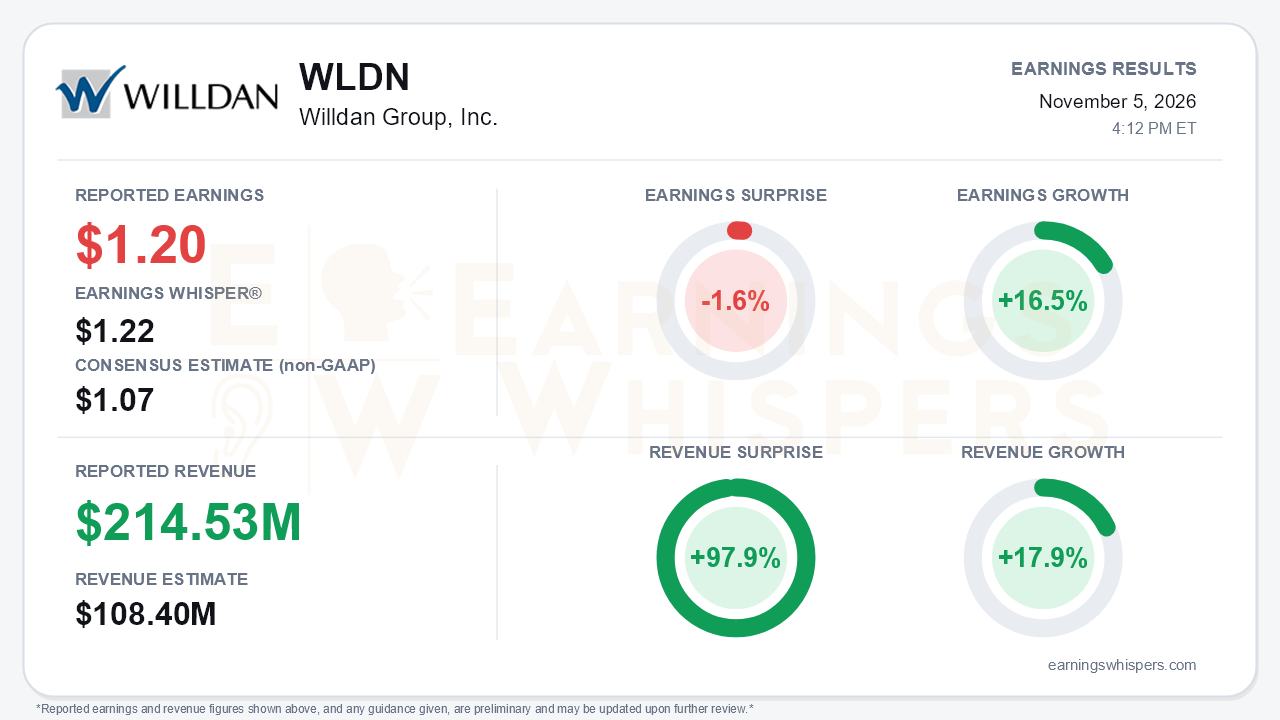
Willdan Group (NASDAQ: WLDN) reported third-quarter adjusted earnings of $1.20 per share, comfortably above the $1.07 consensus but 1.6% short of the $1.22 Earnings Whisper number. On Earnings Whispers' normalized basis, earnings grew 16.5% year over year and revenue rose 17.9% to $214.53 million. The quarter combined strong operations with an earnings line that stalled. Net revenue grew 18%, adjusted EBITDA rose 22% to $28.3 million, and management raised full-year guidance for the third consecutive call. It also introduced preliminary FY2027 targets above $1 billion in contract revenue. But Willdan's own reconciliation shows adjusted EPS essentially flat ($1.20 versus $1.21), and GAAP diluted EPS fell to $0.76 from $0.90. Investors buying the story are now buying the 2027 picture, not the Q3 print.
The headline numbers need two caveats. First, the 97.9% revenue surprise is mostly a basis mismatch. The $108.4 million consensus appears aligned with net revenue, which came in at $112.2 million, not with the $214.5 million of contract revenue that includes pass-through subcontractor costs. Second, the gap between Earnings Whispers' 16.5% EPS growth figure and the company's flat adjusted EPS reflects different prior-year baselines. Under Willdan's own presentation, per-share earnings did not grow. The main reason is taxes: the effective rate normalized to roughly 23% from about 4% a year ago after the 179D deduction expired. Below-the-line costs added pressure too. Stock-based compensation rose 58% and G&A depreciation and amortization rose 48%, holding pre-tax income growth to about 8%. Operationally, though, gross margin expanded roughly 150 basis points to 38.4%, and the EBITDA margin reached 25.2%.
The call also showed clear deceleration from a very strong second quarter:
- Contract revenue growth slowed to 18% from 33%.
- Net revenue growth slowed to 18% from 23%.
- Adjusted EBITDA growth slowed to 22% from 51%.
- EBITDA margin eased to 25.2% from 28.2%, a decline management had flagged in Q2.
Organic net revenue growth of about 12% remains healthy. Year-to-date EBITDA margin of 24.7% versus 21.6% shows a structurally more profitable mix. Guidance has climbed steadily. Adjusted EBITDA has moved from an initial $85–90 million to $109–111 million, and adjusted EPS from $4.50–4.70 to $5.15–5.25. Part of the latest raise reflects about two months of Mantis contribution, so not all of it is organic upside. Management's tone was the most confident of the year, citing "once-in-a-generation" energy trends.
The Mantis Innovation acquisition is both the catalyst and the risk. As the largest deal in Willdan's history, it adds roughly $75 million of net revenue at about a 35% EBITDA margin. It also brings blue-chip commercial and industrial clients such as Hershey, Frito-Lay and DataBank, and lifts commercial work to about a third of the pro forma mix, up from roughly 7% in 2024. Two developments temper that story:
- **Smaller deal than advertised:** Mantis's expected net revenue contribution was lowered to about $75 million from the $120 million previously communicated, following an accounting review. Management framed this as offset by the higher margin profile.
- **Much higher leverage:** Funded with a $250 million term loan and a $35 million revolver draw, the deal pushes pro forma net debt to about 2.3 times EBITDA, from 0.2 times. Management does not target getting below 2.0 times until Q3 2027.
Cash conversion is also lagging. Year-to-date operating cash flow fell to $32.9 million from $40.9 million as receivables swelled. New awards add support. These include a 10-year NYPA IDIQ recompete worth about $50–60 million a year, a roughly $25 million-a-year Con Edison/National Grid program, and $36 million in Menlo Digital substation and Texas battery-storage work. Analysts pressed on political and permitting backlash against data centers. Management said it sees no slowdown, but bears have legitimate ammunition there.
The market has not been rewarding the narrative. As of November 4, before the report, shares traded at $74.20. That is 13.7% below the open following the August report and 13.6% beneath the 200-day moving average near $85.85. The stock sits just 5.7% above its October 15 low of $70.20, after sliding nearly 17% from a September 2 peak of $89.33. Investor sentiment remains negative but improved meaningfully, rising from -0.47 to -0.09, suggesting skepticism was easing heading into the print. Earnings Whispers trend signals lean negative on price and AVWAP, though momentum reads positive.
The bottom line is that Willdan delivered another guidance raise and a credible path to a $1 billion revenue company with expanding margins. However, Q3 itself showed decelerating growth, flat adjusted EPS once taxes normalized, weaker cash conversion, and a balance sheet that went from net cash to meaningful leverage in a single deal. Whether the stock recovers its 200-day average likely depends less on this quarter than on proof that Mantis integrates cleanly and that the FY2027 EBITDA target holds.
Read our earnings preview for Willdan Group, Inc.: https://www.earningswhispers.com/article/WLDN/22413
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Oct-30 | |
| Oct-28 | |
| Oct-06 | |
| Sep-22 | |
| Aug-17 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-15 | |
| Jul-06 |
