Blink Charging's Margin Turnaround Faces Its Proof Point As Revenue Shrinks And Cash Thins
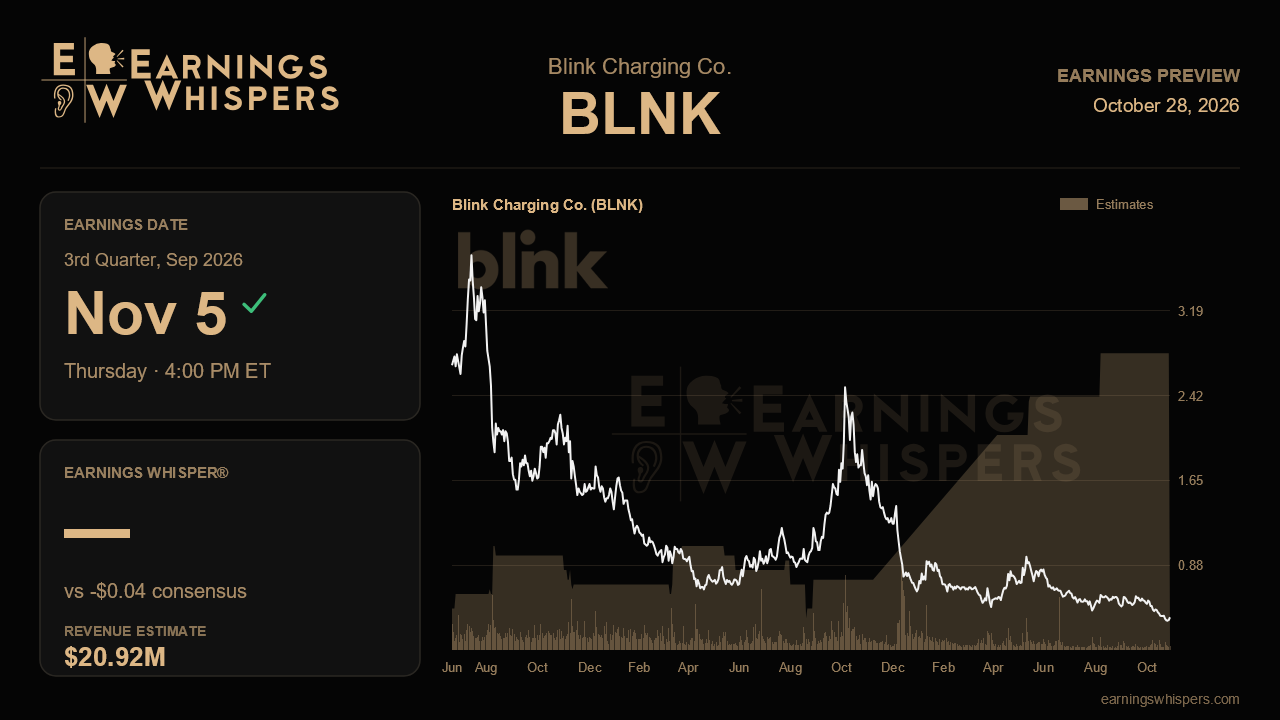
Blink Charging has asked shareholders to accept a smaller company in exchange for a healthier one. When it reports third-quarter results after the close on November 5, the question is whether that trade is paying off fast enough. The bet looks reasonable on paper while the balance sheet keeps getting thinner.
Analysts expect a loss of 4 cents a share on revenue of about $20.9 million. That would match last quarter's per-share loss and improve sharply on the 10-cent loss from a year ago, a 60% gain in the earnings line. Revenue, however, would fall roughly 23% from $27.0 million and dip slightly from the $21.7 million posted in the second quarter. The sequential slip is not alarming. Management cut its full-year revenue outlook to $83 million to $90 million from $105 million to $115 million, and the first half produced roughly $42.5 million. Hitting the range requires about $20 million to $24 million a quarter from here, so the quarterly estimate sits near the low end of management's implied pace. The full-year consensus of about $105.6 million still reflects the old guidance and looks stale. It should drift down toward the company's range, and the gap is a reminder that some forecasts have not caught up with the reset.
The revenue cut was framed as a deliberate choice. Management said it is walking away from unprofitable contract renewals, and it sold the Envoy car-sharing business in June, removing about $4.7 million of annual revenue. This will be the first full quarter without Envoy, so a lower top line is expected. What matters is whether the quality argument shows up in the margins. Gross margin jumped to 38.9% last quarter from 32.0% in the first quarter and under 16% at the end of 2025, and the full-year target was lifted to about 38%. A third-quarter figure near or above that level would validate the pivot. A slide back into the low 30s would suggest the second quarter benefited from a favorable mix rather than a structural change.
The same test applies further down the income statement. Adjusted EBITDA losses shrank to $2.2 million from $5.1 million, helped by operating expenses falling to $14.7 million from $18.4 million. Management still says it can reach roughly breakeven adjusted EBITDA by the fourth quarter and turn positive for all of 2027. That promise needs another clear step this quarter. If the loss stalls or widens, the breakeven timeline loses credibility. Product sales rose 20% sequentially last quarter after a steep year-over-year decline, and evidence that this stabilization held would ease fears that the revenue base is still eroding.
Cash is the uncomfortable counterweight. Blink ended June with $34 million, down from $38 million, and warned that burn would rise as it builds out DC fast charging, targeting about 169 sites and 519 stalls by year end. Progress on that buildout, along with any early traction for the Energy Connect energy-management platform and the retrofit opportunity across roughly 1,500 dealer-installed DC chargers, would help investors judge whether the spending is building a recurring revenue base or simply draining reserves. Battery storage integration is not slated until the first half of 2027, so this report is more about early signs than results.
The market has not been patient. Shares have fallen about 24% since the last report while the S&P 500 was flat, and at 41 cents the stock trades well below its 200-day average of 64 cents and close to its post-earnings low of 38 cents. Sentiment has nonetheless improved from deeply depressed levels a quarter ago, which suggests some see the margin story as underappreciated. The report will likely turn on one issue: whether margin and EBITDA gains are durable enough to reach breakeven before rising capital spending eats too far into a shrinking cash cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-28 | |
| Oct-28 | |
| Sep-14 | |
| Aug-18 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Jul-28 | |
| Jul-28 | |
| Jul-07 | |
| Jun-15 | |
| Jun-05 | |
| Jun-03 | |
| May-13 |
