Republic Airways Raises Its Outlook Again, But Merger-Driven Growth Hides A Softer Quarter
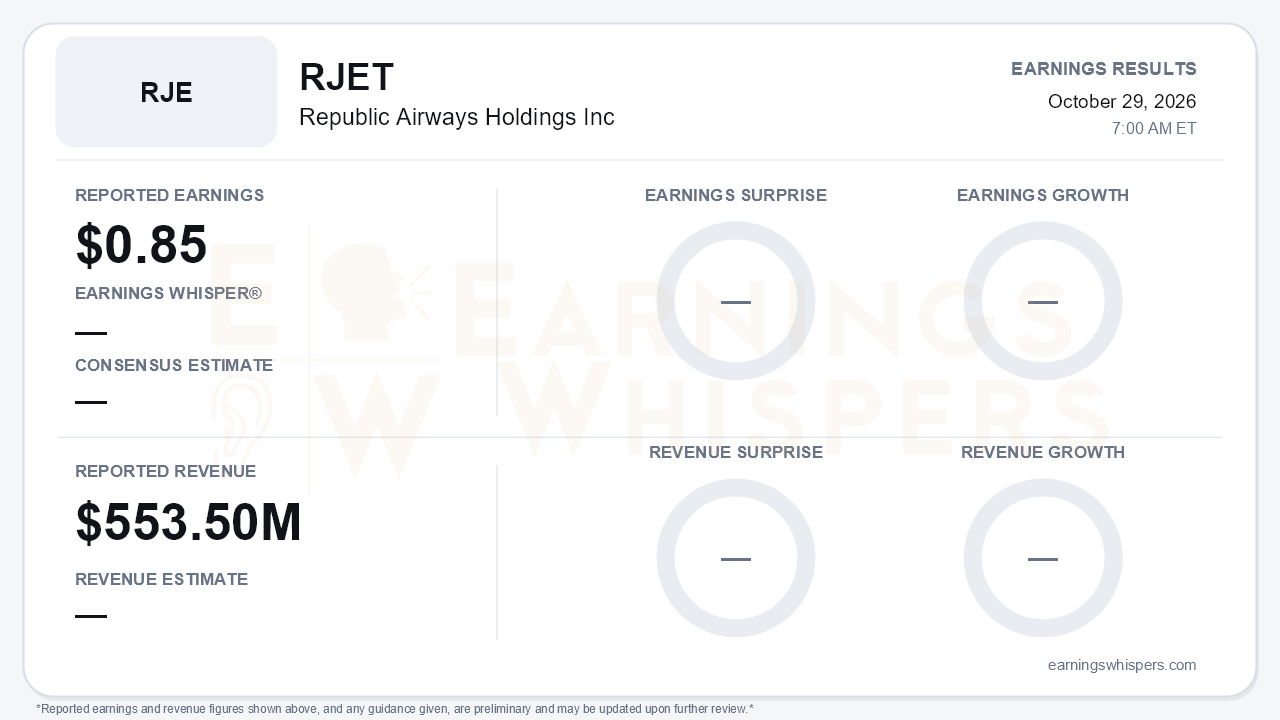
Republic Airways reported third-quarter adjusted earnings of $0.85 per share on revenue of $553.5 million, and raised its full-year adjusted EBITDAR guidance for the second straight quarter, to $410-$420 million from $395-$405 million. It also introduced adjusted EPS guidance of more than $3.30. On a year-over-year basis the quarter looks strong. Revenue rose 34.3%, and adjusted EPS climbed from $0.67. Much of that growth, however, comes from adding Mesa, which closed in November 2025 and is absent from the prior-year comparison. Sequentially, the quarter was softer. That is the central tension: the guidance is moving up while the latest quarter moved down.
The quality of the growth deserves scrutiny. Block hours rose 26.2%, driven by the 60 United-owned E175s that Mesa brought over. Another $49.1 million of the revenue gain was pass-through revenue, mostly shop-level maintenance tied to harmonizing Mesa's fleet. That revenue is low-margin, and it showed up on the cost side: maintenance and repair expense jumped to $133.5 million from $78.2 million. The result was an adjusted operating margin of 12.6%, exactly where it stood a year ago. The business got bigger, not more profitable per dollar.
GAAP results look more dramatic. Net income rose to $34.6 million, or $0.75 per diluted share, from $6.7 million, or $0.17. That jump mainly reflects executive separation and merger charges falling to $6.7 million from $25.0 million, not a change in underlying earning power. The diluted share count also rose to 46.3 million from 40.3 million, so per-share gains trail the growth in absolute profits.
The call explained why management still sounded confident. Executives said results outperformed their internal forecast despite a weather-hit summer. Completion factor fell to 92% in July before recovering to 97.6% by September, and controllable completion held at 99.96%. Even so, the sequential numbers slipped:
- adjusted EPS fell from $0.89 in Q2;
- adjusted EBITDAR fell to $106.8 million from $109.6 million;
- adjusted pre-tax income dipped to $55.6 million from $57.4 million;
- quarterly completion factor fell to 94.6% from 98.2% in Q2.
The raised outlook also implies a lighter fourth quarter. Republic has generated $316.5 million of adjusted EBITDAR and $2.52 of adjusted EPS through nine months. The new guidance therefore points to roughly $93.5-$103.5 million of Q4 EBITDAR and more than $0.78 of adjusted EPS, both below Q3. There is a minor discrepancy on revenue guidance. The release reiterates approximately $2.1 billion, while the call summary referenced more than $2.1 billion. Neither source signaled a change from the Q2 outlook.
The forward-looking developments are generally constructive:
- **American placement:** A six-year agreement puts five idle E170s into American service starting in December, cutting unallocated aircraft from eight to three.
- **2027 growth:** Management framed 2027 block-hour growth at roughly 3-5%, helped by the new aircraft and better Mesa utilization.
- **Integration progress:** Mesa's operations center moved to Carmel, the FAA accepted the second revision cycle, Mesa maintenance migrated to Republic's systems, and heavy-check turnaround times are about 40% lower year over year. Integration is expected to finish in the first half of 2028.
- **Balance sheet:** Operating cash flow was $79.0 million. Adjusted net debt fell to $863.0 million, and leverage dropped to 2.2x from 2.8x a year ago, essentially reaching the year-end target a quarter early.
Bears have legitimate ammunition as well:
- **Pilot labor:** Talks with the pilot unions may go to interest-based arbitration beginning in mid-December and run into 2027.
- **Attrition:** Pilot attrition has normalized after the Spirit liquidation temporarily suppressed it in the first half.
- **Aircraft supply:** E-jet supply-chain constraints still limit aircraft availability.
- **Delta contracts:** Delta's 57 aircraft have contracts expiring on average in 2028, and extension talks remain unresolved.
- **Limited visibility:** Management declined to give 2027 guidance until after a December board review. Only one analyst asked questions on the call, so the outlook received little outside testing.
Market context is thin for this report. Shares opened at $18.98 after the July release, almost exactly on the 200-day moving average of $18.82. That suggests the stock entered this period with no clear technical trend in either direction. Without current price or sentiment readings, it is hard to judge how much of the guidance raise investors had already priced in.
The bottom line is that Republic's third quarter is better as a guidance-and-balance-sheet story than as an earnings story. The Mesa deal is supplying scale, cash flow and faster deleveraging, and management has twice raised its profit outlook. Margins, however, are flat year over year, the quarter softened sequentially, and the new guidance implies a lighter fourth quarter. The investment case now depends less on near-term earnings momentum than on three things: finishing the integration cleanly, getting through pilot negotiations, and securing the Delta extensions that would underpin 2027 and beyond.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-08 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 | |
| Jul-19 | |
| Jul-19 | |
| Jul-14 | |
| May-05 | |
| Apr-30 | |
| Apr-29 | |
| Apr-28 | |
| Apr-17 |
