Belden's Orders Top $1 Billion As AI Data Center Story Grows, But Ruckus Supply Shortfall Breaks The Beat-And-Raise Streak
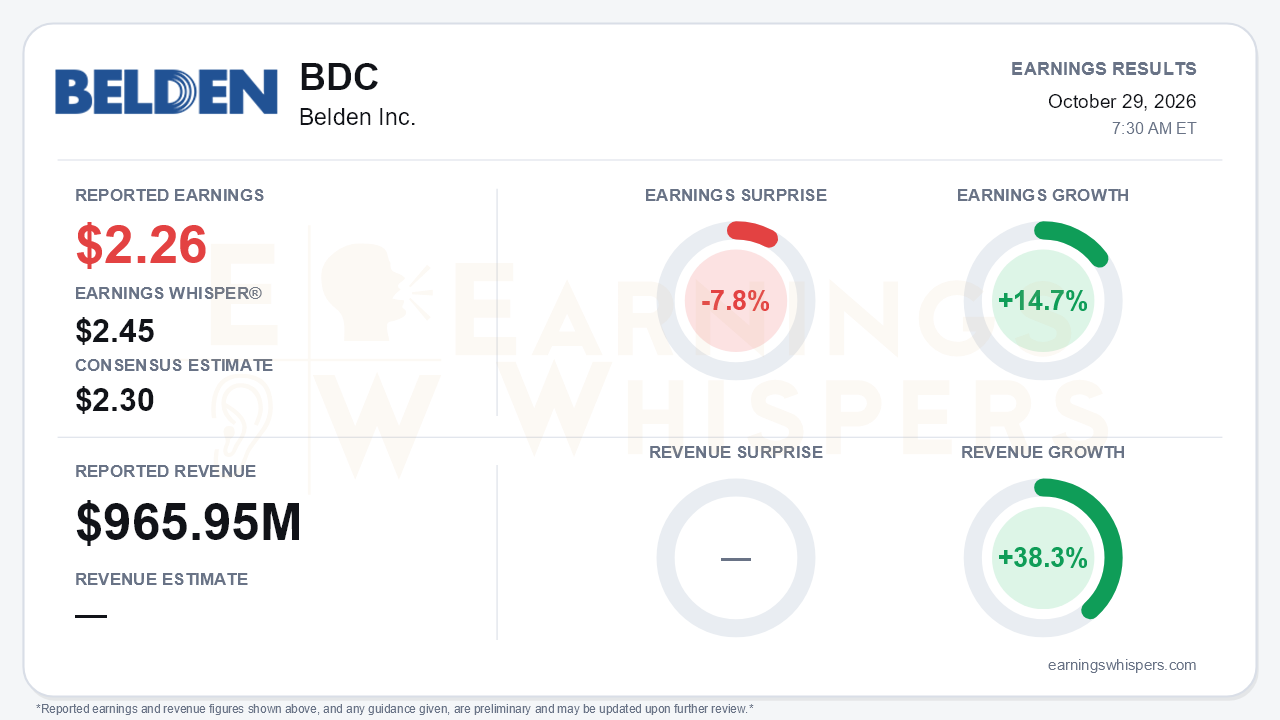
Belden (NYSE: BDC) delivered a quarter in which the long-term story improved while the near-term earnings cadence weakened. Adjusted EPS of $2.26 rose 14.7% year over year on record revenue of $965.95 million, up 38.3%. Earnings still fell short of the $2.30 consensus and well short of the $2.45 Earnings Whisper number, a 7.8% miss. Orders, organic growth and the data center pipeline all accelerated. But chipset shortages at the newly acquired Ruckus business pushed results into the middle of guidance after three straight quarters above the high end. That is the central tension: demand is outrunning Belden's ability to convert it into earnings, at least for now.
The headline growth rates need unpacking. Of the 38% revenue increase, 24 points came from acquisitions and 3 from copper pass-through pricing. That still left 11% organic growth, a clear acceleration from 8% in Q2, 7% in Q1 and 5% in Q4 FY25. The more sobering comparison is that adjusted EPS grew less than half as fast as revenue. The Ruckus deal was largely debt-financed: long-term debt rose to about $3.0 billion from $1.3 billion at year-end, and quarterly net interest expense jumped to $41.8 million from $11.6 million. On a GAAP basis, Belden swung to a loss of $0.29 per share from a $1.41 profit a year ago. The loss was driven by $100 million of non-cash purchase accounting charges for intangible amortization and inventory step-up. Those charges are legitimately non-operating, but the higher interest burden is not, and it will weigh on per-share leverage until net leverage falls from 3.9x toward the roughly 3.6x targeted by year-end.
Margins were mixed. Adjusted gross margin expanded to 41.5% from 39.6% in Q2, reflecting Ruckus's richer mix. Adjusted EBITDA margin, however, was 17.7%, below Q2's 19.5%, which included a tariff benefit, and only modestly above the roughly 17.5% ex-tariff level. Core incremental margins also slipped to above 25% from above 30% in Q2. The Ruckus shortfall explains much of this. Ruckus revenue fell 6% to $168 million against the high-single-digit growth management had framed last quarter, leaving an estimated $10-15 million of high-margin revenue unshipped. Supply relief is expected only in phases into 2027.
The demand evidence was the strongest Belden has shown:
- **Orders.** Orders exceeded $1 billion for the first time, up 46% reported and 16% organically, versus $836 million in Q2. Automation and smart buildings orders each grew about 30%.
- **Data center.** A $100 million 2027 fiber assembly agreement with a major hyperscaler, fulfilled through Wesco, expands a $20 million Q2 order. It lifts expected 2027 data center revenue to about $275 million from a $175 million run rate. Management now expects the data center business to grow more than 50% next year, a notable shift for a unit described as under 5% of sales at the end of FY25.
- **Ruckus demand.** Ruckus orders rose 10% with a 1.09 book-to-bill. Management said the Wi-Fi 7 transition is running 6-9 months ahead of expectations.
- **Grayspace switching.** Belden won new grayspace specifications in Europe and APAC, and existing hyperscaler industrial switch orders are running about 50% above initial estimates.
There are offsets. Consolidated book-to-bill eased to 1.05 from 1.11, and management flagged rising input costs and a tighter supply chain.
That caution shows up in the outlook. Q4 guidance of $960-980 million in revenue and $2.20-2.35 in adjusted EPS implies a roughly flat sequential quarter, with the midpoint below Q2's $2.34, despite record backlog entering the period. The message is that supply, not demand, is the binding constraint. Bears have legitimate ammunition here: a company booking orders 16% above last year organically is guiding to no sequential earnings progress while carrying elevated debt and absorbing cost inflation.
The market had already priced in some of that disappointment. As of the day before the report, shares at $106.66 were down 4.6% from the open following the July report. They sat 24% below the August 11 inter-earnings high of $140.25 and 9.8% below the 200-day moving average of $118.24. The stock was only 5.6% above its October 15 low, so it entered earnings near the bottom of its quarterly range. Investor sentiment improved slightly, from -0.07 to -0.03, but remains marginally negative. That suggests modest stabilization rather than renewed conviction. Price and AVWAP trend readings remain negative, consistent with a stock that has been sold down since its summer spike.
The bottom line is that Belden's demand picture, data center visibility and organic growth trajectory all strengthened meaningfully this quarter. Execution, however, slipped from beat-and-raise to in-line. Investors weighing the stock now face a timing question rather than a demand question: how quickly Ruckus component supply recovers, and whether cost inflation and interest expense let the record order book translate into per-share earnings growth in 2027.
Read our earnings preview for Belden Inc.: https://www.earningswhispers.com/article/BDC/21036
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-21 | |
| Oct-15 | |
| Oct-08 | |
| Oct-01 | |
| Sep-29 | |
| Sep-28 | |
| Sep-24 | |
| Sep-23 | |
| Sep-08 | |
| Aug-27 | |
| Aug-17 |
