ProFrac's Promised Second-Half Pricing Lift Meets A Street Bracing For Lower Revenue
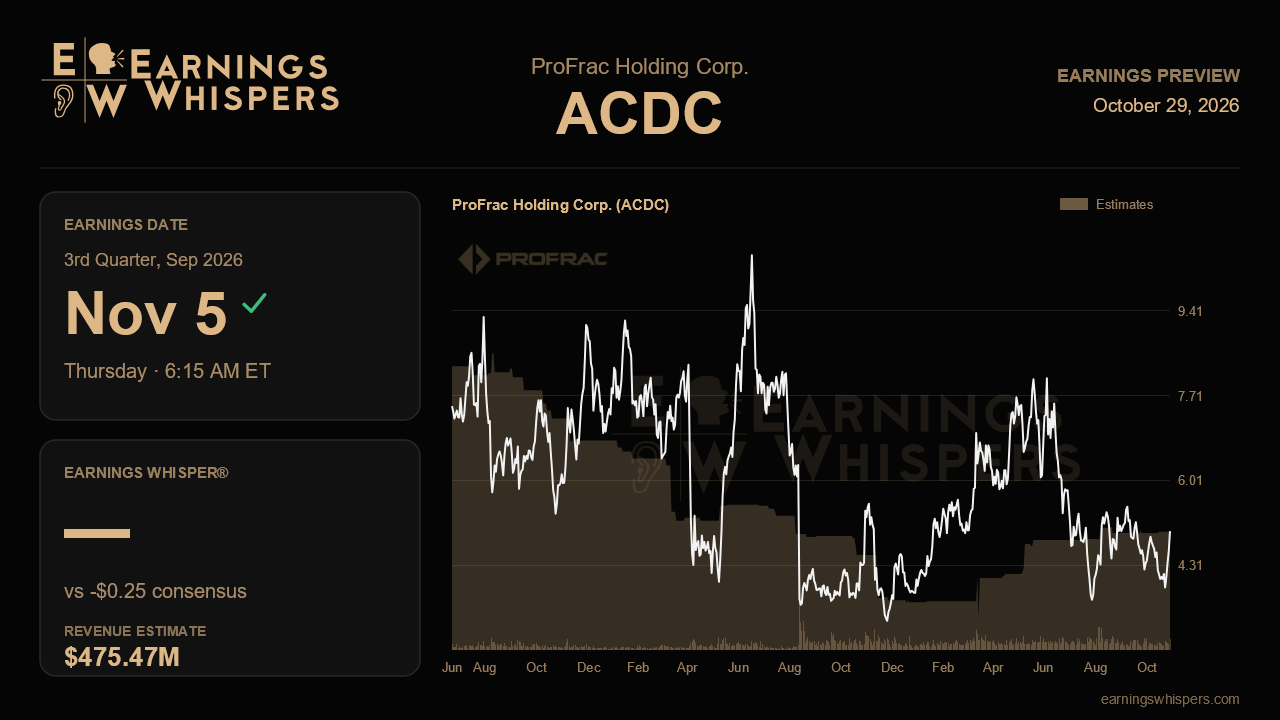
ProFrac heads into its third-quarter report with an unusual disconnect. Last quarter, management said the bulk of its secured price increases would layer in during the third and fourth quarters and that the second half should outshine the first. Wall Street, however, is modeling revenue of about $475.5 million, below the $498.1 million the company just posted. Either analysts are building in caution the company did not voice, or the pricing story is less immediate than it sounded. Thursday's release, due before the open on November 5, should show which.
The consensus calls for a loss of $0.25 a share, a sharp improvement from the $0.44 loss in the second quarter and the $0.60 loss a year earlier. Revenue would be up roughly 18% from the $403.1 million trough of last year's third quarter, which management treats as the bottom of the cycle. So the Street expects a narrower loss on lower sales. That combination only works if margins expand, which makes profitability per fleet, not the top line, the real test. No updated guidance has been issued beyond the reiterated 2026 capital spending range of $155 million to $185 million, so investors have little to anchor on besides the tone of the last call.
That tone was the most confident in a year. Executive Chairman Matt Wilks, who has since also taken the CEO role after Ladd Wilks stepped down in August, compared the setup to early 2022. He pointed to operators earning far better netbacks than their oil budgets assumed, an early start to 2027 contract bidding, and a high-spec, fuel-efficient fleet market with essentially no idle capacity left. Validation would come from stimulation services margins climbing above the 9% posted in the second quarter as renegotiated pricing kicks in, alongside commentary that 2027 bids are landing at firmer rates and longer commitments. Progress on engine upgrades, the eBlender rollout targeted for the full fleet by year-end, and early commercial terms for the Machina closed-loop frac offering would add substance to the narrative.
The risks are equally specific. Pumping hours per fleet cooled in May and June because of more calendar white space than expected, and if that persisted into the summer, it would help explain the Street's softer revenue view. The Alpine sand business earned just $6 million in each of the past two quarters, well below its $16 million showing late last year, amid competitive pricing in West Texas. Flowtech, which nearly doubled its EBITDA last quarter, has to prove that was not a one-off. Then there is the balance sheet: liquidity shrank to roughly $72 million with only $19 million of cash, and borrowings on the credit line rose. Free cash flow, negative $8 million last quarter, needs to turn positive to quiet concerns that the recovery is being financed with debt.
The market has already leaned in. Shares have gained 39% since the last report while the S&P 500 barely moved, and sentiment has improved from clearly bearish to nearly neutral. Yet at $4.99 the stock remains below its 200-day moving average of $5.55 and short of its post-earnings high of $5.68, still far beneath the prior quarter's $8.22 peak. Investors have bought the recovery thesis, but not enough to price in a full upcycle.
The central question is whether pricing gains are now visible in the numbers. If stimulation margins expand, cash flow turns positive, and management confirms that 2027 contracting is tightening, the Street's conservative revenue figure will look stale and the early 2022 comparison will gain credibility. If margins stall and liquidity tightens further, the optimism of the last call will start to look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Aug-06 | |
| Aug-05 | |
| Jul-30 | |
| Jul-06 | |
| May-07 | |
| Apr-30 | |
| Mar-12 | |
| Mar-12 | |
| Mar-12 | |
| Mar-11 | |
| Mar-02 | |
| Feb-26 | |
| Feb-24 |
