ProFrac Beats On Revenue, But An EBITDA Stumble And Proppant Collapse Push The Profit Story Into 2027
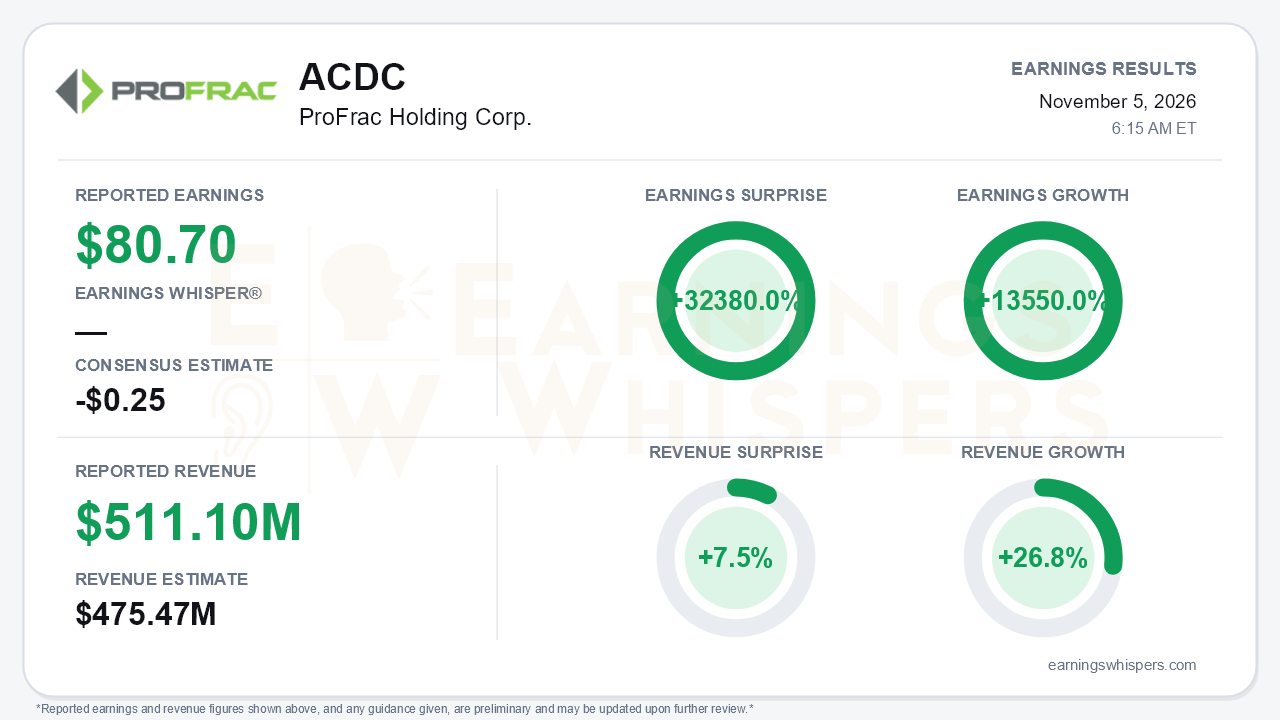
ProFrac Holding Corp. (NASDAQ: ACDC) delivered a quarter in which the top line outran expectations while profitability moved the wrong way. Revenue of $511.1 million beat the $475.47 million consensus by 7.5% and grew 26.8% year over year. It also rose from $498 million in the second quarter and about $450 million in the first. The headline EPS comparison needs a caveat. Earnings Whispers' normalized data shows reported earnings of $80.70 per share against a -$0.25 consensus, a 32,380.0% surprise and 13,550.0% year-over-year growth. The press release, however, reports a net loss attributable to ProFrac of $80.7 million and a consolidated net loss of $74.0 million. Those two sources conflict, and the release does not describe a profitable quarter. The EPS 'beat' should not be read as a swing to profitability. What the release does show is a loss that has narrowed from $92.4 million a year ago but was essentially flat with the second quarter's $74.7 million.
The quality of the quarter deserves scrutiny, because the revenue strength did not reach earnings. Adjusted EBITDA slipped to $65 million, or 13% of revenue, from $69 million and 14% in the second quarter. That breaks the sequential improvement streak. It also lands well below the mid-to-high $70 million consensus referenced on the prior call, where management had said third-quarter results would fully reflect July price increases and that any surprise would be to the upside. Stimulation Services, the core business, saw revenue dip to $421 million from $430 million and EBITDA ease to $37 million from $39 million. Unanticipated September white space, partly a byproduct of simul-frac efficiency, cut pump hours, while materials, maintenance and labor inflation absorbed single-digit price gains. Proppant was the real damage. Segment revenue fell to $101 million from $121 million, and EBITDA collapsed to $2.4 million, a 2.4% margin, from $6 million and 5.2%. Brutal West Texas pricing competition and lower throughput drove the decline, against $16 million of segment EBITDA in the fourth quarter of 2025.
There were genuine bright spots. Flotek continued its climb to $117 million of revenue and $22 million of EBITDA, up from $102 million and $19 million. Manufacturing revenue rose to $53 million on new power-generation packaging and third-party rebuild work. Most notably, free cash flow turned positive at $14 million, versus negative $8 million in the second quarter and negative $25 million in the first. Operating cash flow more than doubled to $51 million, helped by a $17 million working-capital inflow. That inflow suggests part of the improvement may not repeat.
Management leaned hard on the 2027 setup. It described a frac market tightening on limited capacity, especially gas-capable equipment, with leading-edge pricing recovered roughly 50-60% off the trough. Management also said 2027 RFPs are accelerating and operators are discussing contracted new-build gas fleets with multi-year terms and upfront commitments. October activity improved, and fourth-quarter seasonality is expected to be lighter than usual, with both Stimulation and Proppant guided to improve sequentially. The risks are just as concrete. Management expects inflation in logistics, consumables and skilled labor to persist into 2027. Lengthening engine lead times are slowing upgrades and pushing some eBlender deployments into 2027. The CEO now expects positive net income in 2027, a timeline that has drifted from the 'very short order this year' framing on the first-quarter call.
The balance sheet remains the overhang. Principal debt sits near $1.05 billion against $97 million of liquidity, though liquidity is up from $72 million and ABL borrowings fell to $148 million. The Alpine term loan amendment extends maturity to February 2030 and halts amortization until 2028. A Flotek share exchange retired $60 million of affiliate-held debt. Still, the option to pay interest in kind, the excess cash flow sweep and contemplated non-core asset sales signal that cash remains tight. Bears have legitimate ammunition here.
Investor sentiment moved from modestly negative (-0.17) to roughly neutral ahead of the report. Shares have risen 10.6% since the open after the August report, to $3.97. That gain masks a round trip: the stock spiked to $5.68 in early September, then gave back most of it. Shares now sit 30% below that high and 28.5% below the 200-day moving average. The trend readings are mixed, with momentum and AVWAP positive but the price trend still negative.
The bottom line is that ProFrac's revenue beat and first positive free cash flow of the year are real, but the quarter missed its own EBITDA ambitions, proppant economics deteriorated sharply, and the profitability timeline slipped again. The 2027 tight-market pricing thesis is credible and well articulated. For now, though, it remains a forecast layered on a heavily levered balance sheet, and the stock's retreat from its September high shows investors are waiting for proof.
Read our earnings preview for ProFrac Holding Corp.: https://www.earningswhispers.com/article/ACDC/22446
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-29 | |
| Oct-29 | |
| Aug-06 | |
| Aug-05 | |
| Jul-30 | |
| Jul-06 | |
| May-07 | |
| Apr-30 | |
| Mar-12 | |
| Mar-12 | |
| Mar-12 | |
| Mar-11 | |
| Mar-02 |
