ElectroCore Needs An 18% Sequential Jump To Prove Its Sales Overhaul Is Working
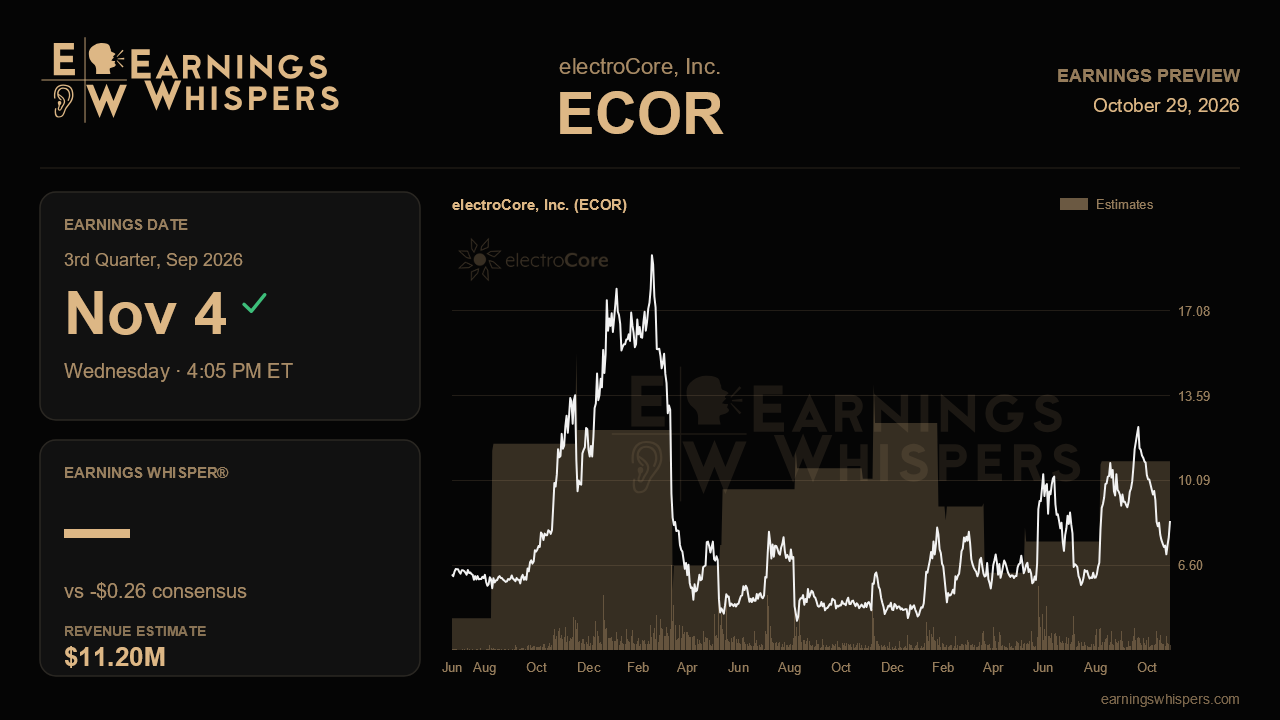
electroCore heads into its third-quarter report with a raised full-year outlook built on a flat base. Last quarter, management lifted its 2026 growth target to more than 30% and named the third quarter of 2027 as the point it expects adjusted EBITDA to turn positive. It did so even though revenue had stalled at $9.5 million, slightly below the prior quarter's record. This report is the first real test of whether that confidence was earned or borrowed against the back half of the year.
The Street is asking for a lot. Consensus calls for revenue of $11.2 million, up about 29% from $8.7 million a year ago. More tellingly, that is roughly 18% above the second quarter's total. The expected loss of $0.26 per share would mark a solid improvement from $0.40 a year earlier and $0.33 last quarter. Full-year consensus of $41.9 million sits just above the roughly $41.6 million figure management now says it will exceed, so analysts are aligned with guidance rather than leaning past it. The math is still demanding. With about $19.1 million booked in the first half, the company needs close to $22.8 million in the second, implying a fourth quarter near $11.6 million if the third lands on target.
The swing factor is the core prescription gammaCore business sold largely through the Veterans Affairs system. That franchise grew only 11% last quarter, down from 26% in the first quarter, and slipped about 4% sequentially. Management blamed disruption from a commercial reorganization and said roughly $145,000 of VA orders slid into the third quarter because of a prosthetics staffing backlog. That recovered revenue helps, but it covers only a small slice of the gap. The bigger proof has to come from the rebuilt sales effort, which doubled sales regions and added 17 contract reps covering 29 VA medical centers. Early signs that matter include a resumption in new VA facility additions, which paused last quarter, and continued gains in patient penetration beyond the 16,400 veterans reached in the second quarter. Progress toward the targeted 30% improvement in refill rates would also count. Heavy reliance on the top 15 VA accounts, which made up more than half of VA revenue, makes broadening that base important.
Quell, the pain-relief line acquired in 2025, is the other leg of the growth story after reaching $1.3 million last quarter. Another sequential step up would reassure, though the FDA inspection observations that delayed the Quell 2.0 over-the-counter relaunch could cap near-term gains. Any update on resolving those findings, and on the planned year-end submission for chemotherapy-induced neuropathy, will shape how much optionality investors assign the product. On the consumer side, TrueVega's advertising efficiency fell as rival bidders crowded branded search and pushed click costs up about 30%. Further erosion would pressure both growth and the gross margin, which eased to 86.5%.
Expectations have warmed noticeably. Sentiment remains modestly bearish but is far less negative than heading into the last report. The shares have gained nearly 26% since then, while the S&P 500 was essentially flat. At $8.42, the stock trades above its 200-day average, yet well below its post-earnings peak of $12.70. That suggests some of the early enthusiasm has already been tested and partly unwound.
With cash down to about $10 million and the breakeven plan premised on avoiding a dilutive raise, a narrowing adjusted EBITDA loss is nearly as important as the top line. Ultimately, though, the narrative hinges on one question. Does the sales reorganization start converting into gammaCore prescription growth this quarter? A clear reacceleration would validate the raised outlook. Another flat print would leave the full-year target resting almost entirely on the fourth quarter.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Sep-10 | |
| Sep-09 | |
| Aug-25 | |
| Aug-06 | |
| Aug-03 | |
| Jul-30 | |
| Jul-16 | |
| Jun-17 | |
| Jun-09 | |
| Jun-02 |
