ElectroCore Halves Its Loss And Beats On EPS, But A Revenue Miss, Slowing Growth And A Guidance Cut Push The Story Into 2027
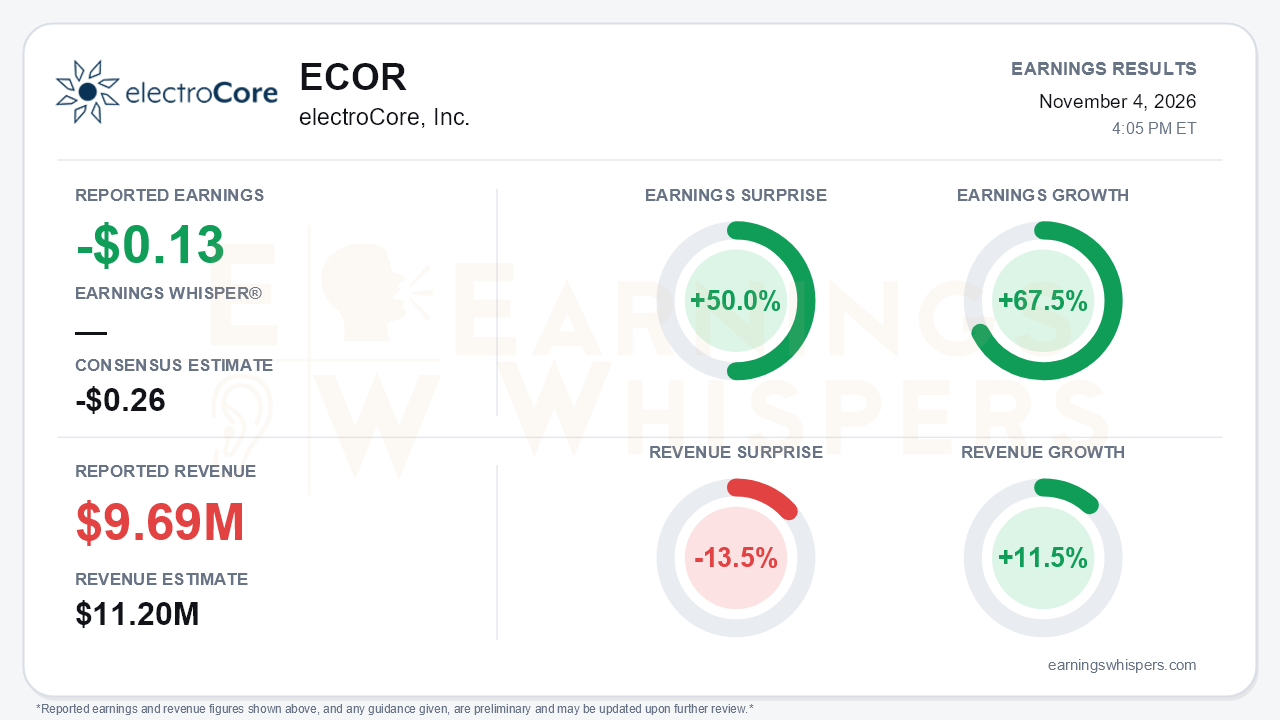
electroCore delivered the most profitable quarter in its history and still gave investors reasons to worry. The bioelectronics company reported a third-quarter loss of $0.13 per share, beating the -$0.26 consensus by 50.0% and improving 67.5% from a year ago. Revenue of $9.69 million set a quarterly record but fell 13.5% short of the $11.2 million consensus, and year-over-year growth slowed to 11.5%. The company also cut its full-year 2026 outlook. That is the central tension: cost discipline is visibly working, while the top line, the part of the story investors were paying for, is slipping.
The bottom-line improvement is mostly real, though it needs some scrutiny. Gross margin expanded to 88.5% from 86.0% a year ago on a more favorable mix. Total operating expenses fell to $10.1 million from $10.4 million, cutting the operating loss to $1.56 million from $2.88 million. The GAAP net loss of $1.3 million, however, also included about $0.4 million from an indemnification settlement gain and a $0.1 million UK tax benefit. Without those items, the headline loss would have looked meaningfully less flattering. The Adjusted EBITDA loss narrowed to $0.7 million from $2.0 million, and stock-based compensation, which this measure excludes, rose to $0.6 million. The weighted share count also climbed to roughly 10.0 million from 8.4 million, a reminder that dilution is part of how this company funds itself.
Beneath the record revenue, growth momentum has faded quickly. Year-over-year growth has decelerated from 43% in the first quarter to 28% in the second and roughly 12% now. Sequential revenue has been essentially flat at $9.6 million, $9.5 million and $9.7 million. The prescription business is still doing the heavy lifting. U.S. Rx sales rose about 25% to $7.95 million, VA new patient orders grew 21%, refill revenue hit a record, and Quell sales doubled to $1.2 million. Offsetting that, General Wellness revenue dropped to $1.04 million from $1.69 million. Management deliberately pulled back on low-return Truvaga spending as branded-search competition and ad costs rose sharply. Return on ad spend improved 8%, but the company is trading consumer volume for efficiency.
Management's case for a reacceleration rests on the rebuilt sales organization. Newly added independent reps are averaging about $210,000 a month in VA revenue, compared with a $160,000 baseline for those territories, and management said they were trending toward roughly $300,000 in October. New patient starts per account have jumped, top-15 account concentration eased to 51% from 54%, and Quell had its best month ever in October. The Lovell distribution shift reached about 91% of VA orders and should trim transaction fees. Still, management attributed the guidance cut to a slower-than-planned sales reorganization. Revenue guidance has moved from "greater than 30% growth" to $39 million to $42 million. With $28.7 million booked through nine months, the range implies a fourth-quarter step-up to roughly $10 million to $13 million, a level the company has not yet demonstrated. The Adjusted EBITDA breakeven target also slipped from the third quarter of 2027 to "by the end of 2027."
The forward catalysts are real but back-end loaded. Preliminary 2027 guidance calls for 30% to 40% growth. The CIPN 510(k) for Quell, which carries Breakthrough designation, is excluded from that outlook, and an FDA response is not expected before late first quarter 2027. Bears have legitimate ammunition on the balance sheet. Cash and securities fell to $7.5 million from about $10 million in the second quarter as inventory built. Stockholders' deficit stands at $2.5 million, and the company is exploring a term-loan refinancing. Its risk disclosures reference going-concern and capital-raising uncertainty. In addition, an open FDA Form 483 continues to delay the Quell OTC relaunch, and the national refill rate of 42% remains well short of the 70% goal.
Investor sentiment entered the report noticeably better than it was last quarter. It swung from clearly negative (-0.35) to roughly neutral (+0.04), suggesting expectations had partially reset toward the turnaround narrative before the guidance cut landed. Price action has been volatile. Shares spiked to a 52-week high of $12.70 in late September but have since given back most of that move. At $7.23, the stock was up only 7.9% from the open after the August report, 6.6% below its 200-day moving average and about 43% below the September peak. The Earnings Whispers trend readings lean positive on sequential growth and momentum, but AVWAP remains negative, consistent with buyers who chased the spike now sitting on losses.
The bottom line is that electroCore proved it can shrink losses, but not yet that it can reaccelerate revenue. The EPS beat and record margins show the cost structure is improving. Against that, the revenue miss, three straight quarters of decelerating growth, a lowered 2026 outlook and a delayed breakeven target shift the burden of proof into 2027, and the company has a thin cash cushion to get there. The rep productivity data is the most encouraging evidence on the table, and the fourth quarter will show whether it translates into the sequential step-up the guidance requires.
Read our earnings preview for electroCore, Inc.: https://www.earningswhispers.com/article/ECOR/22445
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 8 hours | |
| Nov-04 | |
| Nov-04 | |
| Oct-29 | |
| Oct-29 | |
| Oct-28 | |
| Oct-27 | |
| Oct-21 | |
| Sep-10 | |
| Sep-09 | |
| Aug-25 | |
| Aug-06 | |
| Aug-03 | |
| Jul-30 | |
| Jul-16 |
