Eton's First Full Hemangiol Quarter Tests Whether A $145 Million Guide Was Conservative
Eton Pharmaceuticals heads into its third-quarter report with the kind of problem many small drugmakers would envy: management has raised its 2026 revenue outlook twice in two quarters, and the stock has still drifted lower since the last update. The September quarter is the first to include a full three months of Hemangiol, the infantile hemangioma treatment Eton relaunched on May 1 that already became its largest product. That makes this report the cleanest read yet on whether the company's sharp acceleration is durable or was flattered by a one-time patient migration.
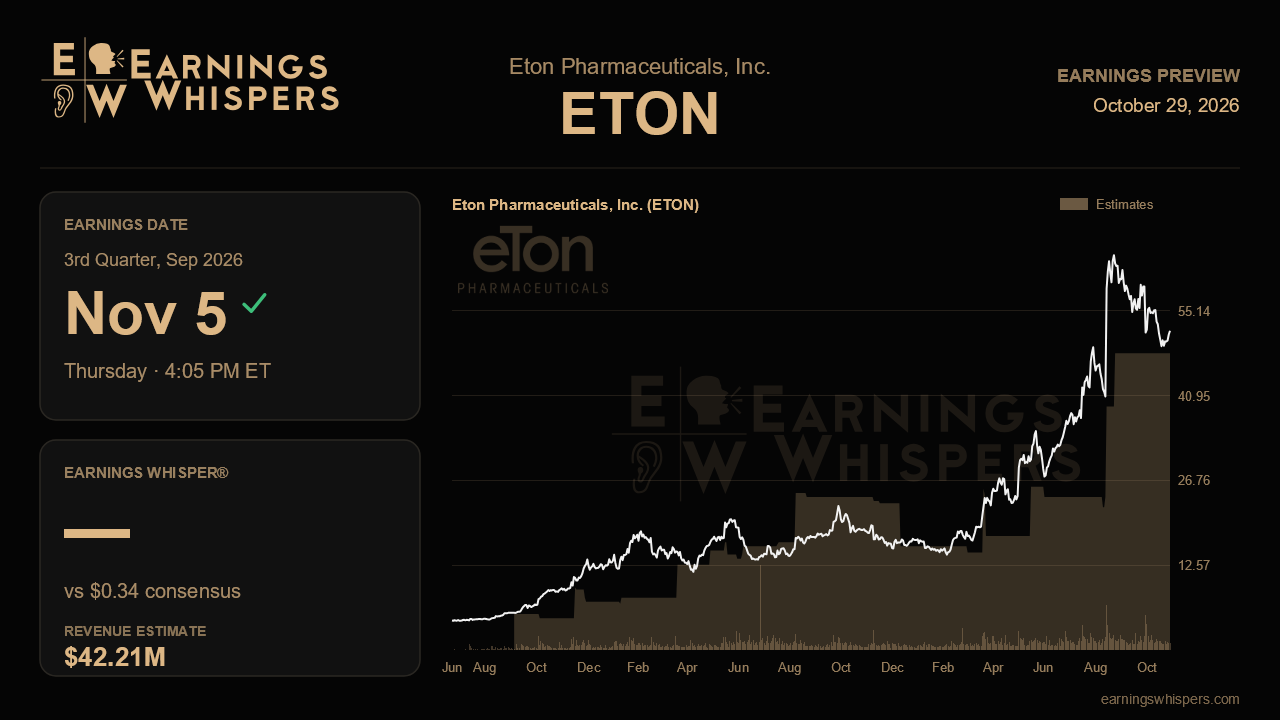
Wall Street is looking for earnings of $0.34 per share on revenue of $42.2 million. Revenue would be up nearly 88% from $22.5 million a year ago and about 12% above the $37.6 million posted in the June quarter, while EPS would swing sharply from a loss of $0.07 a year earlier. The more telling detail is that the EPS estimate sits slightly below last quarter's $0.35 even as revenue is expected to climb. That gap reflects higher planned research spending. Management lifted full-year R&D guidance to $10 million to $14 million to cover the ASN-001 licensing upfront payment and its bridging study, so a flat bottom line on rising sales would not by itself signal a problem.
Guidance is where the expectations bar gets interesting. Eton now expects 2026 revenue above $145 million, up from above $120 million, which itself was lifted from above $110 million. The full-year consensus of roughly $120.2 million still trails that outlook by a wide margin, suggesting many estimates have not fully caught up. A quarter near $42 million would keep the company on pace for its guide, but given the cadence of raises, another increase may be what the market treats as the real test. On profitability, the adjusted EBITDA margin guide of above 35% looks cautious next to the 43% Eton delivered in the second quarter. Holding margins in the high 30s or better while absorbing heavier R&D would confirm that operating leverage is structural rather than a product of a single strong quarter.
Several operating details should determine how the narrative holds up. For Hemangiol, the question is whether growth extends beyond the converted base, since management has said further gains depend on capturing off-label patients, and the net price per course is still an estimate in the $8,000 to $10,000 range. Gross margin, which slipped to 73% from 75% a year earlier, remains vulnerable to lumpy, negative-margin international Increlex sales. The adrenal franchise, which management said had more than 600 active patients, offers a read on steady base demand. Impavito began US distribution only in late September, so meaningful contribution is unlikely yet. One wild card is the roughly $22 million valuation allowance: if Eton has exited its cumulative-loss position, a release could distort GAAP earnings in a way that says little about operations. Pipeline updates on the Increlex harmonization study, the ET-700 pilot, the Kindivi label expansion and the ASN-001 bridging study will round out the picture.
Sentiment has warmed noticeably, moving to a moderately bullish reading from a slightly bearish one ahead of the prior report. The stock tells a more restrained story. Shares are down about 5.7% since the last release, trailing the S&P 500 by roughly five points, and at $51.80 they sit much closer to the post-earnings low of $48.36 than the $66.37 high. Still, the stock remains well above its 200-day moving average near $35 and above the top of the prior quarter's range, so the pullback looks like a consolidation of a big move rather than a rejection of the story.
The central issue is whether Hemangiol's first full quarter shows continued growth on top of a strong base while margins hold up despite rising investment. If Eton tracks comfortably toward or above $145 million and sounds confident about its targets, the recent pullback could look like an overreaction. A sequential stall or margin slippage would suggest the second quarter was the high-water mark rather than the new baseline.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| 14 hours | |
| Oct-14 | |
| Sep-28 | |
| Aug-27 | |
| Aug-21 | |
| Aug-14 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-05 | |
| Aug-03 | |
| Jul-29 | |
| Jul-28 | |
| Jul-17 |
