Eton Pharmaceuticals Crushes Estimates And Raises Guidance Again, But A Tax Benefit Inflates The GAAP Beat
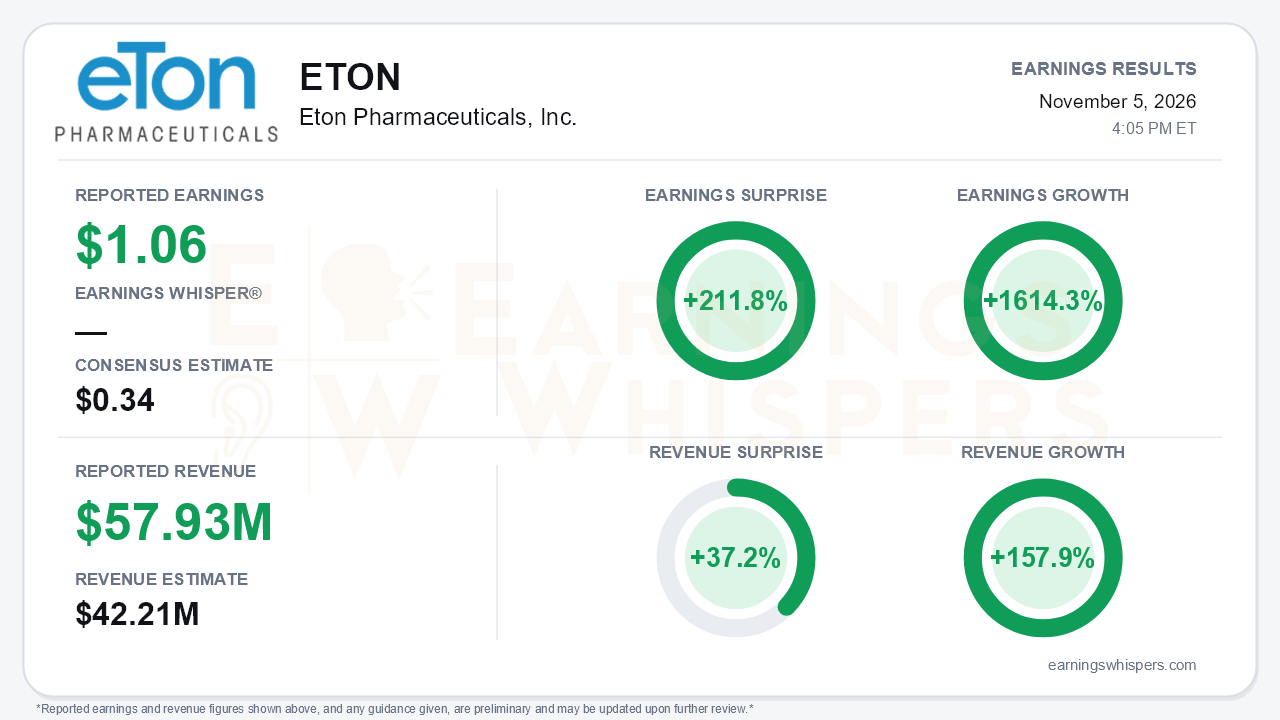
Eton Pharmaceuticals delivered one of its cleanest operating quarters to date, though the headline number needs unpacking. The rare-disease company reported third-quarter GAAP earnings of $1.06 per share on revenue of $57.93 million. That beat the $0.34 consensus by 211.8% and the $42.21 million revenue estimate by 37.2%. Earnings grew 1614.3% year over year, a swing from a $0.07 loss in the prior-year quarter, while revenue grew 157.9%. Management also raised 2026 revenue guidance to more than $175 million from more than $145 million and lifted its adjusted EBITDA margin target to above 40% from above 35%. It was the third straight quarterly increase in both.
The quality of the EPS beat deserves scrutiny. Roughly $12.9 million of the $35.2 million in GAAP net income came from releasing the valuation allowance on federal and some state deferred tax assets. That is a one-time benefit, not operating performance. Strip it out, and non-GAAP EPS was $0.50. Even that figure clears the consensus by a wide margin, so the beat is real, but the GAAP surprise percentage overstates it. Underneath the accounting, the operating story is genuinely strong:
- Adjusted gross margin reached 80%, up from 45% a year ago and 73% in the second quarter.
- Adjusted EBITDA was $28.5 million, a 49% margin, versus 43% in Q2 and 24% in Q1.
- Operating income was $23.0 million, compared with a $1.4 million loss a year earlier.
Much of this reflects mix and operating leverage, with HEMANGEOL contributing its first full quarter at a net price at or slightly above the top of the $8,000-$10,000 range.
The trajectory matters more than any single quarter. Revenue climbed from $24.3 million in Q1 to $37.6 million in Q2 and then $57.9 million in Q3, so growth accelerated sharply through the year. Part of that step-up is acquisition-driven, since HEMANGEOL was not in the base a year ago. Still, management reported record active patient counts for every key promoted product: INCRELEX, ALKINDI SPRINKLE, KHINDIVI, GALZIN, DESMODA and HEMANGEOL. That points to organic volume growth, not just bolt-on revenue. Eton passed its $200 million annualized run-rate goal five quarters early and signaled that its $500 million 2030 target could be reached sooner. Its 50% adjusted EBITDA margin goal for 2028 is essentially already in hand.
The guidance carries some nuance:
- **Implied Q4.** With $119.8 million booked through nine months, the new full-year floor implies fourth-quarter revenue of only about $55 million, slightly below Q3. That looks conservative.
- **Gross margin.** The press release calls for full-year adjusted gross margin above 70%, while the call pointed to roughly 75%.
- **Q4 costs.** A one-time $4 million ALKINDI milestone will run through fourth-quarter cost of sales, and management warned that EBITDA margins may fluctuate with R&D timing.
- **Spending.** G&A rose 98% year over year on stock compensation, headcount and the loss of the orphan-drug FDA fee exemption.
The pipeline broadened but also took its first visible setback. The new catalysts are substantial:
- LIBERVANT, a buccal diazepam film, has a March 29, 2027 PDUFA date and targets an April 2027 launch into a U.S. seizure-rescue market estimated above $450 million.
- KHINDIVI's label expansion has a May 28, 2027 PDUFA date.
- The Glyburide Oral Suspension NDA is expected around year-end.
- ASN-001, which management believes could become its largest product, enters bioavailability dosing in January.
- The INCRELEX harmonization study could expand the addressable U.S. population from about 200 to 1,000 patients.
The counterweight is ET-700. It was far better tolerated than GALZIN (1 of 12 versus 8 of 12 treatment-related adverse events) but cut hepatic copper uptake by only 12%, versus 46% for GALZIN. The planned early-2027 pivotal start now gives way to reformulation arms around the third quarter of 2027. LIBERVANT also requires final FDA approval, exclusivity resolution and a new dedicated sales force. The new ET-900 spasms program is earlier-stage than Eton's usual approach.
The market setup is more complicated than the surprise implies. Investor sentiment moved from slightly negative (-0.04) to modestly positive (0.20) heading into the report, a meaningful improvement but hardly euphoric. The stock had been sliding even as fundamentals improved. At $50.72 on the eve of earnings, shares were down 7.7% from the open after the August report and 23.6% below the 52-week high of $66.37 set on August 24. They sat just 4.9% above the October low. They remained about 40% above the 200-day moving average, so the longer-term uptrend is intact even as the post-August spike has largely deflated. The negative AVWAP reading reflects that recent distribution, while sequential-growth and momentum readings remain positive.
The bottom line is that Eton's operating results were better than the inflated GAAP figure needed to make them look: accelerating revenue, near-80% gross margins, record cash of $55.6 million and a third consecutive guidance raise. Bears have legitimate ammunition in the one-time tax benefit, the ET-700 delay, rising G&A and a heavy 2027 regulatory calendar. Even so, a stock that entered the print near the bottom of its quarterly range has a fundamental story that now looks stronger than its recent price action.
Read our earnings preview for Eton Pharmaceuticals, Inc.: https://www.earningswhispers.com/article/ETON/22460
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-02 | |
| Oct-29 | |
| Oct-29 | |
| Oct-14 | |
| Sep-28 | |
| Aug-27 | |
| Aug-21 | |
| Aug-14 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 |
