Natera Enters Q3 With Signatera Momentum, Raised Guidance And A Stock Near Record Highs
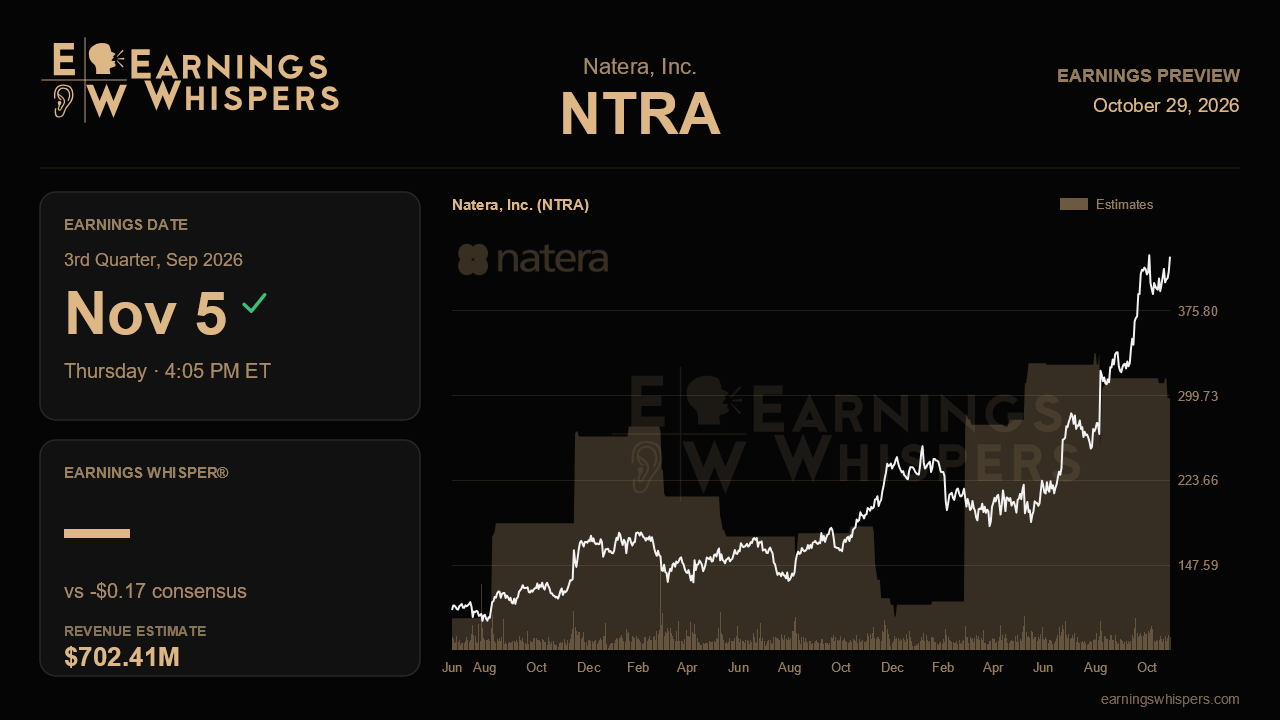
Natera heads into its third-quarter report with an unusual setup: the company just posted its best quarter yet and raised its full-year outlook again, yet the Street's model for the coming quarter looks distinctly cautious. When results arrive after the close on November 5, investors will learn whether that caution is prudent or simply too low a bar for a business that has now raised guidance three times in a row.
Consensus calls for a loss of $0.17 per share on revenue of $702.4 million. That would be an 18.6% increase from the $592.2 million reported a year ago and a sharply narrower loss than the year-ago $0.64. The headline growth rate, however, is a big step down from the roughly 38% pace Natera delivered last quarter. It also implies revenue about $50 million below the $752.8 million booked in the second quarter. Some deceleration in a reported figure is not unusual for a lab company whose results can swing on reimbursement true-ups. Still, the gap between recent momentum and this estimate is wide enough to draw scrutiny.
Guidance puts that estimate in context. Management lifted its 2026 revenue range by $100 million at the midpoint to $2.85 billion to $2.91 billion, following an earlier raise from an initial $2.62 billion to $2.70 billion. First-half revenue totaled about $1.45 billion, so the low end of guidance requires roughly $700 million a quarter for the rest of the year. The quarterly consensus sits right on that floor, while the full-year Street estimate of $2.80 billion actually trails management's low end. Put simply, analysts appear to be modeling below what the company has told them to expect, which leaves room for upside if the business merely holds its recent cadence.
The operational test centers on Signatera, the molecular residual disease test that now drives the story. Units jumped a record 34,000 sequentially to 283,000 last quarter, but management warned that pace would not repeat because weather had depressed first-quarter volumes and flattered the comparison. A healthy outcome would be a gain closer to the prior run rate of roughly 24,000 to 25,000 units, which would show underlying demand intact. Average selling price matters just as much. It has climbed about $25 per quarter to roughly $1,275, and another step up would support the company's growing confidence in its long-term $2,000 target. The larger pricing boost from seven pending Medicare coverage submissions is excluded from 2026 guidance, so any update on timing would be a bonus rather than a requirement. Early signs of traction from the recent wave of regulatory wins, including FDA companion-diagnostic approval in bladder cancer, Japanese approval in colorectal cancer and broad European certification, would further strengthen the narrative.
Margins are the likeliest source of friction. Gross margin held near 65%, but management flagged cost pressure from newly launched products that are not yet optimized, and roughly $100 million of early cancer detection spending this year produces no current revenue. Holding margin near 65% despite those headwinds would validate the operating leverage story. Elsewhere, women's health beat seasonal norms on the improved Panorama launch, and a favorable Medicare decision in organ health should begin helping volumes.
The market has already placed a big bet on continuation. Shares have climbed 32% since the last report against a flat S&P 500, trade far above their 200-day average near $264 and sit within about 3% of their post-earnings high of $437.41. Sentiment has grown modestly less bearish than a quarter ago. With the stock testing a potential breakout, the central question is simple: can Natera show steady Signatera volume, rising pricing and stable margins that make another guidance increase credible? If so, the cautious consensus looks beatable. If volumes or margins slip, a richly priced stock has little cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 11 hours | |
| 15 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-18 | |
| Oct-15 | |
| Oct-13 | |
| Oct-09 | |
| Oct-09 | |
| Oct-09 | |
| Oct-07 | |
| Oct-06 | |
| Oct-05 | |
| Oct-05 |
