Natera Misses On The Bottom Line, But A 13% Revenue Beat, Third Guidance Raise And $6B 2029 Target Dominate The Quarter
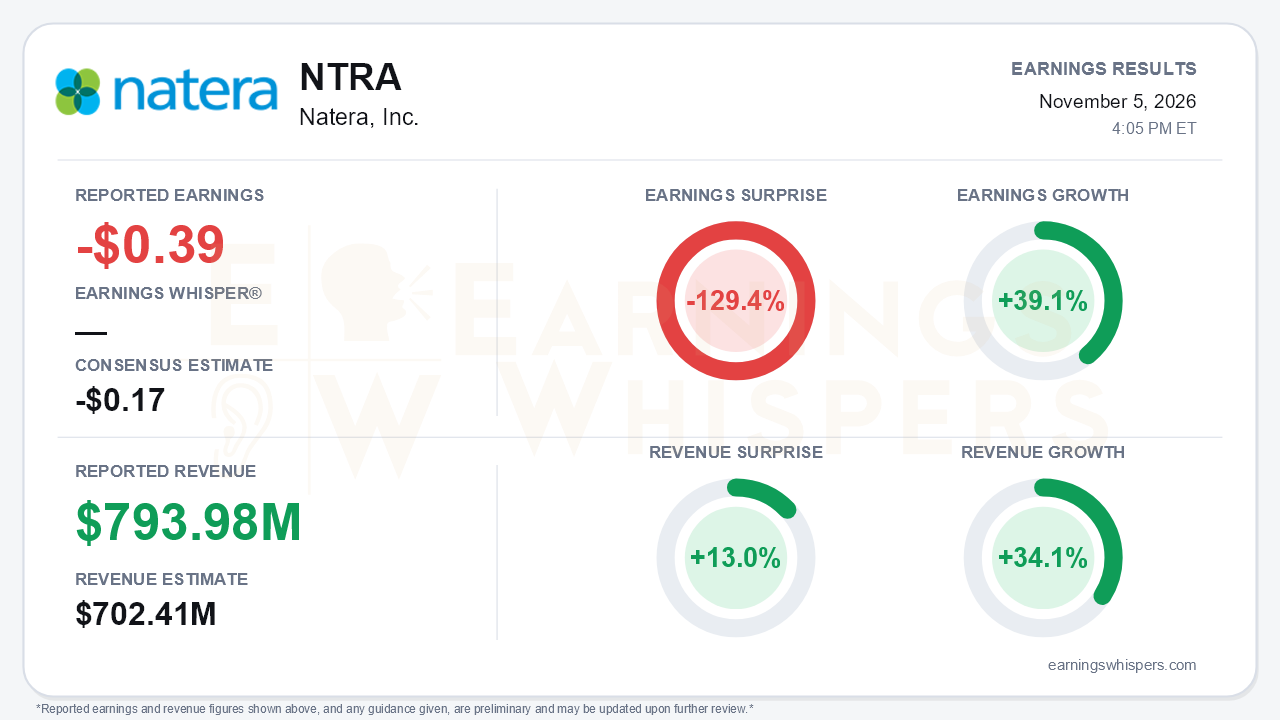
Natera's third quarter is a case where the headline miss tells the least important part of the story. The company reported a loss of $0.39 per share, against a consensus loss of $0.17, missing by 129.4%. Revenue was $793.98 million, beating the $702.41 million consensus by 13.0% and growing 34.1% year over year. The press release shows a GAAP net loss of $0.42 per share, compared with $0.64 a year ago, so the normalized and GAAP figures differ slightly. Either way, the loss narrowed meaningfully, and Earnings Whispers calculates earnings growth of 39.1%. Natera also raised full-year revenue guidance by $140 million at the midpoint to $3.005 billion to $3.035 billion. That is the third straight raise, and guidance now sits roughly $350 million above the initial 2026 outlook. The central tension is that Natera keeps out-running revenue expectations while deliberately spending through the upside, which leaves EPS forecasts exposed even as the franchise strengthens.
The quality of the revenue beat deserves scrutiny, and it largely holds up. Reported growth slowed from 38% in Q2 and 39% in Q1 to 34%. On the surface, that looks like deceleration. The cause, however, is shrinking revenue true-ups:
- Changes in estimates added $32.3 million this quarter, versus $52.3 million in Q2 and $55.1 million a year ago.
- Management says these adjustments are fading as collection history makes initial accruals more accurate.
- Excluding true-ups, growth was roughly 42%, steady to higher than recent quarters.
Reported gross margin of 64.7% looks flat year over year. Stripped of true-ups, however, margin rose about 140 basis points sequentially to 63.2%. In other words, the headline masks a stronger underlying trend: earnings are increasingly built on recurring volume and pricing rather than catch-up collections.
The operating drivers all moved in the right direction:
- **Volume:** Clinical MRD units reached about 316,000, up 33,000 sequentially and 56% year over year. That is notable because management had cautioned on the Q2 call that Q3 would not set a sequential record. Oncology tests processed rose 60.9%, total tests hit a record 1.09 million, and organ health volume grew about 40% with help from a new Medicare surveillance LCD.
- **Pricing:** Signatera ASP climbed to roughly $1,290, up from about $1,275 in Q2 and $1,225 two quarters before that.
- **Biopharma:** MRD revenue through nine months is already up about 70% versus all of 2025.
The call preserved a credible growth story and then extended it. Management introduced a target of $6 billion in revenue by 2029, implying a roughly 25% compound growth rate. It also said that target assumes minimal contribution from cancer screening and that it expects to be profitable by then. Longer-range goals include 70%+ gross margins and a $2,000 Signatera ASP, which management suggested may prove conservative. Near-term catalysts include:
- Medicare coverage for serial Signatera use in early-stage hepatocellular carcinoma, with 9-10 more MolDX submissions in flight.
- Japanese approval in muscle-invasive bladder cancer, with pricing expected around JPM.
- Full enrollment of the FIND CRC screening study, with a 2027 readout.
- FDA Breakthrough designation for the multi-cancer assay.
Bears have legitimate ammunition, though. Operating expenses rose 19.5%, and R&D jumped about 40% year over year to $242.4 million. The top of the SG&A guide moved to $1.3 billion from $1.225 billion, partly on one-time legal costs, and the R&D ceiling rose $25 million. Management also flagged several 2027 pressures:
- Possible COGS pressure if Signatera Genome and Fetal Focus adoption outpaces cost-reduction work.
- A deliberately conservative preliminary 2027 framework: flat unit adds, steady ASPs and a flat margin range.
- Operating expense growth of 10-12% next year.
Cash rose only about $5.7 million in the quarter, while accounts receivable climbed to $471 million from $297 million at year-end. Add a CEO transition to Solomon Moshkevich, competitive consolidation in prenatal testing and new tumor-informed MRD entrants, and the risk list is not trivial.
The market setup is more complicated than the EPS miss implies. Shares closed at $391.03 the day before the report. That is up 21.9% from the open after the August release and about 46% above the 200-day moving average. The stock also sits roughly 10.6% below the 52-week high of $437.41 set on October 6 during this inter-earnings stretch. Investor sentiment remained negative but improved materially, rising from -0.46 to -0.22. Expectations, in short, have been rising alongside price rather than leading it. Earnings Whispers trend signals for price, sequential growth, momentum and AVWAP are positive, consistent with a stock that has been rewarded for execution. The pullback from the October peak, however, shows investors are not paying unconditionally.
The bottom line is that Natera's per-share miss reflects a spending choice, not a demand problem. Volume, ASP and underlying margin all improved, the revenue guide rose again, and the new 2029 target gives the growth story a longer runway. The debate now shifts to whether operating leverage arrives fast enough. With elevated spending, a conservative 2027 framework and leadership change in the mix, the bar for proving that is higher after a 22% run than it was in August.
Read our earnings preview for Natera, Inc.: https://www.earningswhispers.com/article/NTRA/22463
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Oct-18 | |
| Oct-15 | |
| Oct-13 |
