Brookfield Infrastructure's AI Pipeline Faces A Proof Test As The Street Prices Growth Below Target
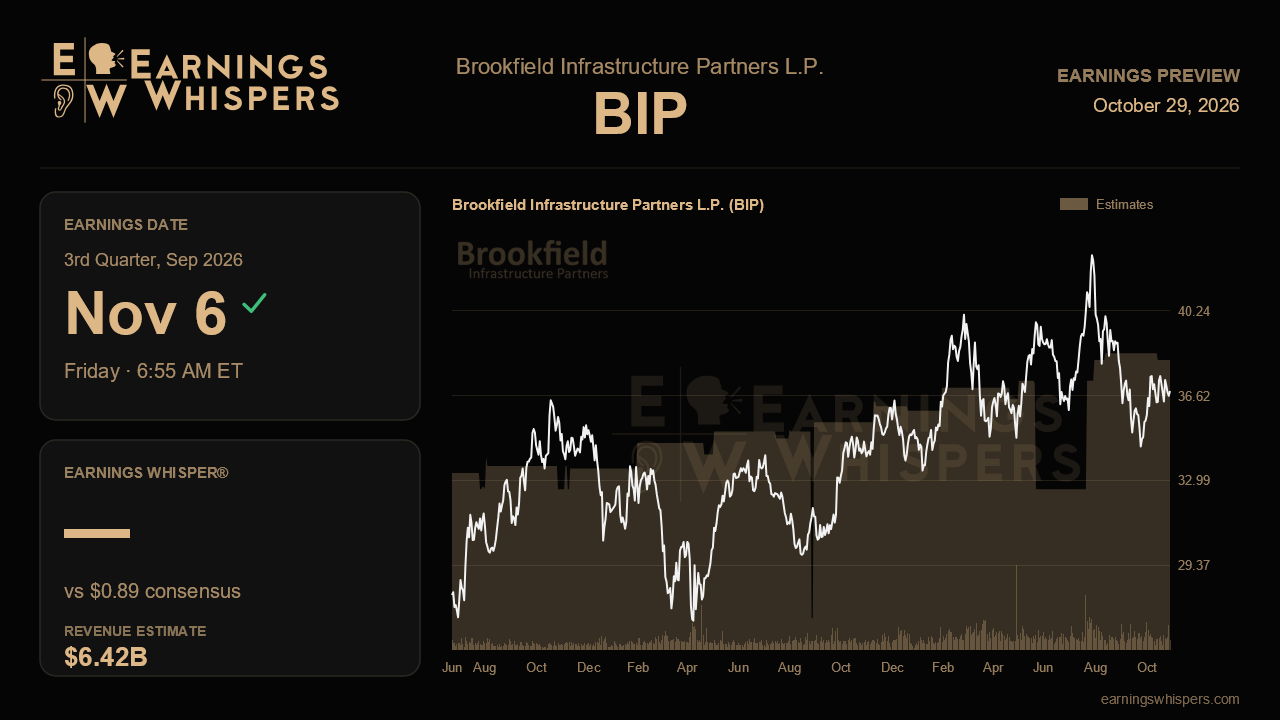
Brookfield Infrastructure Partners heads into its third-quarter report with an odd disconnect. Last quarter, management described an AI infrastructure business moving from slideware to signed contracts: a fivefold expansion of the Bloom framework, a Department of Energy selection for a 1.2 gigawatt Kentucky campus and a sovereign compute partnership with Naver and NVIDIA in South Korea. Since then the units have fallen 13.4% while the S&P 500 gained 4.9%, an 18-point gap that says the market is either doubting the story or bracing for something in the numbers.
The Street is looking for funds from operations of $0.89 per unit on revenue of about $6.42 billion, up 7.2% and 7.5% from a year ago. That is respectable for a utility-like owner of toll roads, pipelines and data centers, but it sits below the 10%-plus per-unit growth management reaffirmed throughout the year and below the 10% pace delivered last quarter. The estimate is also flat with the second quarter's $0.89, and revenue is pegged slightly under the prior quarter's $6.48 billion. In effect, analysts are already allowing for some slippage, likely tied to the earnings given up through asset sales. If Brookfield prints closer to $0.91, consistent with its stated target, the result would quietly support the claim that capital recycling and new investment are offsetting each other. A number at or below consensus would invite the question of whether the 10% framework is becoming harder to hit.
The segment mix matters more than the headline. Midstream was the standout last quarter, with growth accelerating to 17% from 12% in the first quarter and 6% a year earlier. Sustaining double-digit growth there would show that strength is durable rather than a one-quarter spike. Data FFO grew 36%, down from 46% in the first quarter and more than 50% for 2025. Some deceleration is natural as the base grows, but a sharp further slowdown would undercut the AI thesis just as the company is asking investors to value it. Transport, helped by rail, port and toll volumes rising 3% to 7%, needs to keep showing that trade flows remain intact. Utilities, stuck at 5% growth because of the Brazil transmission and Mexico gas sales, are the obvious drag, and any improvement would ease concerns about recycling dilution.
The new catalysts need tangible follow-through. Investors should want evidence that Bloom contracts are scaling beyond their roughly $100 million annual run rate, that AI equity deployment is tracking toward the $300 million to $500 million yearly range, and that the Kentucky and South Korea projects are progressing toward defined commitments. The corporate simplification combining BIP and BIPC was put to unitholders on October 14 with closing targeted for the fourth quarter, so an update on timing is due. Management also flagged risks that deserve fresh commentary: growing community resistance to data centers spreading into Europe and Canada, a temporarily closed IPO window that matters for future public-market exits, slightly higher rates squeezing development yields, and sovereign AI deals that convert slowly, with the heavy capital needs pushed two to three years out.
Sentiment has swung meaningfully, from modestly bullish before the last report to clearly bearish now. The units trade at $36.81, below the 200-day moving average of $37.43 and much nearer the post-report low of $34.30 than the high of $44.04. That backdrop lowers the bar somewhat, since a clean quarter could find a market leaning the wrong way.
The central issue is whether Brookfield can show that its AI origination is translating into contracted growth fast enough to keep the 10%-plus target credible while asset sales weigh on legacy earnings. Reaffirming that target with data and midstream strength intact would validate last quarter's improving tone. Hedging on it, or signaling that NIMBY pushback and shut capital markets are slowing conversions, would suggest the selloff was early rather than wrong.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| Oct-14 | |
| Oct-09 | |
| Oct-06 | |
| Aug-31 | |
| Aug-20 | |
| Jul-30 | |
| Jul-30 | |
| Jul-21 | |
| Jul-02 | |
| Jun-15 | |
| Apr-29 | |
| Apr-29 | |
| Apr-27 | |
| Apr-01 |
