Quanta Services Beats Big, Raises Guidance A Third Time As Backlog Jumps $10 Billion; Supply Chain Is Now The Constraint
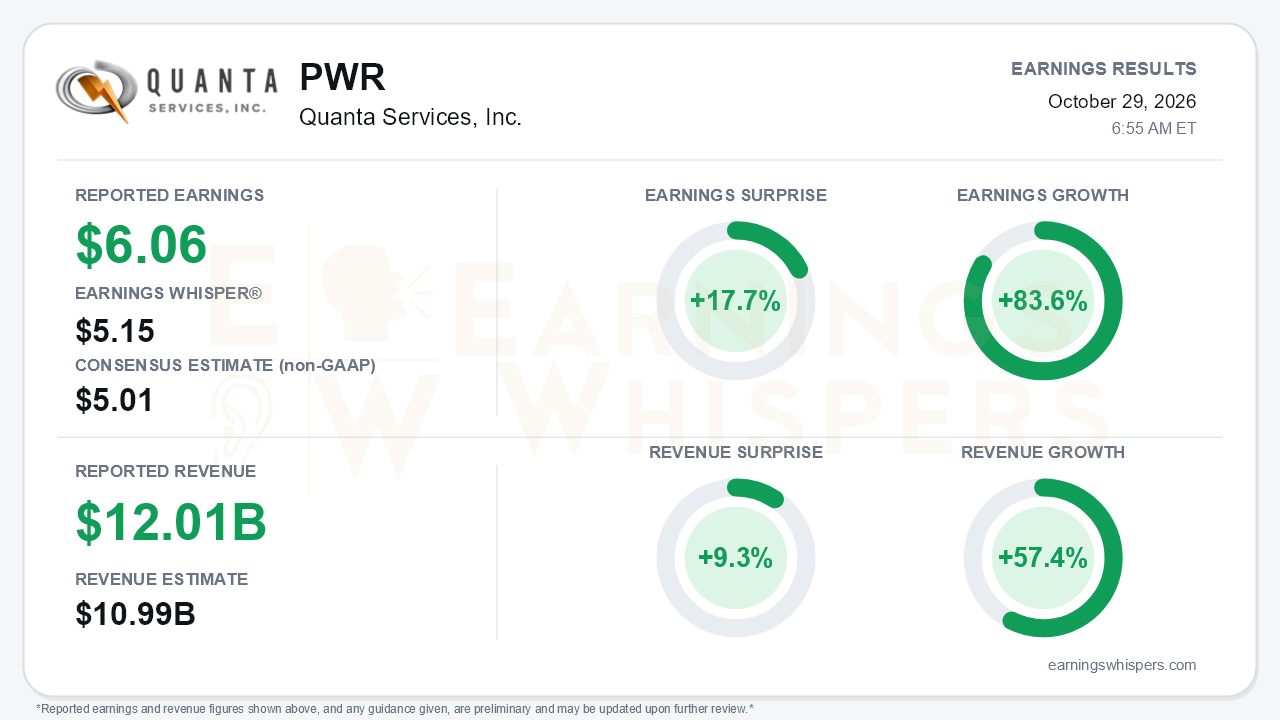
Quanta Services delivered a quarter that went well beyond a routine beat. Adjusted EPS of $6.06 topped the $5.01 consensus by 17.7% and cleared the $5.15 Earnings Whisper number by a wide margin. Revenue of $12.015 billion beat the $10.99 billion consensus by 9.3%. Earnings grew 83.6% year over year and revenue grew 57.4%. That is a sharp acceleration from the first half, when nine-month figures imply revenue growth in the mid-30% range. The more consequential number may be backlog, which rose roughly $10 billion in a single quarter to a record $63.7 billion. Remaining performance obligations roughly doubled from a year ago to $41.8 billion. Quanta is not just executing on demand. It is converting that demand into contracted work faster than it can burn it off.
The quality of the beat holds up under scrutiny, with a few caveats worth noting. GAAP diluted EPS more than doubled to $4.55 from $2.24. Consolidated operating margin expanded to 8.5% from 6.8%, and both segments improved: Electric rose to 12.6% from 11.4%, and Underground and Infrastructure rose to 9.4% from 8.4%. Adjusted EBITDA reached $1.45 billion at a 12.1% margin. The gap between GAAP and adjusted results is meaningful, driven largely by $1.24 per share of intangible amortization tied to an aggressive acquisition program: five deals so far in 2026 and eight in 2025. Some of the headline growth is therefore bought rather than organic. Cash flow was exceptional, with record operating cash flow of $1.45 billion and free cash flow of $1.2 billion. However, contract liabilities climbed to $5.5 billion from $3.3 billion at year-end, so customer prepayments are flattering the cash picture alongside underlying profitability.
The call reinforced how quickly the operating backdrop is shifting. Management said inbound demand is moving at the fastest pace of the CEO's career. It added NiSource bookings covering both transmission and distribution work and power plant scope, and expects large 765kV transmission programs in Texas, Ohio and MISO to book and start in the first half of 2027. Data center electrical and mechanical capture has risen to roughly $5 million to $7 million per megawatt, up from $3 million to $4 million a year ago. Headcount has swelled to about 95,000 from roughly 69,500 at the end of 2025. The notable change in tone is that labor is no longer framed as the binding constraint. Supply chain is. Copper, poles, transformers and breakers are now the stated growth limiter. That explains the acquisition of a steel monopole manufacturer and a manufacturing build-out across roughly ten states.
Guidance was raised across every metric for the third straight quarter:
- **Revenue:** now $41.3 billion to $41.6 billion
- **Adjusted EPS:** now $17.90 to $18.30, up $1.40 at the midpoint, which is more than the size of the Q3 beat
- **Free cash flow:** now $2.5 billion to $3.0 billion
The implied fourth-quarter adjusted EPS of roughly $4.92 to $5.32 sits below Q3's result, so seasonality and conservatism are both embedded in the outlook. Management also signaled strong double-digit adjusted EPS growth in 2027, said it is pacing ahead of its Investor Day 15-20% EPS growth target, and expects Underground and Infrastructure margins to reach double digits in some quarters next year. Bears still have legitimate points:
- **Electric margins:** management describes them as structurally capped around 10-12%, and Q3 already sits at the top of that range.
- **Data center slippage:** analysts flagged some projects sliding or going dark. Management downplayed its exposure to AI learning centers but did not dismiss the concern.
- **Cost pressure:** inflation in fuel, insurance and healthcare persists.
- **Capital needs:** capex is guided at $950 million to $1 billion, and long-term free cash flow conversion is still framed at only 55-60%.
The market setup is more complicated than the surprise implies. Investor sentiment improved meaningfully heading into the report, rising to 0.50 from 0.32. Price action has been far less enthusiastic. Shares closed at $606.89 before the release, down 6.2% from the $647 open following the July report and 2.6% below the 200-day moving average of $623.41. The stock peaked at $724.80 in mid-August, then slid to an inter-earnings low of $527.07 on October 23, just days before earnings, before rebounding about 15% into the print. The Earnings Whispers trend signals are mixed: sequential growth and momentum readings are positive, while the AVWAP trend remains negative.
The bottom line is that Quanta's fundamentals strengthened on nearly every axis that matters: growth accelerated, margins widened, cash flow surged, guidance rose again, and backlog leapt to a record that extends visibility well into 2027. The open questions are whether supply chain bottlenecks cap how fast that backlog converts, and how much of the growth reflects acquisitions. A stock that had sold off sharply into the report now faces a fundamental story that clearly outran its recent price action.
Read our earnings preview for Quanta Services, Inc.: https://www.earningswhispers.com/article/PWR/21122
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 4 hours | |
| 9 hours | |
| 9 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-27 | |
| Oct-26 | |
| Oct-22 | |
| Oct-21 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-09 | |
| Oct-09 |
