Elanco's Fourth Straight Raise Meets A Skeptical Market As Zenrelia Momentum Faces Test
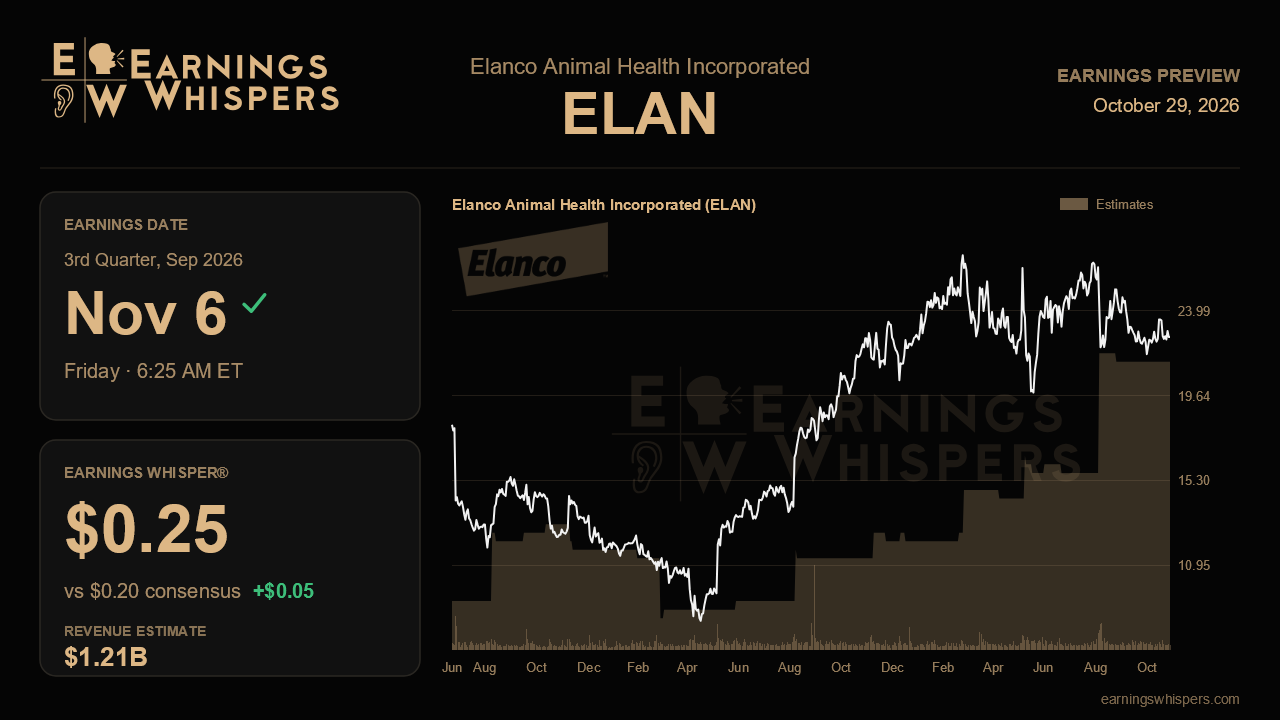
Elanco has spent the past year doing almost everything a turnaround story is supposed to do. It raised full-year guidance for a fourth consecutive quarter, turned Zenrelia into a US blockbuster, pulled leverage down faster than planned and described the first half as its best six months since going public. The stock has gone the other way. Shares have fallen about 16% since the second-quarter report while the S&P 500 was roughly flat, and that gap is the tension heading into the third-quarter release before the bell on November 6.
The numbers on the table are modest by design. Consensus calls for earnings of $0.20 a share on revenue of about $1.21 billion, implying roughly 5% EPS growth and 6% revenue growth from the year-ago $0.19 and $1.14 billion. That sits squarely inside management's quarterly guide of $0.19 to $0.22 and $1.195 billion to $1.220 billion, toward the lower half on earnings and the upper half on sales. The whisper number of $0.25 is the more telling figure. It sits not only above consensus but above the top of company guidance, which suggests the more engaged crowd expects Elanco to keep its habit of clearing its own bar comfortably. Full-year guidance of $1.10 to $1.16 against a $1.11 consensus also leaves room for a fifth raise, and anything short of a nudge higher may read as a pause in the story.
The operational evidence that matters most starts with the innovation portfolio, now targeted at about $1.25 billion for the year after starting 2025 expectations in the $840 million to $880 million range. Zenrelia reached more than 60% of US clinics with reorder rates above 80%, so the question now shifts from penetration to depth: whether revenue per clinic keeps climbing as a new JAK competitor enters dermatology and rivals spend heavily on promotion. Cordelio Quattro's share gains, the Bafrena soft launch where demand ran double expectations despite supply limits that persist into early 2027, and AdTab's 30%-plus international growth should all show continued traction. A further raise to the innovation target would be the cleanest confirmation that the pipeline engine is accelerating rather than plateauing.
The weaker spots from last quarter are where the story could crack. The base business slipped about 1% in the second quarter after growing in the first, and investors will want to know whether that was noise or the start of erosion that innovation must increasingly offset. International farm animal growth fell to 2% from 13%, which management blamed on Middle East shipment timing; a rebound would validate that explanation, while another soft print would invite doubt. Xperia faces tougher comparisons, and operating expenses rose 10% last quarter on direct-to-consumer spending. With inflation still elevated, maintaining the guided 50 basis points of gross margin expansion and roughly 75 basis points of EBITDA margin improvement while funding that competitive fight is a genuine test of operating leverage.
Sentiment has warmed noticeably, with bullish readings at 46% versus about 19% before the last report, yet the tape tells a more cautious story. The stock at $22.65 sits below its 200-day average near $23.81 and much closer to its post-report low of $21.32 than its $27.98 high. That combination of improving fundamentals and a sagging share price can set up a relief move if results reassure, but it also signals that the market is pricing in competitive or base-business risk that guidance alone has not dispelled.
Ultimately, this report hinges on whether Elanco can show that its innovation growth is outrunning both a softening legacy base and rising competitive spending. Delivering near the whisper, lifting full-year targets again and demonstrating stable margins would keep the narrative intact. A quarter that merely lands in range, with base erosion or a dermatology slowdown, would give the skeptics who have driven the stock lower fresh support.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-14 | |
| Oct-07 | |
| Sep-17 | |
| Sep-15 | |
| Sep-11 | |
| Sep-10 | |
| Sep-10 | |
| Aug-31 | |
| Aug-26 |
Elanco celebrates $120 million expansion of Elwood manufacturing facility
ELAN
St. Joseph News-Press, Mo.
|
