Elanco Beats And Raises For A Fourth Straight Time, But A Slower Q4 And 2027 Comparisons Temper The Margin Story
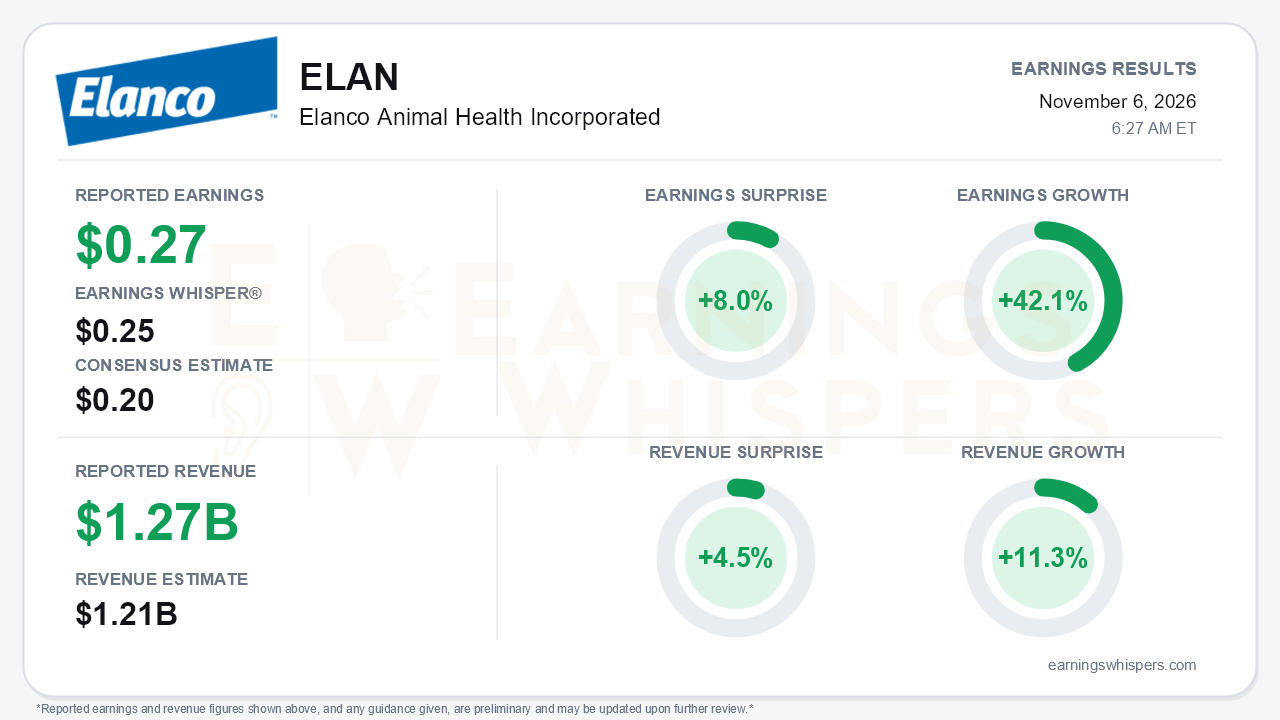
Elanco Animal Health delivered its strongest quarter of the year, and arguably its cleanest beat-and-raise since the innovation cycle began. Adjusted EPS of $0.27 topped the $0.25 Earnings Whisper number and the $0.20 consensus. Earnings Whispers puts the surprise at 8.0% and earnings growth at 42.1%. Revenue of $1.265 billion beat the $1.21 billion consensus by 4.5% and grew 11.3%, or 9% on an organic constant-currency basis. That is an acceleration from the early-year pace. Management raised full-year guidance for the fourth consecutive call. Adjusted EPS guidance moved to $1.17 to $1.20 from $1.10 to $1.16, and organic growth guidance rose to about 8%. The initial February outlook had called for 4% to 6%. The central tension is that Q3 may mark the high-water mark of this cycle's momentum. The company is already guiding Q4 lower and flagging a crowded list of 2027 headwinds.
The composition of the quarter is better than a simple volume beat. Price accelerated to 4% from 2% in each of the first two quarters, with Pet Health price at 5%. Volume held at 5%. Adjusted gross margin rose 300 basis points to 56.1%. The progression through the year matters: margin fell 40 basis points in Q1, rose 80 basis points in Q2, and then jumped 300 basis points in Q3. Management attributed the gain to pricing, mix toward U.S. Pet Health and ruminants, and a now-flushed high-cost inventory headwind. Adjusted EBITDA rose 23% to $243 million, and the adjusted EBITDA margin widened to 19.5% from 17.5%. On a GAAP basis, Elanco swung to net income of $18 million, or $0.04 per share, from a $34 million loss a year ago. The gap between GAAP and adjusted results remains wide, driven largely by $144 million of amortization.
The quality of the beat still deserves some scrutiny. The adjusted tax rate fell to 19.4% from 26.5%, which gave adjusted EPS a lift that operations alone did not provide. Operating cash flow of $216 million was essentially flat year over year. Even so, leverage fell to 2.9x from 3.6x at year-end 2025, reaching the sub-3x milestone roughly a year ahead of the original plan. Year-to-date free cash flow of $362 million is tracking ahead of the company's $1 billion-through-2028 target.
The product engine is what keeps the growth story credible.
- **Zenrelia** posted its largest quarter ever. U.S. JAK share rose 7 points year over year, and the drug is now in roughly 19,000 clinics.
- **Credelio Quattro** gained 9 share points, reached about 55% clinic penetration (up from about 40% in Q1), and passed Seresto as Elanco's largest U.S. Pet Health brand.
- **U.S. Pet Health** growth accelerated from 6% in Q1 to 11% in Q2 and 13% in Q3. International Pet Health jumped 17%.
- **Innovation revenue** rose 40% to $328 million, and the full-year innovation target was raised again to $1.275 billion.
The 2027 catalysts are concrete. Credelio Quattro has a positive EU opinion and a planned Q1 launch. Befrena moves to full U.S. launch in Q1; the call notes spell the product "Bofrena," and management suggested it could be the largest single contributor to U.S. Pet Health growth next year.
Bears have legitimate ammunition, however.
- **Q4 deceleration:** Organic growth is guided to just 4% to 6%, while operating expenses are expected to rise about 11%.
- **Price normalization:** Management expects price to revert to the historical 2% to 3% range as launch-offer pullbacks are lapped.
- **Costco:** The non-renewal will mostly hit Q1 2027.
- **Middle East comparison:** Q1 2027 also laps accelerated Middle East shipments that added about a point to growth in Q1 2026.
- **Befrena margins:** The Befrena ramp will dilute gross margin while inflation persists.
- **Competition:** Promotional and gross-to-net activity is intensifying in dermatology and parasiticides. A new JAK entrant and a competing long-acting IL-31 product are both in the market. U.S. derm market revenue is flat despite dose growth, and Quattro clinic switching slowed late in the season.
- **Farm Animal:** International farm grew only 1% organically, and poultry fell 7%.
Management reaffirmed its 2027 algorithm early: mid-single-digit organic growth, high-single-digit EBITDA growth and low-double-digit EPS growth. That framework implies a return to a more ordinary cadence after this year's outperformance.
The market has not been rewarding the fundamental progress. Shares opened at $27.08 after the August report and touched a 52-week high of $27.98 that day. They then slid to $21.32 within days and stood at $23.68 ahead of this release. That is down 12.6% since the prior report and about 15% below the August peak. The stock enters the print essentially at its 200-day moving average of $23.80, sitting in the middle of its inter-earnings range. Investor sentiment improved meaningfully, rising from 0.19 to 0.45. Expectations were therefore warming into a stock that had been de-rated, a setup more complicated than the surprise alone implies.
The bottom line is that Elanco delivered accelerating price, sharply wider gross margin, early deleveraging and a fourth straight guidance raise, the kind of execution turnaround skeptics have been waiting for. The open question is durability. With Q4 growth guided toward the mid-single digits, price normalizing and 2027 carrying Costco, comparison and Befrena margin headwinds, investors will need the EU Quattro and Befrena launches to prove this quarter was a platform rather than a peak.
Read our earnings preview for Elanco Animal Health Incorporated: https://www.earningswhispers.com/article/ELAN/22482
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 9 hours | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-19 | |
| Oct-14 | |
| Oct-07 |
