Delek Logistics Heads Into Q3 With A Guidance Raise And Sour Gas Ramp On The Line
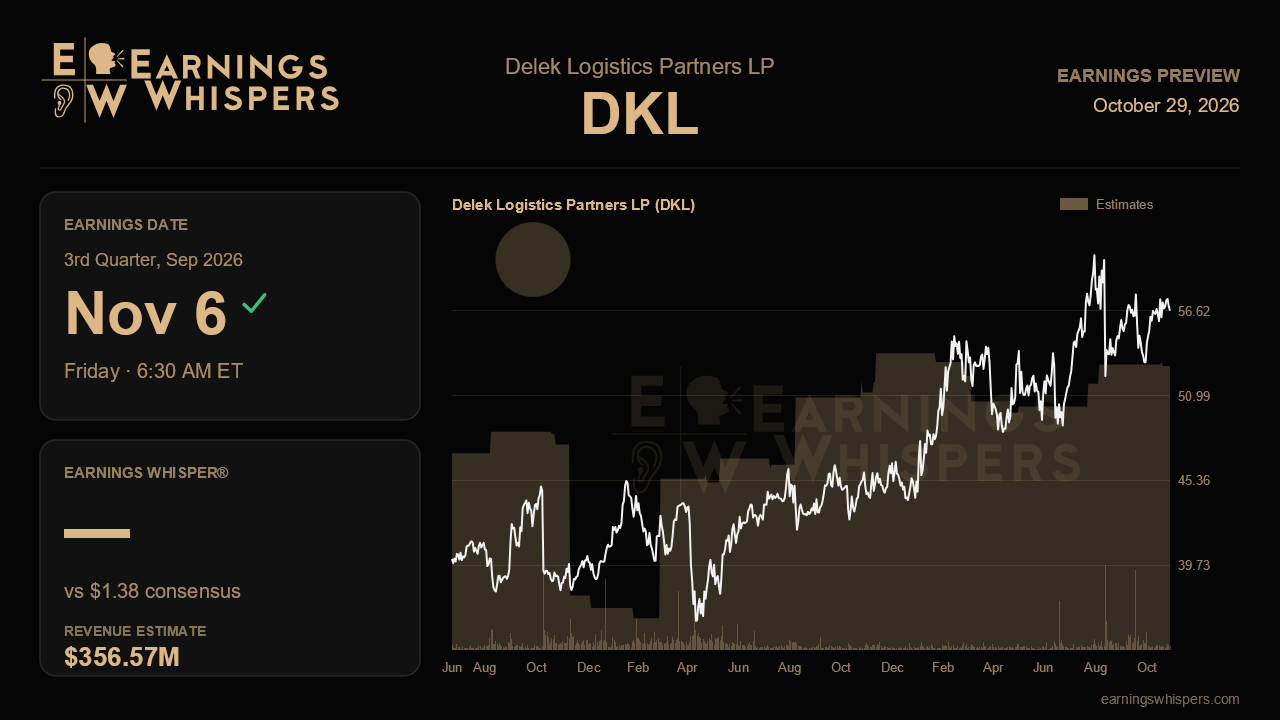
Last quarter, Delek Logistics management all but told the market a raise was coming. On the second-quarter call, executives effectively endorsed analyst math pointing to the high end of their $520 million to $560 million adjusted EBITDA range and hinted that, as they did a year ago, the third quarter could be the moment to lift it. That makes the November 6 report, due before the open, less a test of whether the partnership is growing and more a test of whether it can deliver the upgrade it has already teased.
The Street is braced for a big year-over-year jump. Consensus calls for earnings of $1.38 per unit, up about 62% from $0.85 a year ago, on revenue of roughly $356.6 million, up about 36.5%. That is a steep improvement from the $0.54 posted last quarter, although revenue is expected to slip from the $384.8 million reported then. For a midstream partnership, the more telling figure is adjusted EBITDA, which hit a record $144 million in the second quarter after $132 million in the first. Annualize the second quarter and you land near the midpoint of guidance. Holding that run rate gets the partnership near the top only if the back half keeps stepping up, so a third-quarter print comfortably above $144 million would make a raise credible, while a flat or lower number would leave the reaffirmed range looking about right rather than conservative.
The gathering and processing segment is where the story lives. Its EBITDA jumped to $104 million from $83 million in the first quarter, helped by better utilization at the Libby complex and stronger Permian crude margins. Operating volumes surged across the board: Delaware crude gathering hit a record of roughly 157,000 barrels a day, produced water climbed to about 687,000 barrels a day, and gas volumes topped 80 million cubic feet a day from about 64 million. Investors should want to see those volumes hold or grow, particularly gas, because management framed the full sour gas solution at Libby as a coming step change. The first acid gas injection well is done and the gathering and compression build-out was nearing completion. Evidence that this system is online or tracking to schedule would validate the thesis; any slippage would echo a known risk, since the sour gas ramp has run slower than planned before.
Other tailwinds deserve scrutiny too. Management pointed to firmer Waha gas prices, new residue gas takeaway arriving early next year, and roughly 20 rigs added in the Permian as higher crude prices spurred producers. Some of that crude support is tied to Middle East tensions and could fade, so commentary on producer activity on Delek's acreage matters as much as the quarter's numbers. The $180 million to $190 million growth program, targeted to produce up to $75 million of run-rate EBITDA, is also the reason leverage rose to 4.23 times, above the 3.5 times long-term target. Progress toward deleveraging, aided by the $800 million 2034 note refinancing that cut interest costs and pushed out maturities, would ease that concern. Known drags in wholesale marketing and storage and transportation, stemming from contract and dropdown restructurings, should not surprise anyone.
Sentiment has warmed noticeably, rising to a moderately bullish reading from near neutral before the last report. The stock has not followed, slipping 0.7% since the prior release, essentially in line with the S&P 500. At $56.62 it sits above its 200-day average of $53.24 and in the middle of its post-earnings range of $50.60 to $60.00, so the market has neither rewarded the record quarter nor punished the rising leverage.
That neutral price action leaves the decision to the report itself. If EBITDA steps up again, the sour gas system shows tangible progress and management actually raises the range, the improving narrative holds and the distribution-growth story, now 54 straight increases with coverage near 1.33 times, looks well funded. A reaffirmation without a raise, after last quarter's hints, would be the clearest sign that the back-half ramp is running behind.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| Oct-23 | |
| Oct-16 | |
| Oct-16 | |
| Sep-24 | |
| Sep-24 | |
| Sep-03 | |
| Aug-31 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-08 | |
| Aug-05 | |
| Aug-05 |
