Delek Logistics Misses Badly On EPS As Dilution Flattens Per-Unit Results; Sour Gas Start-Up Now Carries The Thesis
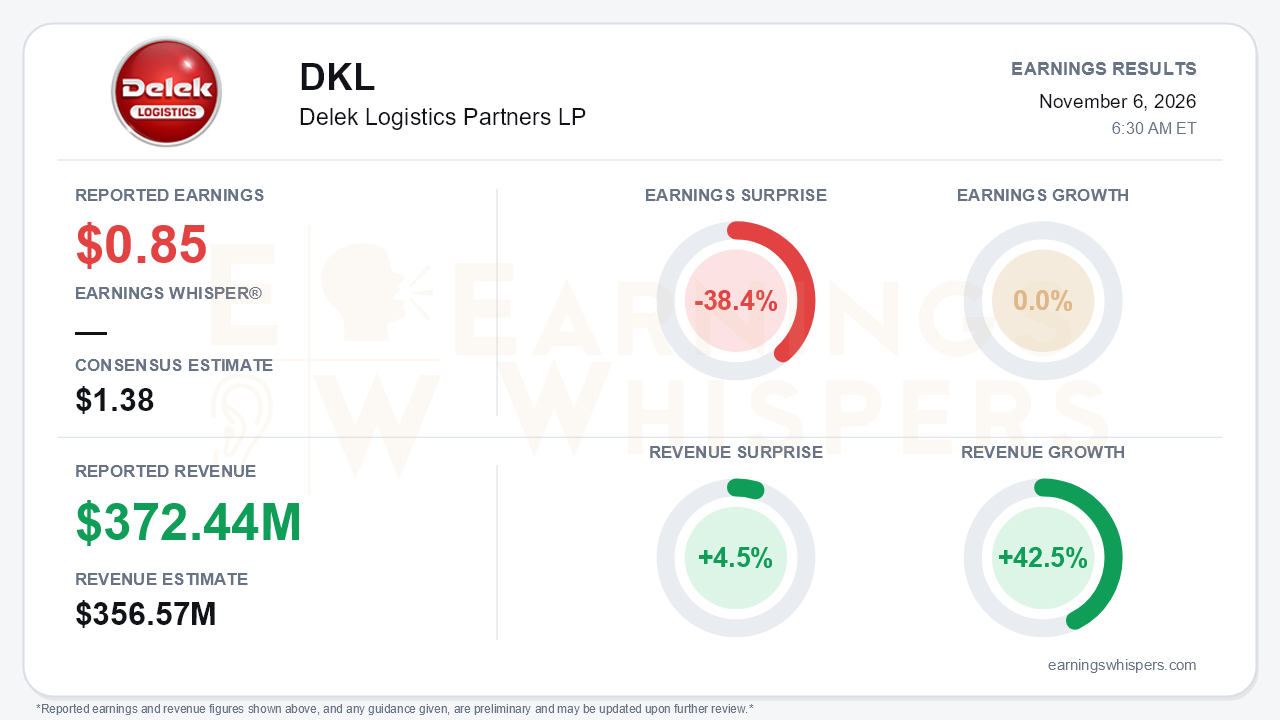
Delek Logistics Partners (NYSE: DKL) posted third-quarter earnings of $0.85 per unit, 38.4% below the $1.38 consensus and unchanged from a year ago. Revenue of $372.44 million beat expectations by 4.5% and rose 42.5% year over year. The EPS miss is large, but it matters less than what sits beneath it. Adjusted EBITDA was $142.9 million, essentially flat against both $142.5 million a year ago and the record $144 million in the second quarter. DKL is a business whose cash generation has stalled for now. It just issued 4.6 million new units, and its next leg of growth depends on a sour gas system that was still commissioning when the quarter closed. That is the central tension.
The quality of the revenue beat deserves scrutiny. Third-party cost of materials jumped to $111.3 million from $44.2 million, so much of the 42.5% top-line growth was low-margin, pass-through activity rather than incremental profit. GAAP net income did rise to $47.4 million from $45.6 million. However, weighted diluted units grew to 55.7 million from 53.5 million, which held per-unit earnings flat. Sales-type lease accounting also continues to move $24.6 million of minimum-volume fees out of revenue and into interest income, a recurring reason GAAP figures diverge from the EBITDA framework management emphasizes. The cash picture is more mixed than the $187.9 million in operating cash flow suggests. That figure was inflated by roughly $108 million of working-capital movement, including a sharp rise in payables. Distributable cash flow, as adjusted, was $73.1 million, down from about $81 million in the second quarter. Coverage fell to 1.11x from 1.33x in the second quarter and 1.24x a year earlier, the thinnest cushion of the year just as the distribution was raised to $1.14.
The operating story is split. Delaware natural gas volumes are the clear bright spot: 93.8 MMcf/d versus 62.7 MMcf/d a year ago, up sequentially from about 80 in the second quarter and 64 in the first. West Texas wholesale margin more than doubled to $9.99 per barrel. Wholesale Marketing and Terminalling rebounded to about $21 million from $13 million in the second quarter. Elsewhere, momentum faded:
- Gathering and Processing EBITDA rose year over year to $88.4 million but fell sharply from $104 million in the second quarter.
- Midland gathering, Plains Connection, and Midland water volumes all declined year over year, and management attributed the sequential dips in crude and water to well-connection timing.
- Equity income from pipeline joint ventures slipped to $26.5 million from $28.4 million.
The forward story rests on Libby. The first sour gas compressor station is complete, and the acid gas injection well is being commissioned, with integrated start-up expected within weeks. Management said producers' wells are waiting on the system and predicted a "pretty substantial jump" in gas volumes. It also said it is evaluating further sour gas expansion. The growth program is still framed as roughly $15 million of EBITDA in 2026 and $60 million in 2027, so the 2027 step-up depends directly on ramp timing. Full-year guidance was raised to $530–$560 million, but only at the low end. That restraint stands out because the CEO had acknowledged last quarter that run-rate math pointed to the high end. With $418.7 million already booked through nine months, the guidance midpoint implies a fourth quarter below the third-quarter level. On the balance sheet, the roughly $220 million equity raise cut leverage to 3.85x from 4.23x in the second quarter, lifted liquidity to about $1.3 billion, and reduced Delek US's ownership to about 58%. That advances the separation story at the cost of dilution.
The market had already priced in skepticism. Shares closed at $51.24 before the report, down 10.1% from the $57.00 open after the prior release. They sat 14.6% below the $60.00 inter-earnings high set in mid-August and just 1.6% above the quarter low of $50.45 reached the day before the report. The stock is 4.1% below its 200-day moving average and trading near the $50 offering price. Investor sentiment improved slightly to 0.06 from 0.02, a modest change that leaves expectations close to neutral rather than enthusiastic.
The bottom line is that DKL delivered a deleveraging quarter, not a growth quarter. EBITDA was flat, coverage thinned, and per-unit earnings missed badly as the unit count rose. In exchange, the balance sheet is stronger and the sour gas platform is weeks from start-up. Bears have legitimate ammunition in the coverage decline and the cautious guidance raise. Bulls need visible gas volume acceleration in the coming months to justify the 2027 uplift and to move a stock that has drifted back toward its offering price.
Read our earnings preview for Delek Logistics Partners LP: https://www.earningswhispers.com/article/DKL/22480
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Nov-06 | |
| Oct-29 | |
| Oct-29 | |
| Oct-23 | |
| Oct-16 | |
| Oct-16 | |
| Sep-24 | |
| Sep-24 | |
| Sep-03 | |
| Aug-31 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 |
