Gogo's Promised Second-Half Equipment Ramp Faces Its First Real Test After Guidance Cut
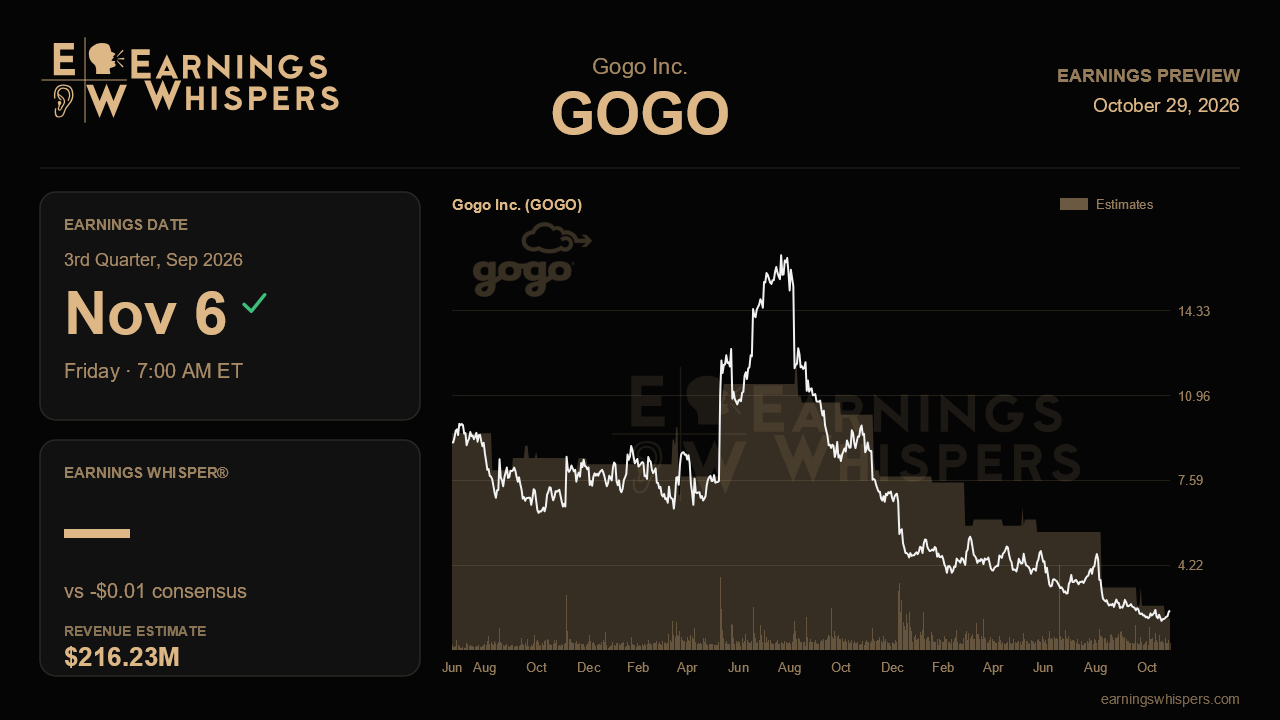
Three months ago Gogo asked investors to accept a simple bargain: the full-year outlook was coming down, but mostly because equipment shipments were sliding into the back half of the year, not because customers were walking away. The third-quarter report, due before the open on November 6, is the first chance to check whether that explanation holds up. If Galileo and 5G hardware starts flowing in volume, the cut looks like a timing problem. If it does not, the market's harsher reading of the last quarter will look justified.
The Street is braced for a soft quarter. Consensus calls for a loss of about a penny per share, compared with a $0.10 profit a year ago, and revenue of roughly $216.2 million, down 3.3% from the prior year and below the $222.8 million booked last quarter. That is contraction, not stagnation. The sequential decline makes sense given two forces management flagged: the record military and government quarter was driven by unusual Middle East usage and was explicitly described as not a normal run rate, and legacy air-to-ground subscribers are still rolling off as NetJets transitions and older aircraft migrate to newer systems. The awkward detail is that the full-year consensus of about $914.6 million still sits above the top of management's reduced $870 million to $895 million range, which suggests some annual estimates have not fully caught up even if the quarterly number looks appropriately cautious.
The guidance cut deserves context because it came after the company had reaffirmed its targets on the two previous calls. Revenue, adjusted EBITDA and free cash flow were all lowered at once, with EBITDA trimmed to $175 million to $185 million. Roughly half of that EBITDA reduction reflects SmartSky litigation costs now pegged near $22 million for the year, up from $8 million, and management indicated the burden likely lingers into 2027. That expense is a reasonable explanation for weak earnings per share this quarter, but any further increase would erode confidence that the cost side is under control.
The operating scorecard matters more than the headline numbers. Equipment revenue fell 18% sequentially to $31.5 million in the second quarter, so a visible rebound is the clearest validation of the timing argument. Galileo aircraft online reached 184, and management's lowered year-end goal in the mid-500s implies roughly doubling that base across the second half; a third-quarter figure that does not show real progress toward that target would put the goal at risk. The company also needs to show movement on the 20 outstanding FDX certifications stuck in the FAA backlog, evidence that every business-jet manufacturer now under contract is actually starting factory line-fit, and early contributions from new certifications on the G650, Falcon 7X and 8X, and PC-12, plus the Airshare Phenom fleet win. Free cash flow, which swung to a positive $21.6 million last quarter, should keep building if the reduced $65 million to $85 million annual target is credible, and any easing of net leverage from 3.8x would help.
The stock has already delivered its verdict on last quarter, falling about 28% since the report while the S&P 500 was essentially flat. At $2.42 it trades far below its 200-day moving average of $3.70 and sits closer to the $1.96 low than the $3.89 high of its post-earnings range, a sharp downshift from the $3 to $5 band of the prior quarter. Sentiment remains bearish, though slightly less so than heading into the last report, which hints that some of the pessimism may be priced in.
Ultimately, this quarter comes down to whether Gogo can prove that its new hardware is leaving the warehouse and lighting up aircraft on the schedule management laid out. Confirmation of a genuine equipment and Galileo activation ramp, alongside a reaffirmed guidance range, would support the case that the business is in transition rather than decline. Another slip in shipments or another trim to the outlook would make the earlier cut look less like a pause and more like a pattern.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Oct-19 | |
| Oct-15 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 | |
| Oct-08 | |
| Oct-01 | |
| Sep-22 | |
| Sep-22 | |
| Aug-06 |
