Gogo Beats On EPS As Galileo Ramps, But Shrinking ATG Revenue And A 24% EBITDA Drop Keep Margins In Question
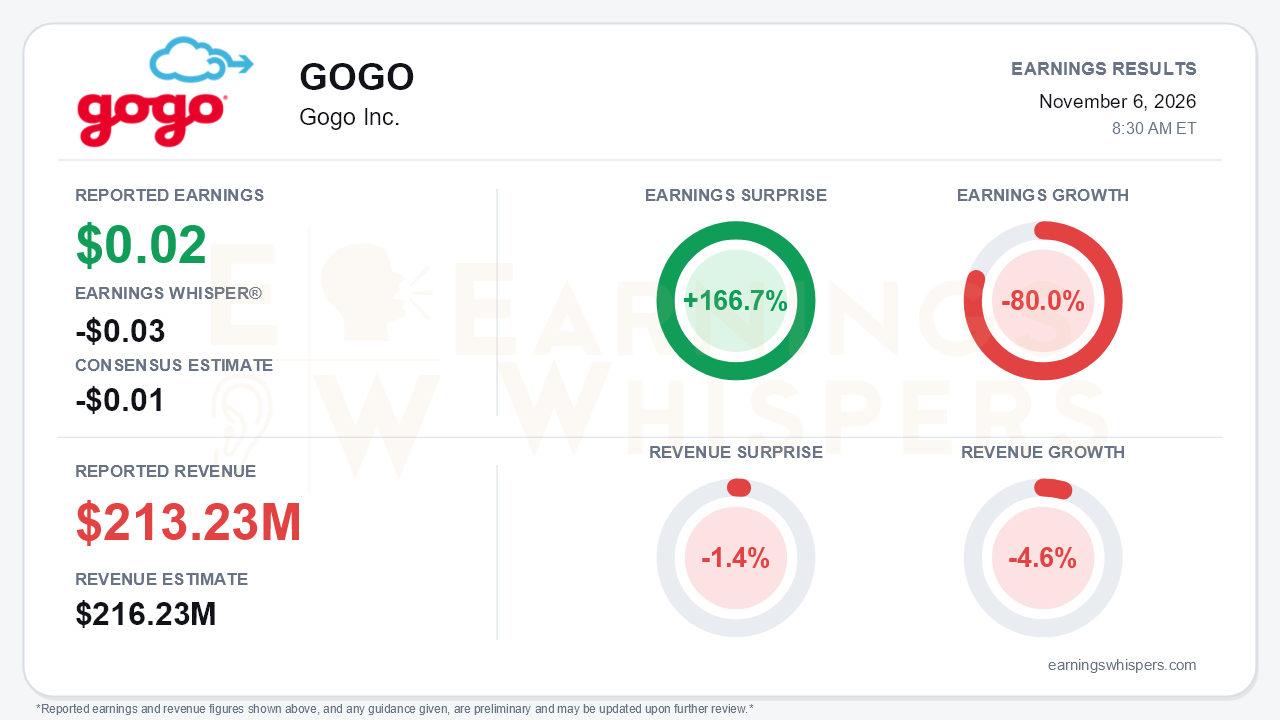
Gogo cleared a low bar in the third quarter, but the quarter was more mixed than the beat suggests. Earnings Whispers puts reported EPS at $0.02, against a consensus estimate of -$0.01 and an Earnings Whisper number of -$0.03, a 166.7% surprise. Earnings still fell 80.0% from a year ago. Revenue of $213.23 million missed consensus by 1.4% and declined 4.6% year over year. On a GAAP basis, Gogo posted a net loss of $3.2 million, or $0.02 per diluted share, compared with a $1.9 million loss a year earlier. A tax benefit kept that loss smaller than the $6.6 million pre-tax deficit. The quarter's central tension is that the LEO transition is gaining real traction while the legacy ATG base shrinks faster than the new business can offset it.
The revenue mix shows the handoff clearly:
- **Satellite broadband service revenue** rose 7% to $83.9 million.
- **Satellite equipment revenue** nearly doubled to $17.3 million.
- **ATG broadband service revenue** fell 22% to $55.5 million.
- **ATG equipment revenue** dropped to $6.6 million from $17.5 million.
Business aviation service revenue declined 10% year over year. Military/government service revenue grew 36% from a year ago but slipped 7% sequentially as Middle East-driven usage moderated.
Profitability weakened. Adjusted EBITDA fell to $41.0 million, down 24% from Q2's $53.7 million and 27% from a year ago. Gross margin slipped to roughly 40% from 42%, which management tied to ATG service mix and aggressively priced Galileo fleet deals. GAAP operating income dropped to $17.2 million from $28.7 million, even though engineering spending fell by more than a third.
The call explained why management sounded more confident despite those numbers. Galileo momentum is accelerating:
- **Shipments:** a record 172 units, up from 92 in Q1 and 108 in Q2.
- **Aircraft online:** 297, up from 184 in Q2.
- **Pricing:** average monthly service revenue per Galileo aircraft rose 6% sequentially as promotional pricing rolls off, a trend management expects to continue through the first half of 2027.
- **Customer wins:** the list now spans every channel. Textron will make HDX standard fit on Citation Longitude, Latitude and Ascend jets, which the call placed from 2028. PlaneSense committed its full 71-aircraft fleet. Duncan Aviation ordered 40 HDX units, Bombardier placed its first sizeable OEM order, and TransMedics will equip 22 Phenom 300Es.
- **Upgrades over defections:** 71% of ATG deactivations were upgrades, and losses to competitors hit their lowest level.
The cumulative Galileo shipment figure is unclear. The release cites 372 units, while the call referenced roughly 690 at quarter end. Investors should treat cumulative figures cautiously until the definitions are reconciled.
The weak spot is Gogo 5G, which bears have legitimate grounds to question. Shipments halved to 68, and only 94 aircraft are online versus the roughly 400 targeted for year-end earlier this year. Total ATG aircraft online fell 17% to 5,399, and the classic network transition now runs into Q1 2027 after the FCC granted a six-month rip-and-replace extension. The reimbursement assumption was also cut to $35 million from $45 million.
Reiterated guidance deserves scrutiny. The 2026 ranges of $870-$895 million in revenue and $175-$185 million in adjusted EBITDA were already reduced in August. With $148 million of adjusted EBITDA booked through September, the full-year range implies Q4 EBITDA of roughly $27-$37 million. That is below Q3's level, even with litigation expense trimmed to $18 million from $22 million after the SmartSky verdict was vacated. The guidance therefore signals no near-term margin recovery. Free cash flow is where the back-half lift sits. Year-to-date FCF of $30.5 million leaves a substantial Q4 requirement to reach the $65-$85 million range. Q3 FCF of $28.1 million, up from -$19.2 million in Q1, makes that more plausible.
The balance-sheet news is a genuine positive. The roughly $600 million Term Loan B now matures in October 2030, with $75 million of principal paydown committed by the end of 2027. Cash rose to $90.7 million. Net leverage, however, climbed to 4.0x, above the 2.5-3.5x target. The 10-year FCC renewal of Gogo's ATG spectrum also opened a new option: management is formally reviewing spectrum and tower monetization with bankers.
The market had braced for worse. Shares fell 33% from the $3.38 open after the August report to $2.27. They touched a 52-week low of $1.96 on October 19 and sit roughly 37.5% below the $3.62 200-day moving average. Investor sentiment remained negative but improved modestly, from -0.26 to -0.21. That suggests expectations were already depressed rather than newly optimistic.
The bottom line is that Gogo delivered an EPS beat and a more credible LEO growth story, with stronger cash generation, a refinanced runway and a possible spectrum catalyst. Revenue is still shrinking, EBITDA and margins are moving the wrong way, 5G is badly behind plan and leverage is rising. Until Galileo's recurring revenue visibly outweighs ATG attrition, the stock's depressed position reflects unresolved execution risk as much as pessimism.
Read our earnings preview for Gogo Inc.: https://www.earningswhispers.com/article/GOGO/22488
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| 4 hours | |
| Oct-30 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Oct-19 | |
| Oct-15 | |
| Oct-13 | |
| Oct-09 | |
| Oct-08 |
