Sunstone's Third-Quarter Test: Can Hotel Momentum Outrun The San Francisco Sale's Revenue Gap?
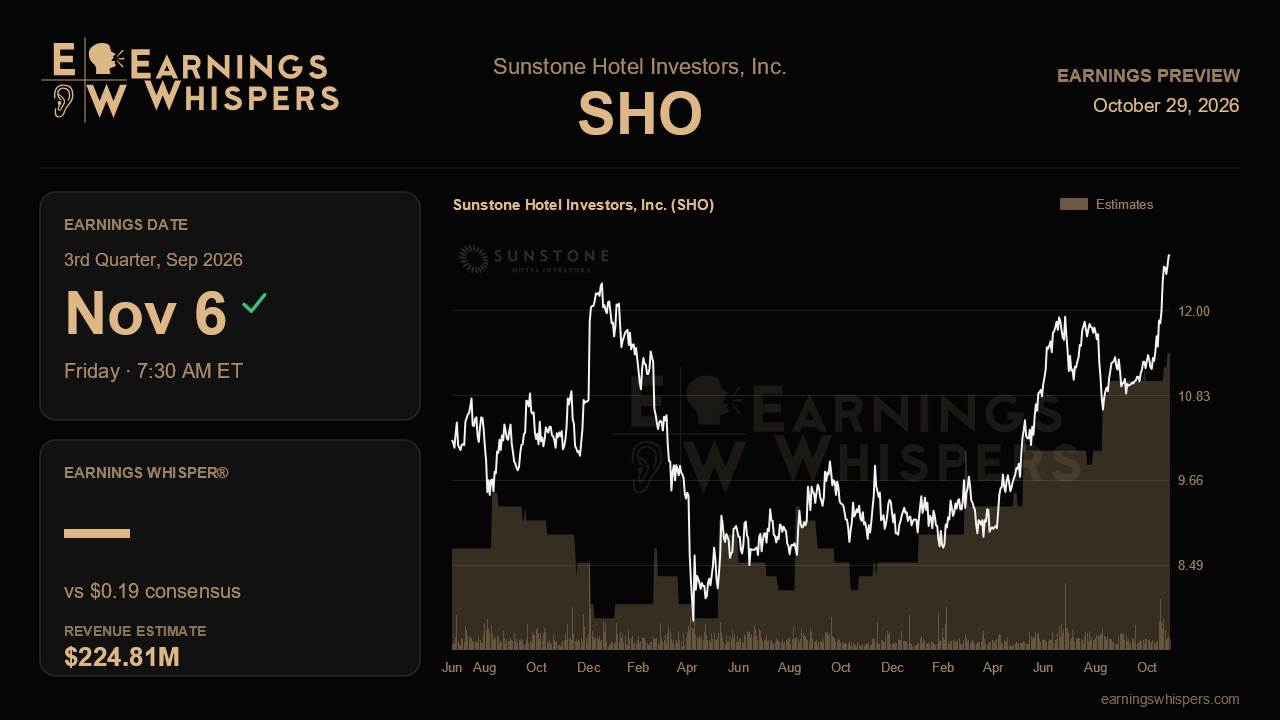
Sunstone Hotel Investors heads into its third-quarter report with an unusual mix of tailwinds and arithmetic. Management has raised its full-year outlook three straight times, the balance sheet is flush after selling its San Francisco hotel at a rich price, and the stock is pressing against its highs. The quarter must now show that this momentum survives a smaller portfolio and the cautious second-half posture management chose to keep.
The Street expects earnings of $0.19 a share, up about 12% from $0.17 a year ago, on revenue of roughly $224.8 million, down 2%. That gap between rising per-share results and falling revenue is the story in brief. Selling the Hyatt Regency San Francisco in late July removed a meaningful revenue contributor. Buybacks of about $70 million in common and preferred stock this year, plus lower leverage, help offset that on a per-share basis. A clean report would show modest top-line shrinkage that is clearly explained by the disposition, paired with earnings growth from the remaining hotels and a lower share count.
Guidance puts the bar in an interesting spot. Management now expects full-year FFO of $0.93 to $0.98 a share, up from $0.88 to $0.96 previously, yet the consensus full-year estimate sits at $0.91, below the bottom of the range. With $0.59 already booked in the first half, the company needs at least $0.34 over the final two quarters to reach its low end. A $0.19 third quarter would leave roughly $0.15 to $0.20 needed in the fourth, which looks reachable against last year's $0.20. The lagging consensus suggests analysts either doubt the guidance or have not fully absorbed it. Either way, holding or nudging the range higher again would put pressure on estimates to catch up. Trimming it would hurt more than usual, because it would break a pattern investors have come to rely on.
The operating checklist comes straight from last quarter's call. Resorts drove the gains, with combined growth near 27% and Wailea posting strong occupancy and profit gains, so continued resort strength through the softer summer season is the first test. Forward transient pace was up 22% for the next six months, and July came in better than expected. Results should confirm that pace turned into actual stays rather than fading. San Diego is the main swing factor. The Hilton Bayfront's total RevPAR fell 8.4% in the second quarter on a thin convention calendar and a meeting-space renovation, and the shift toward transient guests weakened the economics of a large group hotel. Any sign the trough has passed, along with confirmation of the double-digit 2027 group pace, would ease that concern. Margins matter too. Management called the second quarter's 4.4% expense growth the toughest comparison of the year, so slower cost growth now would support the view that the pressure was about timing.
The smaller catalysts deserve a look as well. Early results from the Hilton Key West conversion, Andaz Miami Beach's ramp ahead of the Bazaar Meat opening and an expected fourth-quarter lift from a nearby W Hotel closure are all parts of the bullish case. So is the question of how the remaining sale proceeds, with cash near $430 million, will be put to work.
The market has already moved ahead of the report. Shares have gained 7.5% since the last release while the S&P 500 was roughly flat, and at $12.76 the stock is testing its post-earnings high of $12.83, well above its 200-day average near $10.51. Sentiment has nonetheless cooled from mildly bullish to mildly bearish, which hints at some fatigue after a strong run. In the end, the narrative holds up if Sunstone shows that its slimmer portfolio can keep growing per-share earnings while San Diego stabilizes and costs ease. A fourth guidance increase would strengthen the breakout case, while a merely reaffirmed outlook could leave a richly priced stock with little to push it higher.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Oct-29 | |
| Sep-18 | |
| Aug-06 | |
| Aug-06 | |
| Jun-26 | |
| Jun-24 | |
| Jun-23 | |
| Jun-07 | |
| May-05 | |
| May-05 | |
| Mar-31 | |
| Feb-28 | |
| Feb-28 | |
| Feb-27 | |
| Feb-27 |
