Sunstone Beats And Raises Again, But Thin Margin Flow-Through Remains The Catch
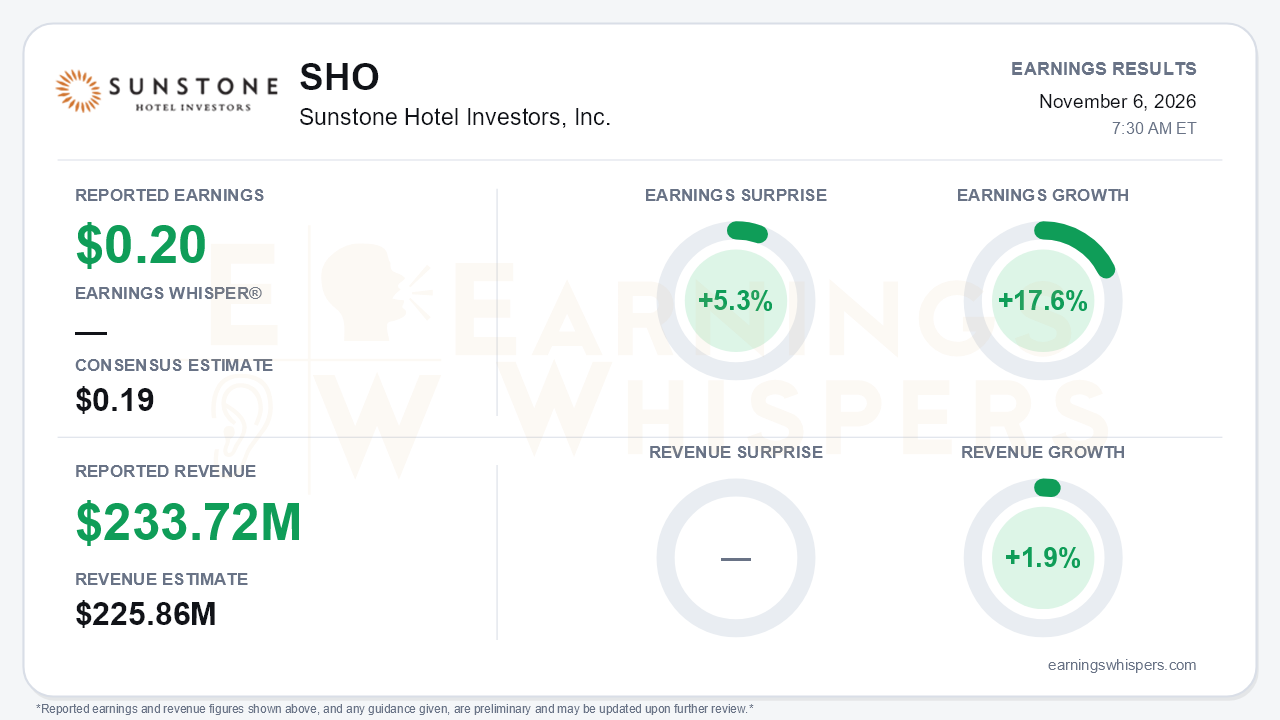
Sunstone Hotel Investors delivered another beat-and-raise quarter, and the more consequential news may be its outlook for 2027. Adjusted FFO of $0.20 per share topped the $0.19 consensus by 5.3% and grew 17.6% year over year. Revenue of $233.72 million beat the $225.86 million estimate by 3.5%. Management raised full-year 2026 guidance for the third consecutive quarter, lifting adjusted FFO per share to $1.00-$1.03 from $0.93-$0.98. On the call, it also indicated that the 2027 quarterly dividend should rise to $0.11-$0.12 from the current $0.09. The central tension is that top-line momentum is clearly accelerating while margin conversion still lags. The quality of the beat therefore depends on whether that gap closes next year.
The headline revenue growth of 1.9% understates the portfolio's operating strength. The July sale of the Hyatt Regency San Francisco removed most of that hotel's year-earlier contribution. For the 13 hotels Sunstone still owns, RevPAR rose 11.4% to $235.22, with occupancy up 460 basis points to 72.7% and average daily rate up 4.4%. Excluding the newly reopened Andaz Miami Beach, RevPAR still increased 10.3%. That is a sharp acceleration from roughly 4.3% on the same basis in the second quarter, which makes the improvement broad-based rather than a single-asset story. GAAP results also flipped to net income of $0.21 per share from a $0.02 loss. However, that swing was driven largely by a $31.5 million gain on the San Francisco sale, so adjusted FFO is the cleaner read.
Margins are where bears have legitimate ammunition. Total RevPAR grew 10.5%, yet hotel adjusted EBITDAre margin excluding Andaz expanded only 50 basis points to 26.7%. Year to date, that margin is down 20 basis points. Management attributed the weak flow-through to several factors:
- a transient-heavy mix at hotels built for group business;
- displacement from the Hilton Key West renovation, where RevPAR fell about 10%;
- energy costs running above expectations;
- repeated storm cleanup costs at Wailea.
Management estimates margins would have expanded roughly 200 basis points excluding Key West and one-time items. That adjustment is plausible, but it remains an adjustment. Energy costs, which management described as largely outside its control, are not obviously temporary.
The forward evidence gives the bull case real substance. Management cited:
- 2027 group pace up mid-to-high single digits for the portfolio;
- San Diego group pace up 10%-plus and Wailea up 20%-plus;
- transient pace up 9% for the next six months;
- record third-quarter group production in Orlando, up more than 40%.
Management expects group segmentation in San Diego and Washington, D.C. to normalize, which should improve flow-through in 2027. Andaz Miami Beach is now fully activated with Bazaar Meat open and a grand opening planned for early 2027. Its room rates still sit several hundred dollars below its competitive set, which is both a lingering weakness and a source of upside. The offsets are near term. The guidance implies fourth-quarter RevPAR growth slowing to mid-to-high single digits, with November the weakest month. Key West disruption extends into mid-2027, and supply of acquisitions in Sunstone's $50-$200 million target range is thin.
Capital allocation is doing much of the per-share work. Repurchases reached about $197 million year to date, up from roughly $70 million at the second-quarter report. That total includes $143.4 million of common stock at an average of $10.43 and about $54 million of preferred stock at double-digit discounts to liquidation value. Net leverage held at 2.8x, and there are no debt maturities until January 2028. Guided diluted shares fell to 183.5 million from 187 million, which flatters per-share growth. Recycling private-market asset sales into discounted equity is nonetheless a credible way to create value. Management also flagged a shift toward preferred buybacks and an option to redeem the Series G preferred.
The market setup is more complicated than the surprise implies. Earnings Whispers investor sentiment slipped from modestly positive (0.13) to slightly negative (-0.08) into the report, a notable cooling even though both readings sit near neutral. Yet the stock has been strong. Shares are up 4.0% since the open after the August report and trade 16.3% above the 200-day moving average. The stock is 20% above its mid-August low and set a 52-week high of $13.08 on November 2, now about 5.6% above the current price. That combination suggests investors had already priced in much of the improving RevPAR story while growing more cautious about what comes next.
The bottom line is that Sunstone answered the demand question emphatically. Accelerating RevPAR, a third guidance raise, strong 2027 pace and a larger expected dividend all point the right way. The unresolved issue is conversion: 10%-plus revenue growth is producing only modest margin gains. If group mix normalization and the end of the Key West renovation deliver the flow-through management expects, 2027 could validate the stock's run. If energy costs and mix keep diluting returns, the discount-buyback story will have to carry more of the load.
Read our earnings preview for Sunstone Hotel Investors, Inc.: https://www.earningswhispers.com/article/SHO/22498
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 8 hours | |
| 8 hours | |
| Oct-29 | |
| Sep-18 | |
| Aug-06 | |
| Aug-06 | |
| Jun-26 | |
| Jun-24 | |
| Jun-23 | |
| Jun-07 | |
| May-05 | |
| May-05 | |
| Mar-31 | |
| Feb-28 |
