UFP Technologies Must Show Its Margin Recovery Can Outlast A Flattering Comparison
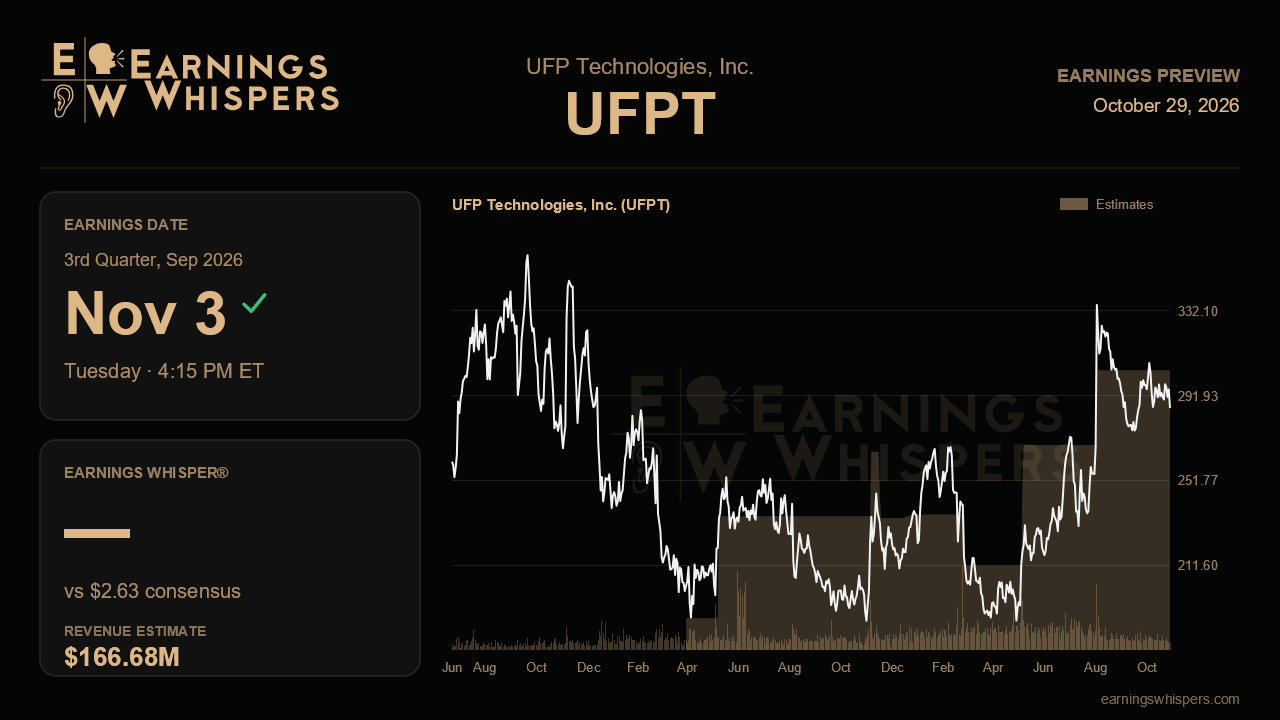
UFP Technologies heads into its third-quarter report with a curious setup. Last quarter the company posted record adjusted earnings of $2.92 a share and double-digit organic growth, yet the stock has slipped 6.2% since then while the S&P 500 gained 1.5%. The market appears to have taken management at its word when it cautioned that the blowout was partly a product of an easy comparison. The upcoming release will show whether that caution was prudent conservatism or an early warning.
Wall Street expects earnings of $2.63 a share on revenue of $166.7 million, up 10% and 7.8% from a year ago, respectively. Both figures represent a sequential step down from the $174 million and $2.92 delivered in the second quarter. That is not a sign of trouble so much as an acknowledgment of what management said on the last call: after a 12.4% organic surge, it steered investors back toward its long-term range of 6% to 9% for the rest of the fiscal year. The consensus revenue growth rate sits comfortably inside that band, which suggests analysts have built in little room for another upside surprise on the top line.
The more interesting question is margins. A year ago, the company absorbed roughly $3 million of labor inefficiency at its AJR operation in St. Charles, which dragged gross margin down to 27.7%. Management now says that problem is fully resolved, with the backlog worked down and the facility fully ramped. Gross margin has climbed steadily since, reaching 29.3% last quarter. If that level holds, the year-over-year margin comparison should be generous, and a 10% earnings growth forecast could look modest. The offset is overhead. SG&A rose to $22.8 million last quarter on higher back-office wages and roughly $1 million of extra non-cash equity compensation tied in part to the CEO transition from Jeff Bailey to Mitch Rock. Management described that spending as the new baseline, with only partial relief expected by mid-2027. Petroleum-based input inflation linked to the Iran conflict adds another wrinkle, since any lag in passing costs to customers would show up directly in gross margin.
Beyond the headline numbers, the report should offer progress checks on several catalysts introduced or reinforced last quarter. Two robotic-assisted surgery programs have launched and are expected to contribute eight figures in 2027, even as the broader robotic surgical market runs flat to down this year. Two of three Dominican Republic program transfers are complete, but the benefits have arrived more slowly than planned and the third depends on customer qualification. Evidence that growth outside the top five customers, which rose 19.7% last quarter, remains strong would also help confirm that the company is reducing its dependence on a handful of large accounts. With leverage under 1x and a pipeline of five to ten potential deals, any update on acquisitions could shift the conversation as well.
Sentiment has soured noticeably, moving from mildly bearish ahead of the last report to considerably more bearish now. The stock trades at $286, well above its 200-day moving average of about $249 but closer to the $273 low of its post-earnings range than to the $338.71 peak it touched after the June quarter. Having run up from a prior-quarter range that topped out near $279, shares have given back much of their post-earnings enthusiasm.
That cooling arguably lowers the bar. The central test is whether gross margin holds near the 29% level now that the AJR drag is gone, enough to absorb the heavier SG&A base and raw material pressure. If it does, the second quarter looks like the start of a durable earnings step-up rather than a one-time beneficiary of a soft comparison. If margins slip back, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 7 hours | |
| Aug-20 | |
| Aug-03 | |
| Aug-03 | |
| Jul-29 | |
| Jul-01 | |
| Jun-04 | |
| Jun-04 | |
| May-06 | |
| May-04 | |
| May-04 | |
| Apr-30 | |
| Mar-17 | |
| Mar-04 |
