UFP Technologies Beats On Double-Digit Organic Growth, But Slower Momentum And AJR Delays Keep Investors Wary
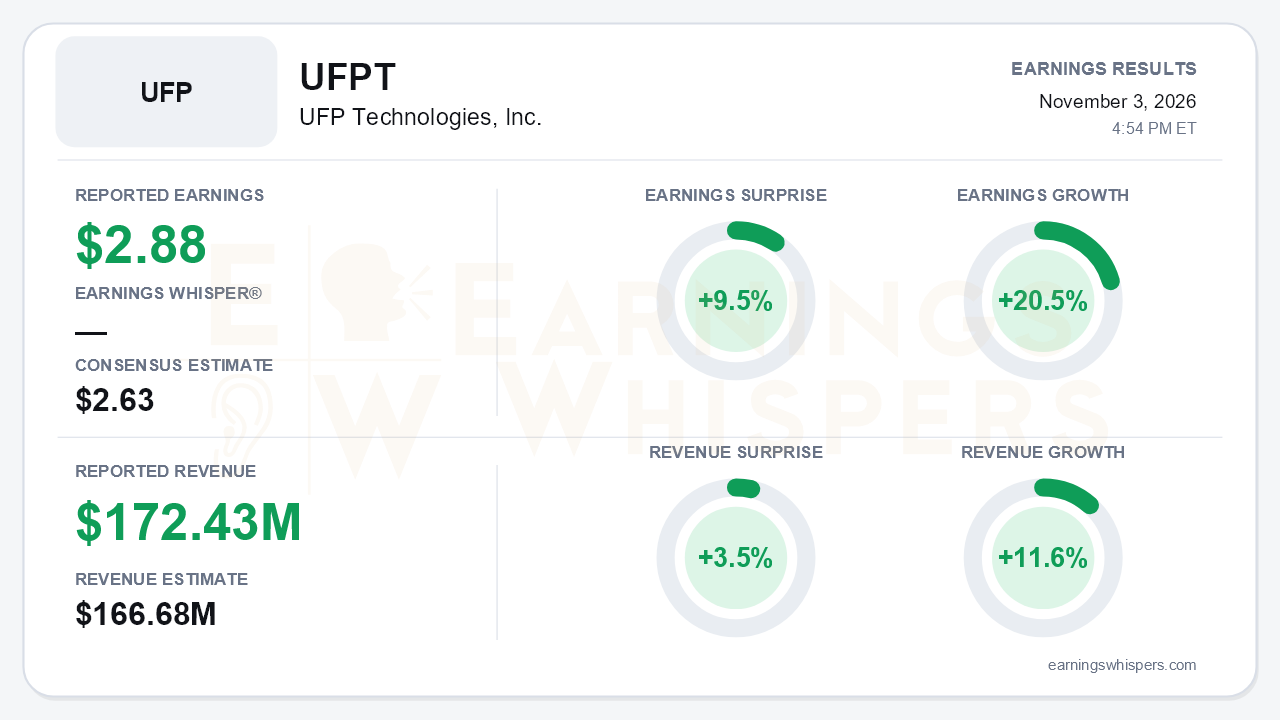
UFP Technologies delivered a clean beat in the third quarter. Adjusted EPS was $2.88, 9.5% above the $2.63 consensus and 20.5% higher than a year ago. Revenue of $172.43 million topped expectations by 3.5% and grew 11.6%, with 11.1% of that growth organic. GAAP EPS rose to $2.64 from $2.11. The central tension is that the beat came against expectations that had been set too low. On the second-quarter call, management had guided investors to expect second-half organic growth to fall back into the 6-9% range. Instead, organic growth stayed in double digits. Even so, the quarter was a step down from the record second quarter, and the market had already been marking the stock lower before the report.
The quality of the beat is good but not flawless. Gross margin expanded to 29.4% from 27.7% a year ago and edged up from 29.3% in Q2 and 28.8% in Q1. Management now says margins are "settling in at 29%" within its 28-31% range. Spending absorbed much of that gain. SG&A rose 21.4% to $23.2 million, or 13.4% of sales, and adjusted SG&A climbed to 12.0% of sales from 10.7%. Management attributed the increase to investing ahead of growth, duplicate equity costs tied to the CEO transition, and new permanent cybersecurity costs. As a result, adjusted operating income grew 14.5%, noticeably slower than adjusted net income at 21.1%. Lower interest expense filled part of the gap, falling to $1.5 million from $2.4 million as long-term debt dropped to $83.5 million from roughly $123 million at year-end. That deleveraging is real and earned. Q3 operating cash flow was $38.5 million, versus $15.6 million in Q2 and $3.2 million in Q1. Still, part of the bottom-line outperformance came from below the operating line.
Sequentially, the trend cooled. Sales slipped to $172.4 million from $174.0 million in Q2, and adjusted EPS eased from a record $2.92. Reported growth decelerated from 15.1% to 11.6%, while organic growth moved from 12.4% to 11.1%. Growth among the top five MedTech customers slowed from 14.7% to 11.7%. Adjusted operating margin was essentially flat at 17.5%, compared with 17.6% in Q2. Demand itself, however, looks broad-based. MedTech grew 12.5%, with double-digit gains in patient handling, cardiovascular, infection control and orthopedics. That breadth matters because robotic surgery, historically a key driver, remains flat-to-down for 2026.
The forward story leans on 2027 and on capital deployment:
- **Capacity and robotics:** Management added capacity at DAS Medical to support expected double-digit growth next year. It previously described the ramping robotics programs as an "eight-figure contribution" in 2027.
- **Customer win:** A top-five customer awarded UFP a supplier designation.
- **Plastics expansion:** The company acquired CI Medical in August, extending its push into medical injection molding, which builds on the 2025 TPI investment that management says has exceeded expectations.
- **Larger deals:** UFP is expanding its credit facility, using a framework of roughly 3.25x EBITDA borrowing capacity, to pursue bigger acquisitions.
Bears have legitimate ammunition, though. The AJR program transfer to the Dominican Republic is now openly behind schedule, with completion pushed to 2027. That timeline was expected in the second half of 2026 as recently as the year-end call. Q4 was also flagged as seasonally softer, with more holiday shutdowns in the Dominican Republic. Management offered no formal guidance and only reaffirmed its long-term framework of 6-9% organic and 12-18% total growth. Larger acquisitions would also reintroduce integration and leverage risk just as the balance sheet has been repaired.
Investors were not positioned for good news. Earnings Whispers sentiment fell from -0.09 at the prior report to -0.33, a meaningful shift deeper into negative territory. Shares were $280.32 at the time of the report, down 8.1% from the $305 open after the August release. The stock nonetheless remained about 12.3% above its 200-day moving average of $249.54. The longer-term uptrend is intact, but the stock has lost ground since the record Q2 print. The Earnings Whispers trend readings are mixed, with momentum positive while AVWAP remains negative. Together, they describe a stock that has been consolidating rather than breaking down.
The bottom line is that UFP delivered more than the market asked for: double-digit organic growth that beat management's own second-half framing, higher gross margins, strong cash flow and a cleaner balance sheet. The headline overstates the operating leverage, however. Elevated SG&A and the sequential dip from Q2 show a business investing heavily while growth moderates from its peak. Recurring AJR slippage and the absence of guidance give skeptics reason to wait for 2027 proof points. With sentiment soured and shares off their post-Q2 levels, the setup now hinges on whether the robotics ramp, DAS capacity and acquisition pipeline turn management's optimism into visible acceleration.
Read our earnings preview for UFP Technologies, Inc.: https://www.earningswhispers.com/article/UFPT/22511
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Oct-29 | |
| Aug-20 | |
| Aug-03 | |
| Aug-03 | |
| Jul-29 | |
| Jul-01 | |
| Jun-04 | |
| Jun-04 | |
| May-06 | |
| May-04 | |
| May-04 |
